Who May Be Exempt From the VA Funding Fee?
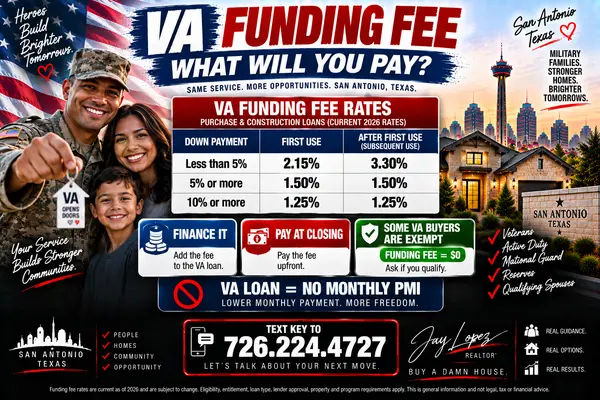
In a different blog, we broke down the VA funding fee—what it is, how much it can cost, and how it works.
But there's another question that can potentially save a VA buyer thousands of dollars:
🇺🇸 DO I HAVE TO PAY THE VA FUNDING FEE AT ALL?
Because some eligible VA borrowers don't.
Under current VA guidance, certain Veterans, service members, and surviving spouses are exempt from paying the VA funding fee.
And this isn't something you want to discover three weeks after closing.
Let's break it down.
First: What Is the VA Funding Fee?
The VA funding fee is generally a one-time payment associated with VA-backed and VA direct home loans.
It helps offset the cost of the VA home loan program to taxpayers.
For borrowers who aren't exempt, the amount varies depending on factors such as:
Loan type
Loan amount
Down payment
and
Whether you've used your VA home loan benefit before.
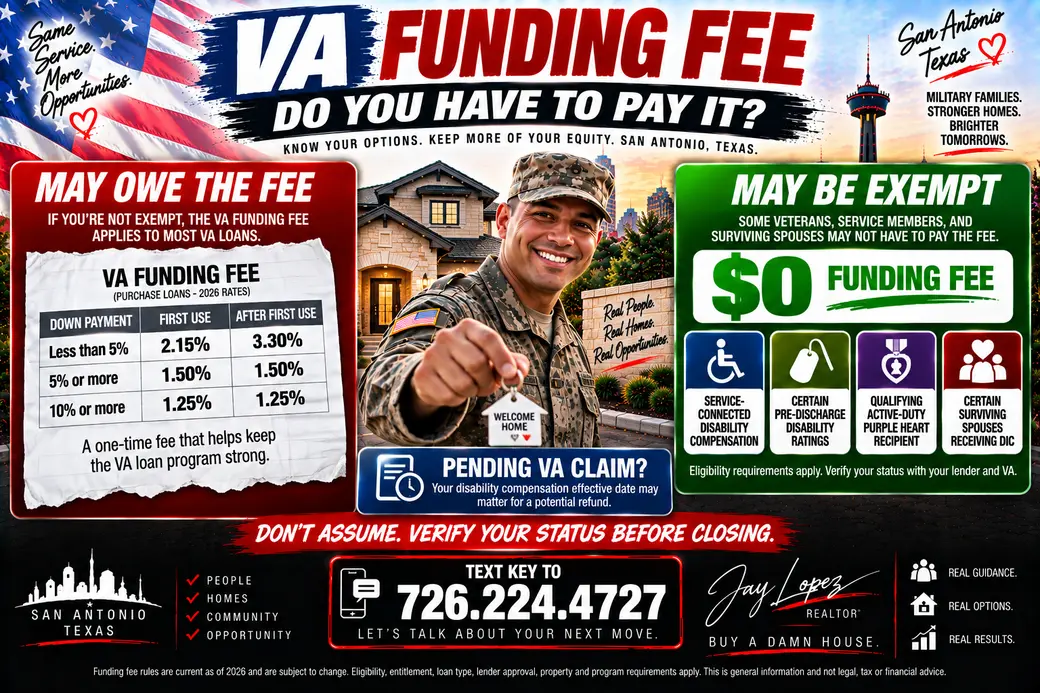
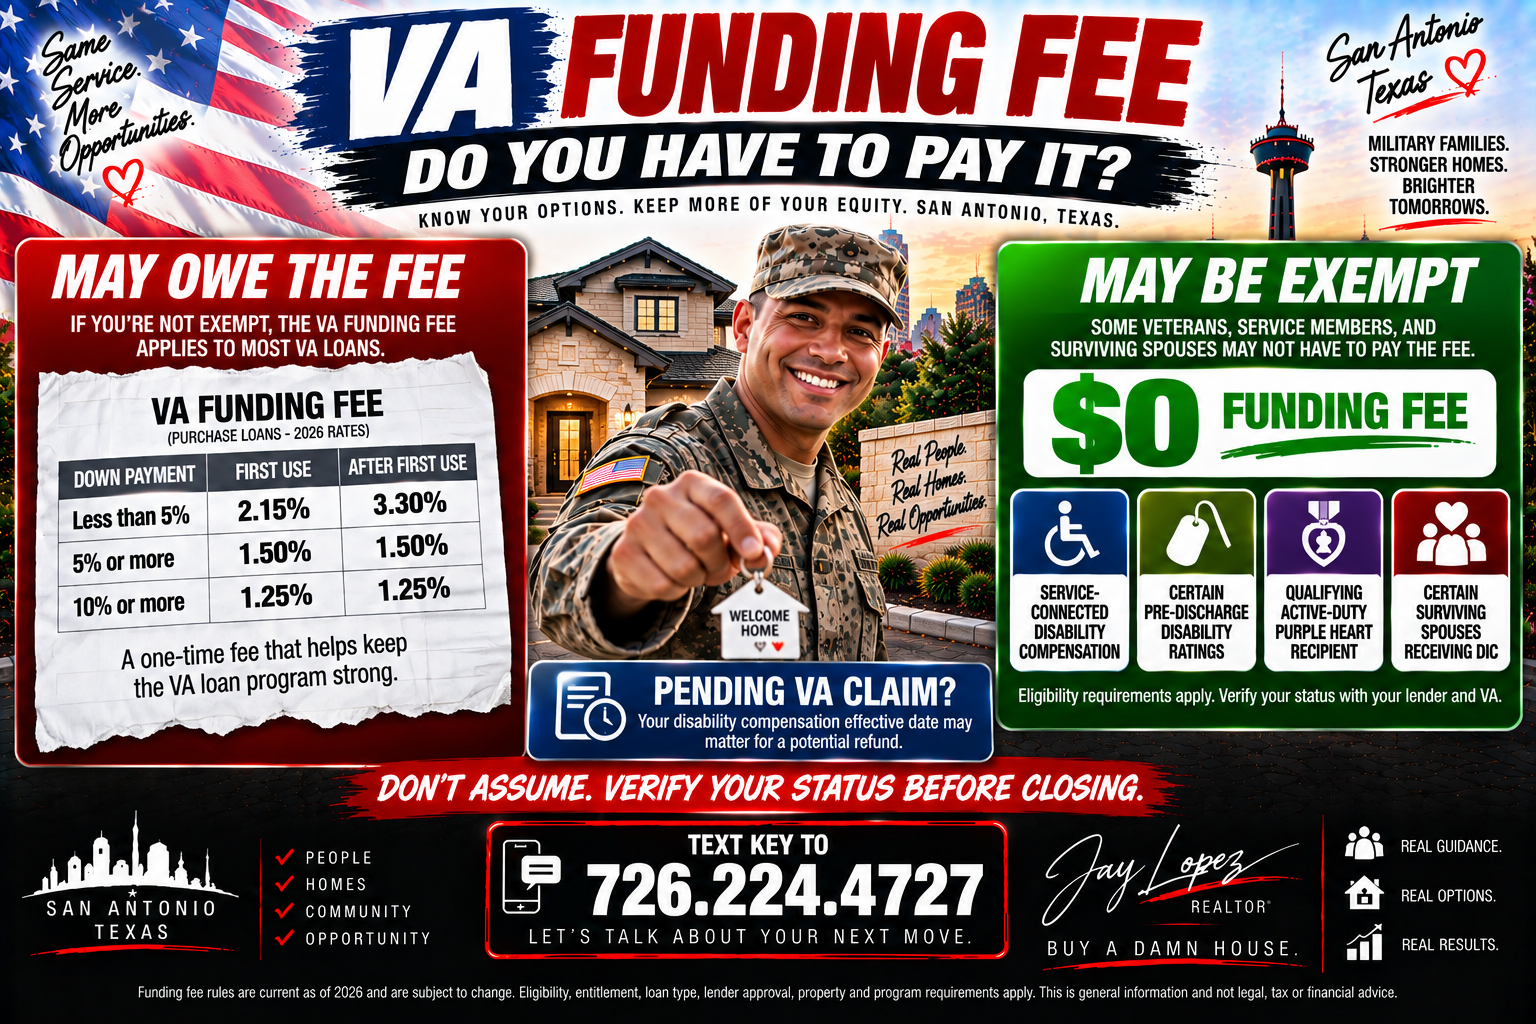
VA's current purchase-loan funding fees range from 1.25% to 3.30%, depending on down payment and whether it's a first or subsequent use.
But for an exempt borrower?
FUNDING FEE = $0
That's a pretty important distinction.
Who Is Currently Exempt?
According to the Department of Veterans Affairs, you won't have to pay the VA funding fee if one of several specific circumstances applies.
Let's go through them one at a time.
🇺🇸 EXEMPTION #1: You're Receiving VA Compensation for a Service-Connected Disability
This is probably the exemption most Veterans are familiar with.
If you're receiving VA compensation for a:
SERVICE-CONNECTED DISABILITY
you may be exempt from the VA funding fee.
And here's something important:
VA's current exemption rule does not say:
“You must be 100% disabled.”
That's a common misunderstanding.
The relevant question is whether you meet VA's exemption requirements—not whether you've reached some assumed disability percentage.
🇺🇸 EXEMPTION #2: You're Eligible for VA Disability Compensation but Receive Retirement or Active-Duty Pay Instead
This one is easy to overlook.
VA also provides an exemption if you're eligible to receive VA compensation for a service-connected disability but you're receiving retirement pay or active-duty pay instead.
So don't assume:
“There's no VA disability payment hitting my bank account, so I'm not exempt.”
Your actual VA eligibility status matters.
🇺🇸 EXEMPTION #3: Certain Surviving Spouses Receiving DIC
Some surviving spouses may also be exempt.
VA currently lists a surviving spouse receiving:
Dependency and Indemnity Compensation — DIC
as exempt from the funding fee.
DIC is a VA survivor benefit available in qualifying circumstances.
If you're a surviving spouse using the VA home loan benefit, have your funding-fee status verified rather than assuming the standard fee applies.
🇺🇸 EXEMPTION #4: Certain Service Members With a Pre-Discharge Disability Rating
This one is especially important for service members transitioning out of the military.
A service member may be exempt if, before the loan closing date, they have received a proposed or memorandum rating showing eligibility for compensation based on a pre-discharge claim.
Timing matters here.
A lot.
The key phrase is:
BEFORE THE LOAN CLOSING DATE.
🇺🇸 EXEMPTION #5: Certain Active-Duty Purple Heart Recipients
An active-duty member of the Armed Forces may also be exempt if they provide evidence, on or before the loan closing date, that they received a:
💜 PURPLE HEART
VA specifically includes this category in its current funding-fee exemption rules.
Again:
DOCUMENTATION + TIMING MATTER.
Does Every Veteran With a Disability Automatically Get the Exemption?
Don't make that assumption.
What matters is your VA-recognized status and whether you meet the applicable funding-fee exemption requirements.
That's why the correct question isn't:
“Do I have a disability?”
It's:
“Does VA currently show me as exempt from the funding fee?”
Let VA and your lender verify that.
Where Do You See Your Funding-Fee Status?
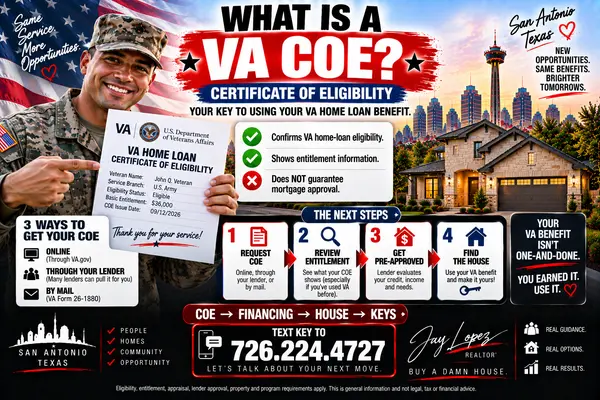
Remember our article on the:
Certificate of Eligibility — COE?
This is another reason that document matters.
Your lender should determine whether you're exempt before closing.
VA guidance specifically tells lenders to ensure that a borrower's exemption status is established before loan closing and to exercise due diligence when information suggests an exemption may apply.
So if you believe you're exempt:
SAY SOMETHING EARLY.
Don't wait until you're sitting at the closing table.
“But My COE Doesn't Show Me as Exempt.”
Don't just shrug and pay the fee.
😂
If you believe you're eligible for an exemption but your loan paperwork doesn't reflect it, bring it up with your lender.
There may be additional documentation or VA verification needed.
The important thing is:
VERIFY BEFORE CLOSING WHENEVER POSSIBLE.
VA specifically cautions lenders against simply telling a borrower who believes they're exempt to close, pay the fee, and request a refund later. Refund determinations are borrower-specific and aren't guaranteed.
That's an important detail.
What If My VA Disability Claim Is Still Pending?
Now we get into one of the most important situations.
Imagine:
You're buying a house.
Your VA disability claim is pending.
You're not currently shown as funding-fee exempt.
You close on the house and pay the funding fee.
Then later:
VA AWARDS YOUR SERVICE-CONNECTED DISABILITY COMPENSATION.
Are you out of luck?
NOT NECESSARILY.
VA says you may qualify for a funding-fee refund if you're later awarded VA compensation for a service-connected disability and the effective date of that compensation is retroactive to before the date you closed the loan.
That effective date is critical.
Example: A Potential Funding-Fee Refund
Let's say you close on your San Antonio home in:
June
You pay a:
$7,000 VA funding fee
Later, VA approves your service-connected disability compensation.
But the effective date of the award is:
April
That means the effective date occurred before your June closing.
Under VA's current guidance, that could make you eligible for a refund of the funding fee.
That's worth checking.
But Don't Assume Every Later Disability Decision Creates a Refund
This is important.
The fact that VA awards disability compensation after closing does not automatically mean the funding fee gets refunded.
The effective date of the compensation matters.
VA says the effective date must be retroactive to before the loan closing date for this type of refund eligibility.
So:
Award date isn't the only date that matters.
EFFECTIVE DATE MATTERS.
Special Warning for Pre-Discharge Ratings
There's another timing distinction worth understanding.
VA says that if a service member receives a proposed or memorandum rating after the loan closing date, they still must pay the funding fee and aren't eligible for a refund based solely on that later proposed or memorandum rating.
That's different from the retroactive compensation situation we just discussed.
Which is exactly why:
DON'T GUESS ABOUT THIS STUFF.
Have your specific situation reviewed.
How Much Could an Exemption Save?
Potentially quite a bit.
Let's use a simplified example.
Suppose your VA loan amount before the funding fee is:
$350,000
First use.
Less than 5% down.
The current funding-fee rate is:
2.15%
That would equal:
$7,525
for a non-exempt borrower.
An exempt borrower:
$0 FUNDING FEE
That's a $7,525 difference in this example.
Subsequent Use Can Make the Difference Even Larger
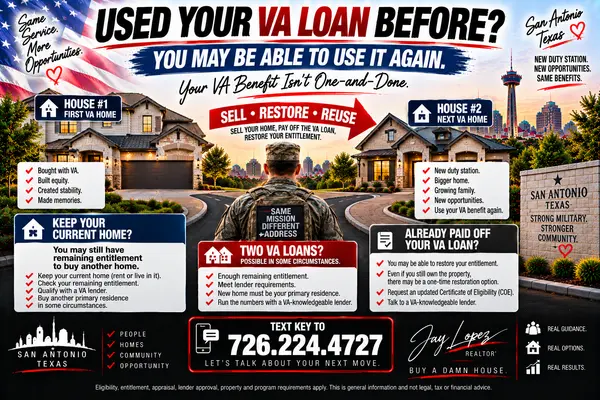
Now imagine that same $350,000 base loan amount, but this is a subsequent VA use with less than 5% down.
Current funding-fee rate:
3.30%
That equals:
$11,550.
If the borrower qualifies for a funding-fee exemption?
$0
Now you understand why I'm spending an entire blog article on this.
😂
Does Being Exempt Change the VA Loan Benefit?
The exemption removes the funding fee.
It doesn't mean you're suddenly using a different VA loan program.
You still have to satisfy the applicable:
VA requirements
Lender underwriting
Property requirements
Appraisal requirements
and other transaction requirements.
Funding-fee exemption does not equal:
AUTOMATIC LOAN APPROVAL.
Does Funding-Fee Exemption Mean $0 Closing Costs?
NO.
This is another important distinction.
Funding fee:
$0 if exempt
does not mean:
Everything at closing = $0.
You may still have other transaction expenses such as:
Closing costs
Prepaid taxes
Insurance
Earnest money
Option fee
Home inspection
and other applicable expenses.
Seller or builder credits may sometimes help with allowable costs when properly structured, but those are separate from your funding-fee exemption. VA says buyers and sellers can negotiate many closing costs, while seller concessions are subject to separate VA rules.
Does an Exempt VA Buyer Still Have No Monthly PMI?
Yes—the VA home loan program itself doesn't require monthly mortgage insurance, regardless of whether the borrower owes a funding fee.
So an exempt qualifying borrower may potentially have:
No VA-required down payment
subject to eligibility, entitlement, appraisal, lender and transaction requirements,
plus:
NO MONTHLY PMI
and:
NO VA FUNDING FEE.
That's a combination worth understanding.
What If the Funding Fee Was Accidentally Charged?
If you believe you were exempt and a funding fee was charged anyway:
DON'T IGNORE IT.
Contact your lender and VA.
VA specifically provides a process for borrowers who believe they're eligible for a funding-fee refund and directs them to their VA regional loan center.
The answer depends on the circumstances, but it's absolutely worth investigating.
Don't Wait Until Closing Day
Here's what I want every San Antonio VA buyer to do.
Early in the loan process, ask:
“AM I EXEMPT FROM THE VA FUNDING FEE?”
Not:
“I think I'm exempt.”
Not:
“My buddy didn't have to pay it.”
Not:
“I'm pretty sure my disability rating takes care of it.”
😂
Ask your lender to verify it.
VA Funding-Fee Exemption Checklist
If you think you might qualify:
🇺🇸 1. TELL YOUR LENDER EARLY
Don't wait until closing.
📄 2. REVIEW YOUR COE
Make sure your VA information is current.
♿ 3. VERIFY YOUR VA COMPENSATION STATUS
Don't rely on assumptions.
💜 4. ACTIVE-DUTY PURPLE HEART RECIPIENT?
Make sure the required evidence is provided before closing.
🎖️ 5. TRANSITIONING OUT WITH A PRE-DISCHARGE CLAIM?
Ask whether your proposed or memorandum rating was issued before closing.
📅 6. DISABILITY CLAIM PENDING?
Understand that the effective date may matter for a potential future refund.
💰 7. ALREADY PAID A FUNDING FEE BUT THINK YOU WERE EXEMPT?
Ask VA whether you may qualify for a refund.
The Biggest Mistake?
Assuming.
The VA funding fee can represent thousands of dollars.
So don't assume:
“Everybody pays it.”
And don't assume:
“I'm a Veteran, so I'm automatically exempt.”
Neither statement is correct.
Your individual VA status determines the answer.
The Bottom Line
Under current VA guidance, funding-fee exemptions can apply to qualifying borrowers including:
🇺🇸 Veterans receiving service-connected disability compensation
🇺🇸 Those eligible for that compensation but receiving retirement or active-duty pay instead
🇺🇸 Certain surviving spouses receiving DIC
🇺🇸 Certain service members with qualifying pre-discharge disability ratings before closing
💜 Active-duty Armed Forces members who provide timely evidence of receiving a Purple Heart.
And if you're later awarded qualifying disability compensation with an effective date retroactive to before your loan closing, you may potentially be eligible for a funding-fee refund.
VERIFY IT.
Because the difference could be:
THOUSANDS OF DOLLARS.
Buying With VA in San Antonio?
Let's make sure you understand the benefit before you start shopping.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
First VA purchase or used VA before
and
Your approximate buying timeline.
Example:
“KEY — Veteran — first VA purchase — looking this winter.”
I'll help you get the home-buying game plan started, and your VA lender can verify your financing and funding-fee status.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house. 🇺🇸🔑
Featured Image Concept
Let's make this one visually different from #31.
Main Headline:
🇺🇸 VA FUNDING FEE
DO YOU HAVE TO PAY IT?
Split the image down the middle.
LEFT — RED
MAY OWE THE FEE
Large funding-fee receipt graphic:
2.15% • 3.30% • ETC.
RIGHT — GREEN
MAY BE EXEMPT
Huge:
$0 FUNDING FEE
Underneath, four simple exemption icons:
♿ Service-Connected VA Compensation
🎖️ Certain Pre-Discharge Disability Ratings
💜 Qualifying Active-Duty Purple Heart Recipient
🇺🇸 Certain Surviving Spouses Receiving DIC
Center bottom callout:
PENDING VA CLAIM?
Your disability compensation effective date may matter for a refund.
Background: military/Veteran home buyer holding keys outside a modern San Antonio home, with subtle American flag and Tower of the Americas.
Bottom:
DON'T ASSUME. VERIFY YOUR STATUS BEFORE CLOSING.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts