Should You Buy a House or Keep Renting in San Antonio?
“Am I wasting money by renting?”
That's one of the most common questions I hear.
And you might expect a Realtor to immediately say:
“YES! STOP RENTING AND BUY A HOUSE!”
But that's not always the right answer.
Sometimes buying makes sense.
Sometimes renting makes sense.
Sometimes you're not ready to buy today, but you could be six months from now.
The important thing is to stop making the decision based on slogans like:
“Renting is throwing money away.”
or
“Buying is too expensive right now.”
Instead, let's look at your actual situation.
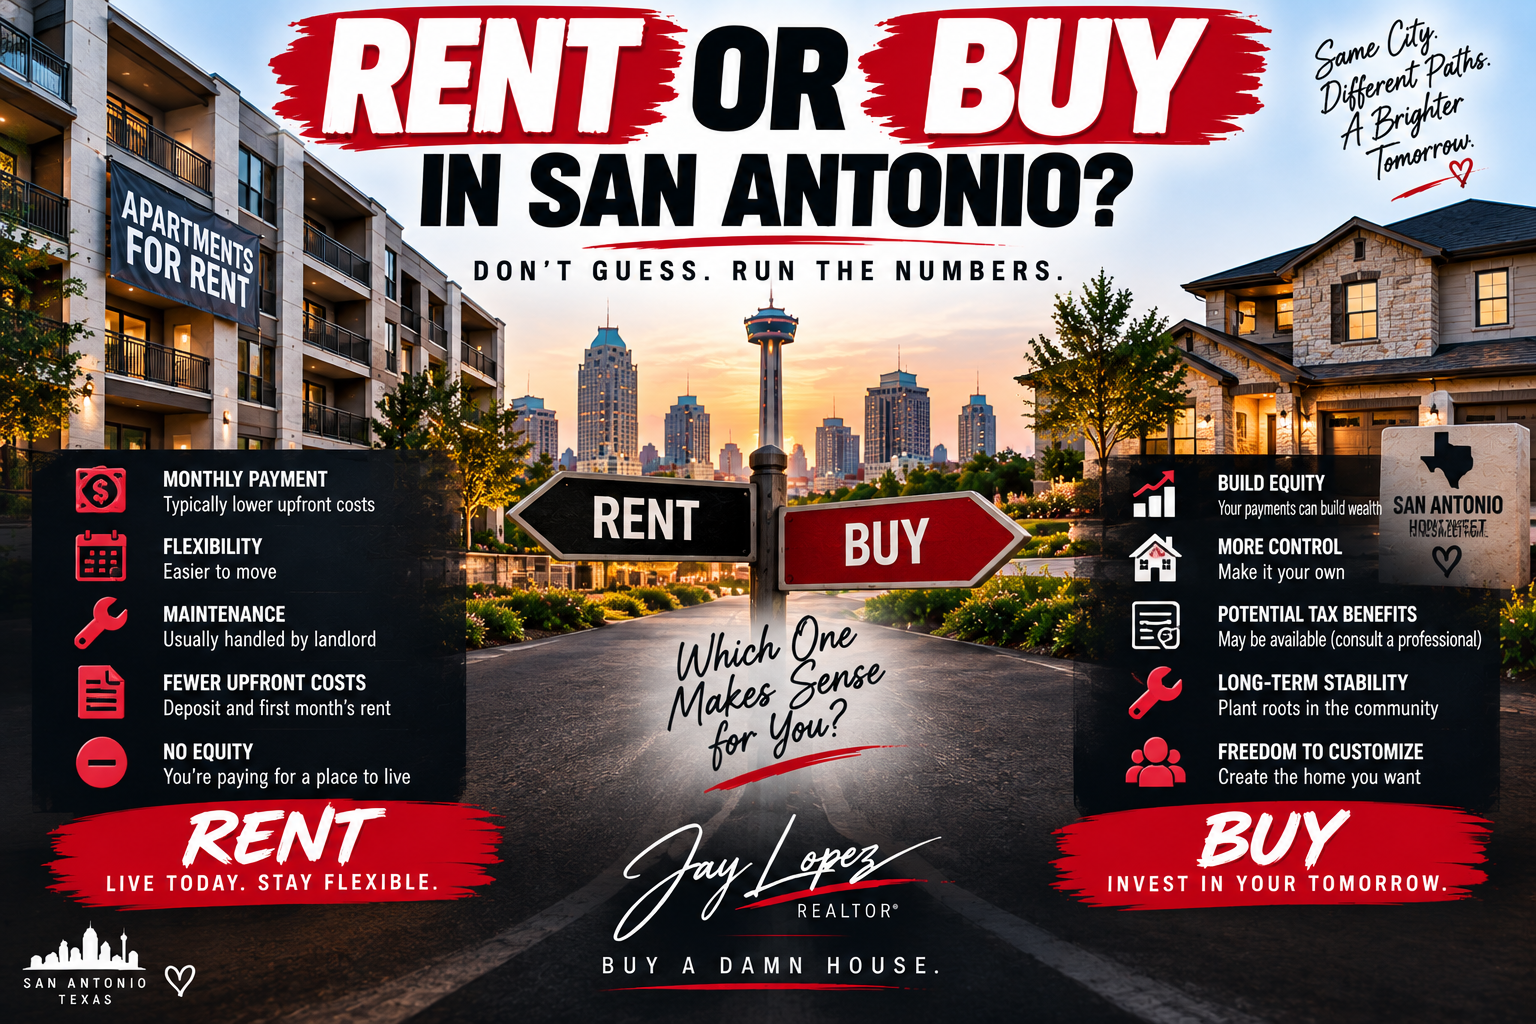
Because whether you should rent or buy in San Antonio depends on much more than comparing your rent payment with somebody else's mortgage payment.
1. Start With Your Current Rent
Let's start with a simple question:
What are you paying in rent right now?
Maybe it's:
$1,400 a month.
Maybe $1,800.
Maybe $2,200.
Maybe more.
Now multiply that by 12.
A $1,800 monthly rent payment equals:
$21,600 per year.
That doesn't automatically mean you should buy a house.
Rent provides something valuable:
A place to live.
But knowing what you're already comfortable spending each month gives us a starting point for evaluating your options.
2. Don't Compare Rent to Only Principal and Interest
This is where online rent-versus-buy comparisons can become misleading.
Someone says:
“Why pay $1,800 in rent when the mortgage is only $1,700?”
Not so fast.
A homeowner's monthly housing expense can include more than principal and interest.
Depending on the property and financing, you may also have:
- Property taxes
- Homeowners insurance
- Mortgage insurance when applicable
- HOA dues
- Maintenance expenses
- Other ownership costs
So we need to compare your rent with a realistic estimate of homeownership costs, not an incomplete mortgage number.
3. Renting Gives You Flexibility
This is one of renting's biggest advantages.
If your job may move next year...
If you're planning to leave San Antonio...
If you're going through a major life change...
If you simply aren't sure where you want to live...
Renting may provide flexibility that homeownership doesn't.
At the end of the lease, you may have the ability to move without having to sell a property.
That's valuable.
Buying a house shouldn't automatically be viewed as the right move just because you qualify for one.
4. Homeownership Can Give You More Control
On the other hand, renters are living in someone else's property.
Your ability to make changes may be limited by the lease and property owner.
Homeownership can provide greater control over your living space, subject to laws, deed restrictions, HOA requirements and other applicable limitations.
Want to paint the bedroom?
Change the flooring?
Build out the backyard?
Create an office?
Replace those cabinets you've hated since the day you moved in?
As the owner, you generally have far more control over those decisions.
Just remember:
You also get to pay for them. 😂
5. Buying May Allow You to Build Equity
When you make mortgage payments, part of the principal-and-interest payment generally goes toward reducing the loan principal.
Over time, that can contribute to equity.
Your property's market value can also change.
If the property increases in value, your equity may increase.
If its value falls, the opposite can happen.
That's important because you will sometimes hear:
“Buy a house because it's guaranteed to go up.”
No.
Real estate values can rise or fall, and future appreciation isn't guaranteed.
Homeownership may create an opportunity to build equity over time, but buyers should understand the risks as well as the potential benefits.
6. Buying Requires More Money Upfront
Renting often involves costs such as a security deposit, application fees and the initial rent payment.
Buying can involve significantly more.
Depending on your financing and transaction, you may encounter:
Down payment
Earnest money
Option fee
Inspection
Appraisal-related costs
Closing costs
Prepaid expenses
Insurance
and other costs.
As we discussed in Blog #4, you don't necessarily need a 20% down payment.
But that doesn't mean buying requires no money.
Understanding the upfront costs is an important part of deciding whether you're ready.
7. Homeowners Need an Emergency Fund
Here's something that's easy to forget when you're looking at beautiful houses online.
When you rent and the air conditioner stops working:
You call the landlord.
When you own the house:
Congratulations. You are the landlord. 😂
Repairs and maintenance are part of homeownership.
That doesn't mean something breaks every week.
But buyers should have financial room for maintenance and unexpected expenses.
If buying the house would leave your bank account at exactly $0, we should probably have another conversation.
8. Your Timeline Matters
How long do you expect to stay in the home?
If you expect to move again soon, transaction costs associated with buying and eventually selling may affect whether purchasing makes sense.
If you're planning to stay in San Antonio for years, the calculation may look different.
There's no universal rule that says:
“If you stay exactly X years, buying always wins.”
Your property, financing, future market conditions and transaction costs all matter.
But your expected timeline should absolutely be part of the decision.
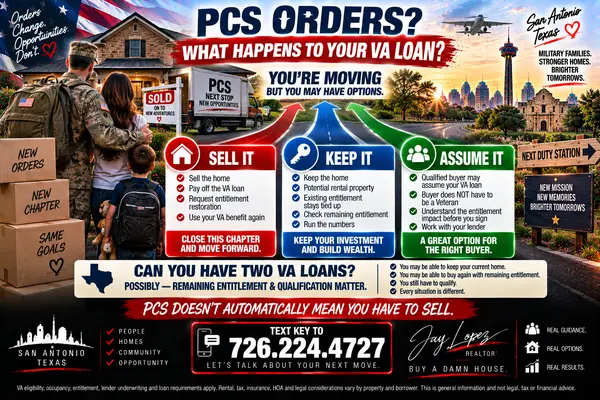
9. Military Buyers Have Another Variable: PCS Orders 🇺🇸
San Antonio is a military city.
For active-duty buyers assigned to JBSA Lackland, Randolph, Fort Sam Houston or another installation, potential PCS timing deserves serious consideration.
You might ask:
How long do I expect to be stationed here?
What would happen to the property if I PCS?
Would selling make sense?
Could renting the property later be an option?
How would my VA entitlement be affected by future plans?
Buying while in the military can absolutely make sense for some households.
But it should be part of a larger plan—not simply:
“My BAH is $____, so I should buy.”
10. Your Monthly Payment Isn't the Only Financial Question
Let's say:
Rent = $1,900
Estimated homeownership expense = $2,100
Does that mean renting automatically wins because it's $200 cheaper?
Not necessarily.
What about:
Upfront costs?
Maintenance?
Equity?
Flexibility?
Future plans?
Tax considerations?
Opportunity cost of your down payment?
Potential changes in rent?
There's more to the decision than finding the smaller monthly number.
11. Your Lifestyle Matters
Maybe you want a backyard for the dogs.
Maybe you're tired of apartment parking.
Maybe you need an office.
Maybe you want more privacy.
Maybe you want to customize your home.
Maybe you absolutely do not want to spend Saturdays maintaining a yard. 😂
Those things matter.
A home isn't just a spreadsheet.
It's where you're going to live.
Your decision should make sense financially and fit your lifestyle.
12. Don't Buy Because Somebody Pressured You
Your parents bought their first house at 24.
Great.
Your coworker just bought one.
Awesome.
Your friend keeps telling you renting is stupid.
Good for them.
They aren't paying your mortgage.
Buying a house is a major financial commitment.
Do it because the numbers and timing make sense for you, not because you feel behind somebody else.
13. Don't Keep Renting Just Because Buying Feels Complicated
This is the other side of it.
Some people continue renting because:
“Buying seems overwhelming.”
That's understandable.
But complicated doesn't mean impossible.
You don't have to understand the entire transaction before starting.
That's what your Realtor, lender, title company, inspector and other professionals are there to help you navigate.
Start with one question:
What would buying actually look like for me?
Then decide.
14. What If Your Lease Ends in Six Months?
This is actually a great time to start exploring.
Not because you need to buy a house tomorrow.
Because you have time.
If you're ready now, great.
If you need to improve credit, you have time.
If you need to save more money, you have time.
If you need to pay down debt, you have time.
If you decide buying isn't right for you, you can renew the lease knowing you actually evaluated the alternative.
That's much better than waiting until:
“My lease ends in 27 days. Can we buy a house?” 😂
15. Run the Numbers Before You Renew
This is the biggest takeaway from this entire article.
I'm not telling you:
DON'T RENT.
I'm telling you:
DON'T AUTOMATICALLY RENEW WITHOUT CHECKING YOUR OPTIONS.
Find out:
What you may qualify for.
How much cash you might need.
What monthly payment you're comfortable with.
What homes are available in that range.
Whether buying fits your plans.
Then make the decision.
Maybe the answer is:
Buy.
Maybe it's:
Rent another year.
Maybe it's:
Let's spend six months getting ready.
All three are better than guessing.
Renting or Buying? Let's Find Out What Your Numbers Look Like
If you're renting in San Antonio and your lease is coming up, send me three things:
1. What are you paying in rent?
2. When does your lease end?
3. What monthly housing payment would you be comfortable with?
From there, we can start figuring out whether exploring homeownership makes sense.
No need to convince yourself you can buy.
And no need to convince yourself you can't.
Let's get the information first.
🔑 Text KEY to 726.224.4727
Tell me:
“My lease is coming up.”
We'll start there.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts