From Pre-Approval to Closing: What Actually Happens When You Buy a House in San Antonio?
You've been pre-approved.
Awesome.
Now what?
Do we start looking at houses?
When do you make an offer?
When does the inspection happen?
What's an option period?
When does the lender order the appraisal?
When do you actually give somebody money?
And the question everybody really wants answered:
WHEN DO I GET THE KEYS? 🔑😂
Buying your first home can seem complicated because there are a lot of moving pieces happening at the same time.
But when you break the process into individual steps, it becomes much easier to understand.
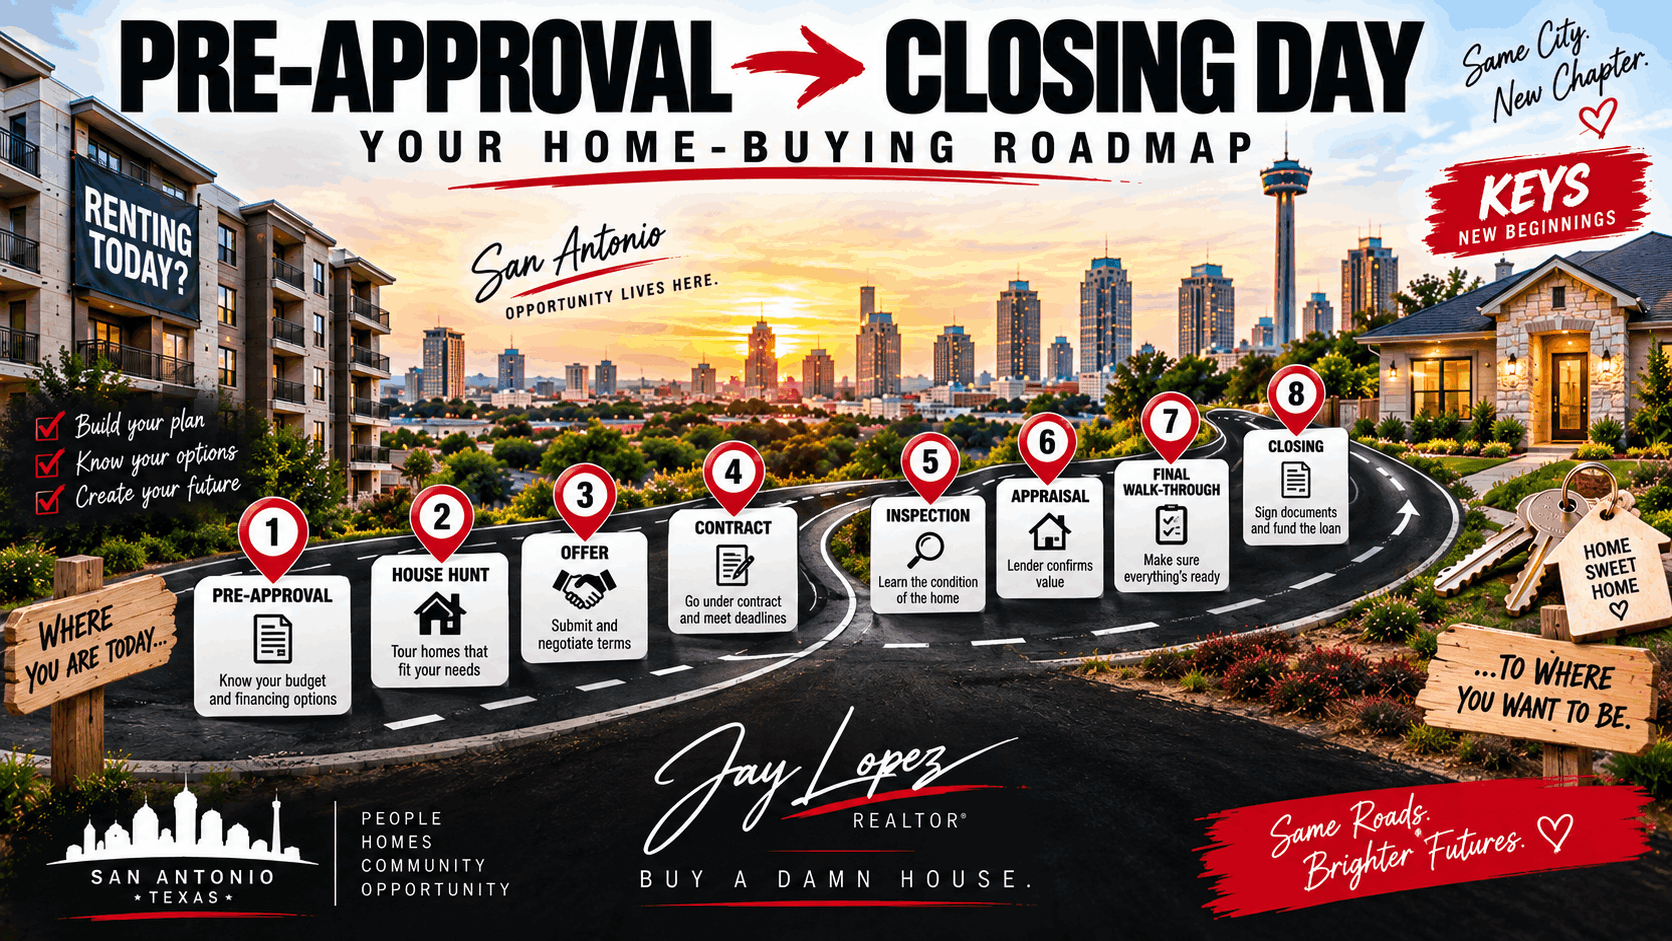
So let's walk through a typical financed home purchase in Texas—from getting pre-approved all the way to closing day.
Step 1: Talk With a Lender and Get Pre-Approved
Before we spend every Saturday touring houses, let's figure out the financial side.
A mortgage lender can review information about your finances and determine what financing options and purchase range may be available to you.
Depending on your circumstances, that can involve reviewing things such as:
- Income
- Employment
- Credit
- Assets
- Existing debt
- Down-payment funds
- Loan-program eligibility
Your lender may discuss conventional, FHA, VA, USDA or other available financing depending on your situation.
Why does pre-approval matter?
Because it gives us a realistic place to start.
Instead of scrolling through every house in San Antonio, we can focus on properties that fit your financing and budget.
Step 2: Decide What You Actually Want
Now we start building the wish list.
Think about:
Price range
Comfortable monthly payment
Location
Bedrooms
Bathrooms
Square footage
New construction or resale
Yard
Commute
Garage
HOA preferences
Must-have features
And here's what usually happens:
Your original list changes after we tour a few houses. 😂
That's completely normal.
Maybe you thought you needed 2,500 square feet.
Then you realize you'd rather have 2,000 square feet with a better layout.
Maybe you wanted a giant backyard until you remembered who has to mow it.
The search helps us figure out what actually matters.
Step 3: Start House Hunting 🏠
Now we get to the part everybody has been waiting for.
Looking at houses.
We'll search available properties that fit your criteria and start touring the ones that make sense.
Around San Antonio, that could mean looking throughout the city or surrounding communities depending on your needs.
You may also compare:
Resale homes
versus
New construction
Don't just look at the countertops and flooring.
Pay attention to:
- Layout
- Property condition
- Storage
- Location
- Commute
- Taxes
- HOA considerations
- Potential maintenance
- Your long-term plans
A beautiful house that doesn't fit your life isn't necessarily the right house.
Step 4: You Find THE ONE 👀
Eventually it happens.
You walk through a house and start doing something dangerous:
Mentally placing your furniture. 😂
You know exactly where the TV goes.
You've already claimed a bedroom as the office.
Someone is planning backyard furniture.
Now it's time to talk about making an offer.
But before we just throw a number at the seller, we look at the whole situation.
Step 5: Build the Offer
An offer involves more than:
“We'll pay $350,000.”
Depending on the transaction, we'll consider terms involving things such as:
- Purchase price
- Financing
- Earnest money
- Option period and option fee
- Closing date
- Seller contributions, if requested
- Personal property when applicable
- Addenda
- Other negotiated contract terms
Market conditions matter too.
If several buyers want the same property, our strategy may look different than it would for a home that's been sitting on the market.
The goal isn't necessarily to make the highest offer possible.
It's to structure an offer that makes sense for you and the circumstances.
Step 6: Negotiation
The seller can respond to an offer in several ways.
They might accept it.
They might reject it.
Or they might propose different terms.
This is where negotiations can involve:
Price
Closing date
Seller contributions
Option terms
Repairs or other negotiated items later in the process
and other contract provisions.
Once both sides reach agreement and the contract is properly executed, we're officially:
UNDER CONTRACT. 🎉
Now the clock starts moving.
Step 7: Earnest Money and Option Fee
Texas contracts contain important deadlines.
If your contract provides for earnest money and an option fee, those funds must be delivered according to the contract.
Don't think:
“I'll get around to that later this week.”
Deadlines matter.
Your Realtor should tell you:
How much is due
Where it goes
and
When it must be delivered
Follow those instructions carefully.
Step 8: Schedule the Home Inspection
If you've negotiated a termination option, the option period is commonly when buyers conduct inspections and further evaluate the property.
You'll generally want to hire a qualified home inspector.
Depending on the property, buyers may also consider additional specialized inspections or evaluations.
The inspector's job isn't to tell you:
“Buy this house.”
or
“Don't buy this house.”
The inspection provides information about the condition of the property.
Then we decide what to do with that information.
Step 9: Review the Inspection Results
Home inspection reports can look terrifying.
Especially for first-time buyers.
You might receive a report that's dozens of pages long and immediately think:
“THIS HOUSE IS FALLING APART!”
Sometimes the report contains serious concerns.
Other times it contains routine maintenance, smaller defects and items the inspector is required to document.
We'll review the findings and discuss your options under the contract.
Depending on the circumstances and contract rights, buyers may consider issues involving repairs, negotiations, further evaluations or other available options.
The important thing is:
Don't panic just because the report is long.
Understand what it actually says.
Step 10: Your Loan Keeps Moving
While we're working on the property side, your lender is working on the mortgage.
This is where I need you to remember one important rule:
DON'T DO ANYTHING WEIRD WITH YOUR MONEY. 😂
This is generally not the time to:
Buy a new truck.
Finance furniture.
Open three credit cards.
Quit your job.
Co-sign a loan.
Move large amounts of money around without documentation or explanation.
Before making a significant financial change:
Ask your lender.
Your loan isn't finished simply because you received a pre-approval.
Step 11: The Appraisal
For most financed transactions, the lender will require an appraisal.
The appraisal helps the lender evaluate the property's value in connection with the mortgage.
Remember:
Inspection = primarily evaluates condition.
Appraisal = primarily evaluates value for the lending process.
They are different.
If the appraisal supports the transaction, we continue moving forward.
If there's an appraisal issue, the next steps depend on the financing, contract provisions and circumstances.
Your Realtor and lender can help explain the available options.
Step 12: Title Work Is Happening Too
While you're thinking about inspections, moving boxes and furniture, there's another important process happening behind the scenes.
The title company is working on the transaction.
Depending on the transaction, title professionals may handle matters involving:
- Title examination
- Title commitments
- Closing documents
- Escrow
- Funds
- Coordination among parties
- Title insurance
- Settlement and closing
If the title company sends you something you don't understand:
Ask questions.
Never be embarrassed to ask what a document means before signing it.
Step 13: Homeowners Insurance
Your lender will generally require homeowners insurance for a financed purchase.
Don't wait until the last minute to start shopping for coverage.
Insurance premiums can vary.
Getting quotes earlier can also help you better understand your expected housing expenses.
Remember what we've discussed in the affordability blogs:
The mortgage isn't just principal and interest.
Insurance can affect your overall monthly housing cost.
Step 14: Loan Underwriting and Final Approval
Your loan moves through underwriting.
The underwriter evaluates whether the loan satisfies the applicable lending requirements.
You may be asked for additional documents.
This does not automatically mean something is wrong.
Mortgage underwriting can involve requests for updated or additional information.
If the lender asks for something:
Respond quickly.
Don't leave the request sitting in your inbox for four days because you're busy.
Everyone is trying to get you to the same place:
Closing.
Step 15: Review Your Closing Disclosure
For many mortgage transactions, borrowers receive a Closing Disclosure before consummation, subject to federal timing requirements.
This document provides important information about the loan and closing costs.
Review it.
Don't just scroll to the bottom and look for a signature line.
Compare the information with what you've been discussing with your lender and ask about anything you don't understand.
This is your mortgage.
You should know what you're agreeing to.
Step 16: Final Walk-Through 🏠
We're getting close.
Before closing, buyers generally conduct a final walk-through.
This isn't intended to be another full inspection.
It's an opportunity to look at the property before closing and make sure there haven't been unexpected material changes and that appropriate agreed matters have been addressed.
Walk through the property.
Pay attention.
If something doesn't look right:
Say something.
Step 17: Closing Day 🔑
Here we go.
You'll sign the necessary closing documents at the title company or through the closing process arranged for your transaction.
There may be quite a few signatures.
Bring whatever identification or other items you've been instructed to provide.
And one extremely important warning:
WIRE FRAUD IS REAL.
Never rely on unexpected or changed wiring instructions sent by email without independently verifying them using a trusted contact method.
If anything involving money or wiring instructions seems unusual:
STOP.
Call the title company using a verified phone number.
Do not send money because an email says the instructions changed.
Step 18: Funding and Getting the Keys 🎉
Signing documents and receiving possession aren't necessarily the exact same moment.
The transaction needs to complete the required closing and funding process, and possession is governed by the contract.
Once everything required has happened and you're entitled to possession:
YOU GET THE KEYS. 🔑🏠
This is the moment we've been working toward.
You went from:
“I think I might want to buy a house.”
to:
“I OWN A HOUSE.”
Now you get to move.
And discover how much stuff you somehow accumulated while renting. 😂
How Long Does the Entire Process Take?
There's no single timeline for every buyer.
Before going under contract, the house-search period could take:
A weekend
or
Several months.
Once under contract, the closing timeline depends on the contract, financing and transaction.
That's why I don't want you waiting until your lease expires next week before calling me.
Start early.
Even if you're not ready to buy today, we can begin building the plan.
The Process Is Complicated. Your Experience Doesn't Have to Be.
There are a lot of people involved in a real estate transaction.
Your Realtor.
Lender.
Title company.
Inspector.
Appraiser.
Insurance provider.
Seller.
Seller's agent.
Possibly others.
You don't need to manage everybody yourself.
That's part of why you hire professionals.
My job isn't just to unlock doors.
It's to help you understand:
What's happening now?
What happens next?
What do you need to do?
What deadlines matter?
And sometimes:
“Andrew—sorry, Jay—tell me again why I'm signing this?” 😂
Ask questions.
That's what we're here for.
Ready to Start Step One?
If you're thinking about buying in San Antonio, don't worry about understanding all 18 steps today.
Start with Step One.
Let's figure out your game plan.
🔑 Text KEY to 726.224.4727
Tell me:
“I'm ready to start the buying process.”
We'll take it from there.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts