What Is a VA Certificate of Eligibility (COE)?
You're ready to explore using your VA home loan benefit.
Then your lender says:
“We need your COE.”
And you're thinking:
“My what?”
😂
Welcome to the military, where apparently we needed one more acronym.
COE stands for:
🇺🇸 CERTIFICATE OF ELIGIBILITY
And if you're planning to use a VA-backed home loan, it's one of the first documents you should understand.
The good news?
It's usually not nearly as complicated as it sounds.
What Does a VA COE Actually Do?
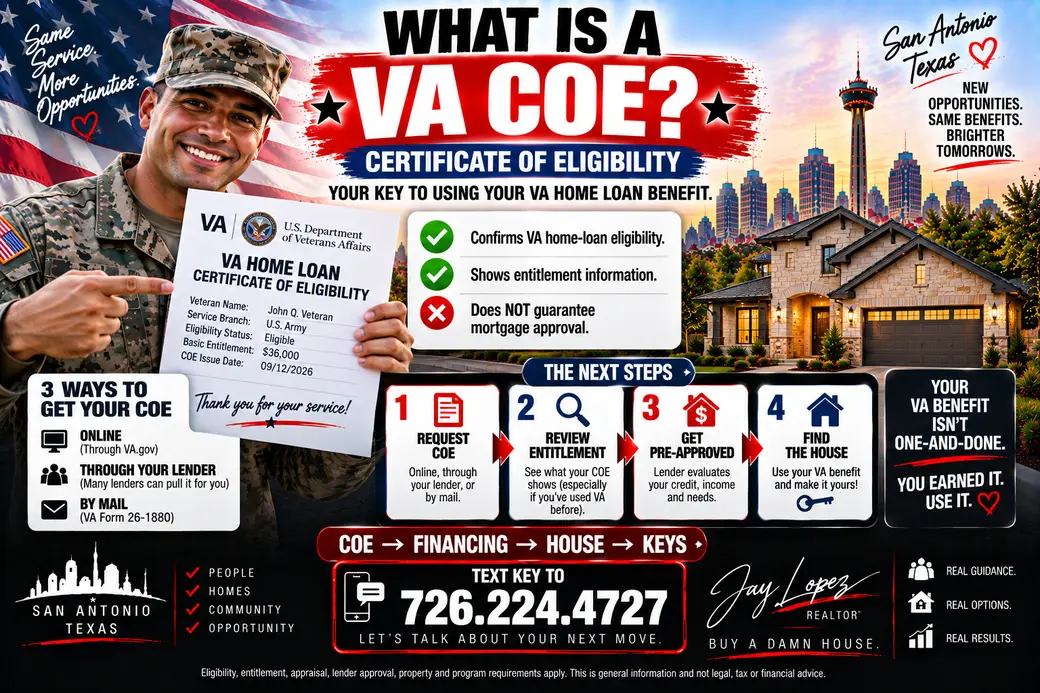
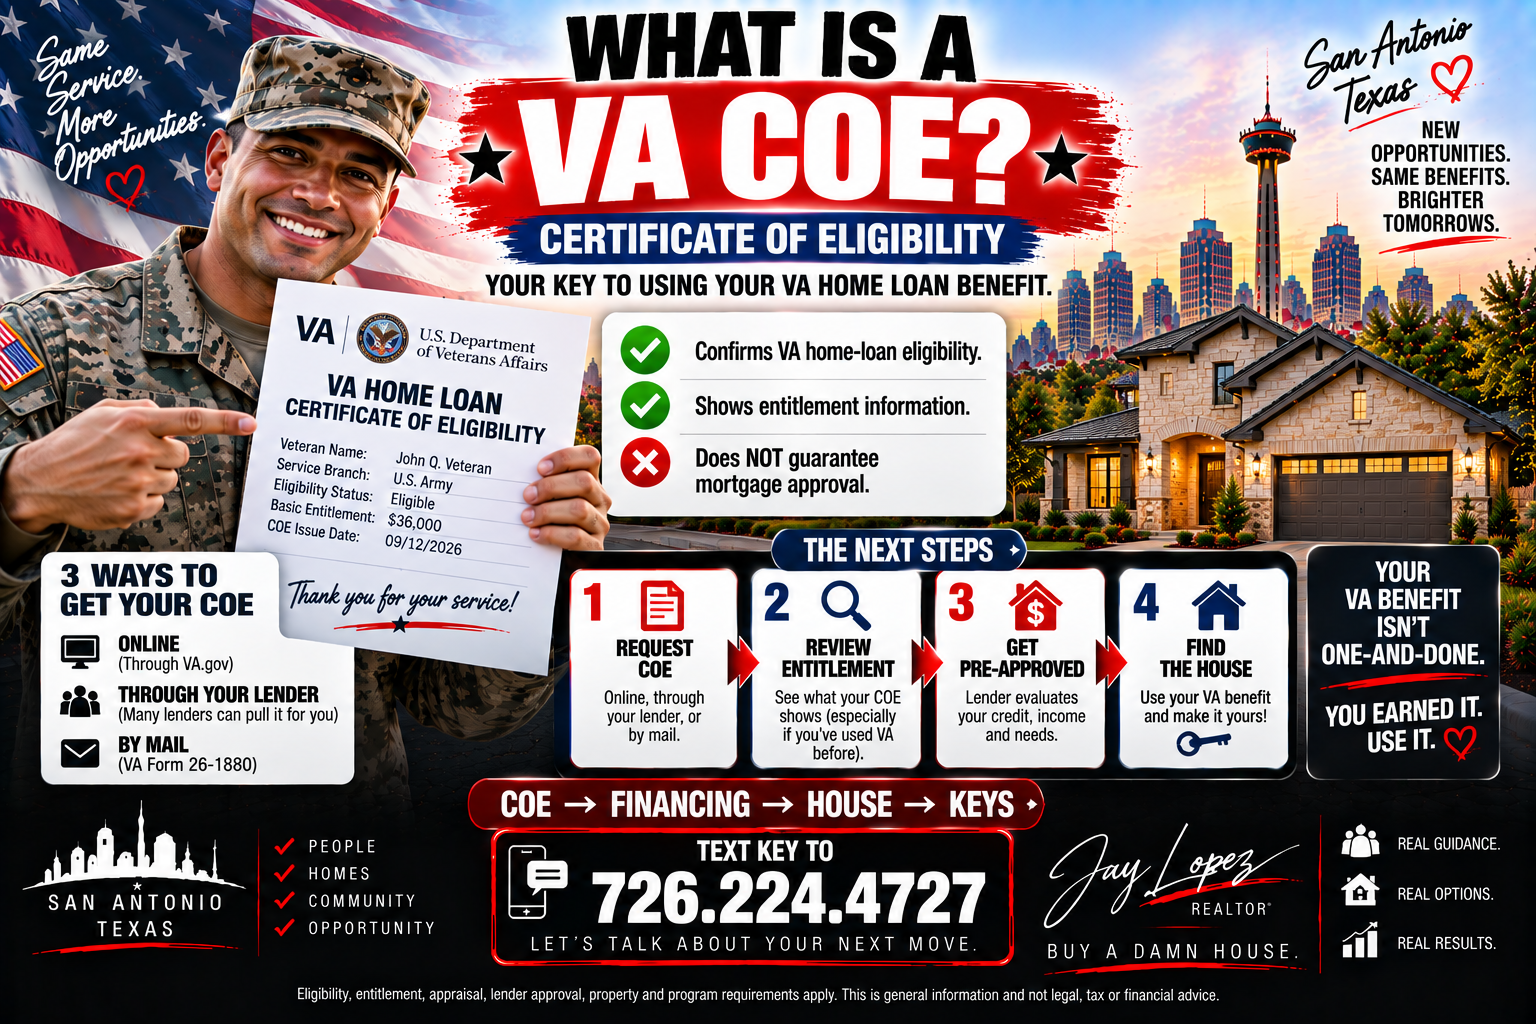
Your Certificate of Eligibility confirms to your lender that you qualify for the VA home loan benefit based on your service history and duty status.
Think of it as VA telling the lender:
“Yes, this borrower has VA home loan eligibility.”
But here's where people get confused.
A COE does not mean:
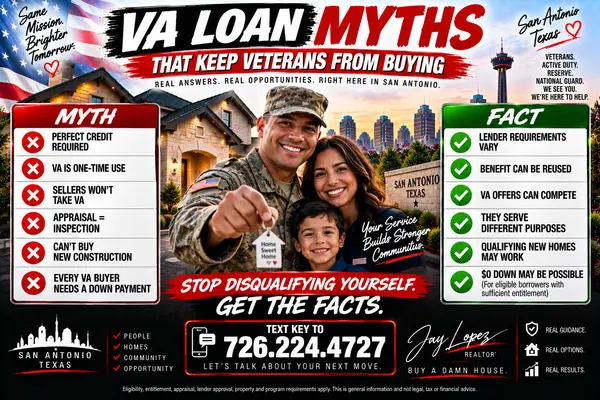
❌ You're approved for a mortgage.
❌ You're approved for a specific loan amount.
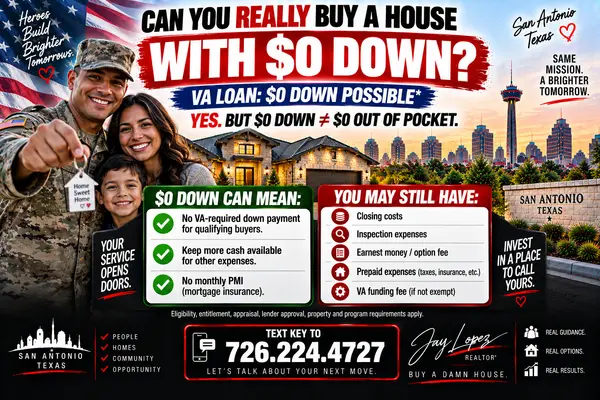
❌ You're guaranteed $0 down.
❌ You're guaranteed a particular interest rate.
❌ You're guaranteed the house you want will qualify.
The lender still has to evaluate your credit, income and other applicable requirements, and VA purchase financing generally requires that you intend to occupy the property as your home.
So remember:
COE = VA BENEFIT ELIGIBILITY
COE ≠ MORTGAGE APPROVAL
That's probably the most important distinction in this article.
Why Does Your Lender Need the COE?
Because your lender needs documentation that you're eligible to use the VA home loan benefit.
VA-backed purchase loans are generally made by private lenders rather than directly by VA.
VA guarantees a portion of the loan against loss, which can help eligible borrowers obtain favorable financing features.
Before the lender can structure your financing appropriately, they need to know:
Are you eligible?
and, especially if you've used VA before:
What's going on with your entitlement?
Your COE helps answer those questions.
What Is VA Entitlement?
This is where the COE becomes especially interesting.
Your COE can show information about your VA home loan entitlement.
Entitlement is related to the amount of guaranty VA provides to your lender.
It is not:
A pile of money waiting for you.
😂
If you see something like $36,000 basic entitlement on a COE, that does not mean:
“I can only borrow $36,000.”
VA specifically explains that the basic-entitlement amount shown on a COE is not your borrowing limit.
Wait...My COE Says $36,000. What Does That Mean?
This is one of those VA things that can look terrifying until somebody explains it.
VA currently describes $36,000 as the basic entitlement associated with loans of $144,000 or less.
For larger loans, additional entitlement rules apply.
If you have full entitlement, VA doesn't impose a loan limit based simply on the guaranty—but your lender still determines how much you can actually borrow based on qualification, and the appraisal must support the transaction.
So please don't look at:
$36,000
and think:
“Well...I guess I'm buying a shed.”
😂
That's not what it means.
What If My COE Shows $0 Basic Entitlement?
Don't panic about that either.
VA explains that a COE showing $0 remaining basic entitlement doesn't necessarily mean you can't get another VA loan.
You may still have additional or “bonus” entitlement available for a loan above $144,000.
And if you've used VA before, your situation may involve:
Previously used entitlement
Remaining entitlement
or
Restoration of entitlement.
That's why you want a VA-knowledgeable lender to interpret the actual COE instead of trying to decode it at 11:47 p.m. on Google.
Who Can Potentially Get a COE?
Eligibility depends on VA's service requirements and your specific circumstances.
Potentially eligible groups include certain:
🇺🇸 Veterans
🇺🇸 Active-duty service members
🇺🇸 National Guard members
🇺🇸 Reserve members
🇺🇸 Qualifying surviving spouses
and some other eligible beneficiaries.
The required service varies based on when and how you served, and VA also recognizes certain qualifying exceptions.
So don't rely on:
“My buddy told me I didn't serve long enough.”
Let VA determine your eligibility.
How Do You Get Your VA Certificate of Eligibility?
VA currently provides three primary ways to request your COE.
OPTION #1 — REQUEST IT ONLINE
You can request the COE directly through VA online.
This is useful if you want to verify your eligibility before getting deep into the mortgage process.
OPTION #2 — HAVE YOUR LENDER REQUEST IT
For many buyers, this may be the easiest route.
VA says lenders may be able to use its online system to obtain the COE for you.
So you may walk into the lender conversation thinking:
“I have to hunt through 14 boxes in my garage for some mysterious VA certificate.”
😂
Not necessarily.
Ask:
“Can you pull my COE?”
In many cases, they can help.
OPTION #3 — REQUEST IT BY MAIL
You can also request a COE by completing:
VA Form 26-1880
Request for a Certificate of Eligibility
and mailing it according to VA's instructions.
VA notes that mailed requests may take longer than online or lender-assisted requests.
For most buyers today, online or lender-assisted retrieval will probably be the more convenient place to start.
What Documents Might You Need?
That depends on your status.
VA lists different documentation requirements for different types of applicants.
For example:
VETERANS
You may need your:
DD214
or applicable discharge/separation documentation.
ACTIVE-DUTY SERVICE MEMBERS
You may need a:
Statement of Service
with required service information and the appropriate signature.
NATIONAL GUARD & RESERVE
Documentation varies based on whether you were activated, whether you're still serving and your service history.
SURVIVING SPOUSES
Additional VA forms and supporting documentation may be required depending on the circumstances.
This is another reason I don't recommend assuming your situation matches somebody else's.
What If VA Can't Issue My COE Immediately?
Don't automatically assume that means:
“DENIED.”
Sometimes VA may need additional documentation or information before making the eligibility determination.
VA reviews the request and provides its decision, and you can check the status of a COE request online.
So if the lender's system doesn't instantly produce a COE:
Don't panic.
Find out what VA needs.
Does Getting a COE Affect Your Credit?
Requesting the COE itself is about verifying your VA home-loan eligibility.
That's separate from the lender's mortgage qualification process.
The lender may need to review your credit and financial information as part of the loan application, but obtaining your COE isn't the same thing as being approved for financing.
Again:
ELIGIBILITY ≠ APPROVAL
Do You Need a COE Before Talking to a Realtor?
No reason to wait.
You can start discussing:
Your goals
Timeline
PCS
Areas around San Antonio
Home type
and your overall strategy.
But before we get serious about writing offers using VA financing, I want your lender involved.
And part of that process is getting your COE sorted out.
Do You Need a COE Before Talking to a Lender?
No.
In fact, your lender may be able to retrieve it for you.
So don't think:
“I can't call a lender because I don't have my COE.”
That's backwards.
Call the lender.
Tell them:
“I want to explore my VA home loan benefit.”
Then let them help you through the process.
What If You've Never Used VA Before?
Your COE helps establish your eligibility and provides entitlement information.
If you're otherwise qualified and have full entitlement, you may potentially use VA's no-down-payment feature subject to applicable requirements, including the relationship between the sales price and appraised value.
But your lender still determines what you qualify to borrow.
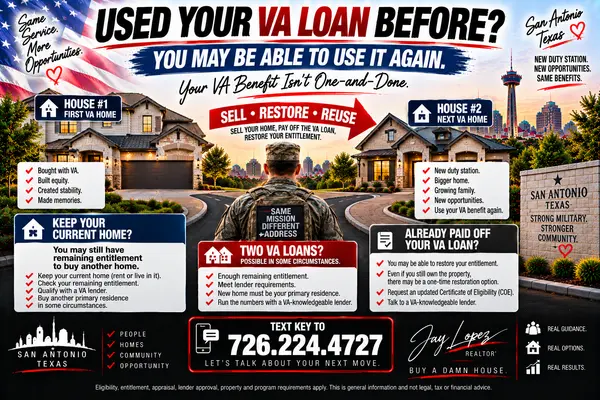
What If You've Used Your VA Benefit Before?
Now the COE becomes even more important.
Maybe you:
Sold the previous home
Paid off the VA loan
Still own the previous home
Still have the VA loan
or
Had someone assume the loan.
Your entitlement situation can be different depending on what happened.
Can You Restore Your VA Entitlement?
Potentially.
VA says previously used entitlement may be restored in qualifying situations, including when the previous VA-financed property has been sold and the loan paid in full.
There are also provisions involving qualifying assumptions with substitution of entitlement and a one-time restoration when the prior VA loan has been paid in full but you still own the property.
You can request entitlement restoration when requesting an updated COE.
What If You Can't Restore All of It?
You may still have:
REMAINING ENTITLEMENT
available.
That can potentially allow some Veterans to obtain another VA-backed loan even though entitlement remains tied to a previous loan.
That's why:
“I already have a VA loan.”
doesn't automatically equal:
“I can't use VA again.”
We covered this in detail in Blog #29, and it's one of the most important VA concepts for PCS buyers.
PCS to San Antonio? Get the COE Early.
If you're heading to:
JBSA-Lackland
JBSA-Randolph
Fort Sam Houston
or another assignment in the San Antonio area, I'd put this near the top of your home-buying checklist:
GET YOUR VA FINANCING REVIEWED EARLY.
Especially if you already own a VA-financed home at another duty station.
We need to know whether you're:
Selling it
Keeping it
and
How your entitlement affects the next purchase.
That information can dramatically change the home-buying strategy.
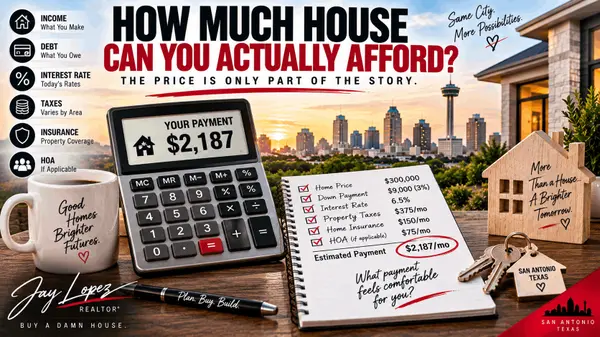
Your COE Doesn't Tell You What House You Can Afford
This deserves its own section.
Your COE is not a home-shopping budget.
Don't receive your COE and think:
“Sweet. How expensive a house can I buy?”
😂
That's the lender conversation.
Your lender evaluates your:
Income
Debts
Credit
Assets
and other applicable underwriting factors.
Then you should take the additional step of asking:
“What payment am I actually comfortable with?”
Maximum approval and comfortable budget aren't necessarily the same thing.
Your COE Also Doesn't Replace Pre-Approval
Think of the process like this:
🇺🇸 COE
Am I eligible for the VA home loan benefit?
⬇
🏦 PRE-APPROVAL / LOAN REVIEW
What financing might I qualify for?
⬇
💰 PERSONAL BUDGET
What payment am I comfortable carrying?
⬇
🏠 HOME SEARCH
What properties fit those numbers?
That order makes a lot more sense than:
HOUSE → FALL IN LOVE → FIGURE OUT MONEY
😂
The Simple VA COE Game Plan
If you're thinking about buying:
STEP 1
Talk to a VA-knowledgeable lender.
STEP 2
Request or retrieve your COE.
STEP 3
Review your entitlement.
STEP 4
Discuss your credit, income and financing.
STEP 5
Determine your comfortable payment.
STEP 6
Build your San Antonio home search.
STEP 7
Go find the house.
🔑
COE Frequently Asked Questions
Does a COE guarantee my VA loan?
No. You still need to satisfy lender and VA requirements.
Can my lender get my COE?
Yes, many lenders can request it electronically through VA.
Can I request it myself?
Yes. VA allows you to request it online or by mail.
What form is used for a mailed COE request?
VA Form 26-1880.
Do Veterans generally need a DD214?
VA lists discharge or separation papers such as the DD214 among the documentation Veterans may need when requesting a COE.
Can I use VA again if I've already used it?
Potentially. Entitlement may be restored in qualifying circumstances, or you may still have remaining entitlement.
Does my COE tell me how much house I can afford?
No. Your lender still has to approve you for the loan amount.
Don't Let Three Letters Intimidate You
That's really the message.
COE
sounds like another complicated military document.
In reality, it's simply a critical piece of confirming your VA home-loan eligibility.
And you don't have to figure it out alone.
Start with:
🇺🇸 COE
Then:
🏦 FINANCING
Then:
🏠 HOUSE
Then:
🔑 KEYS
That's the mission.
Want to Start Your VA Home-Buying Plan?
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
Whether you've used VA before
and
Your approximate buying timeline.
Example:
“KEY — Veteran — never used VA — buying in 6 months.”
Or:
“KEY — Active Duty — already have VA loan — PCS Randolph.”
We'll start there.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house.
Categories
Recent Posts