What Happens to Your VA Loan When You PCS?
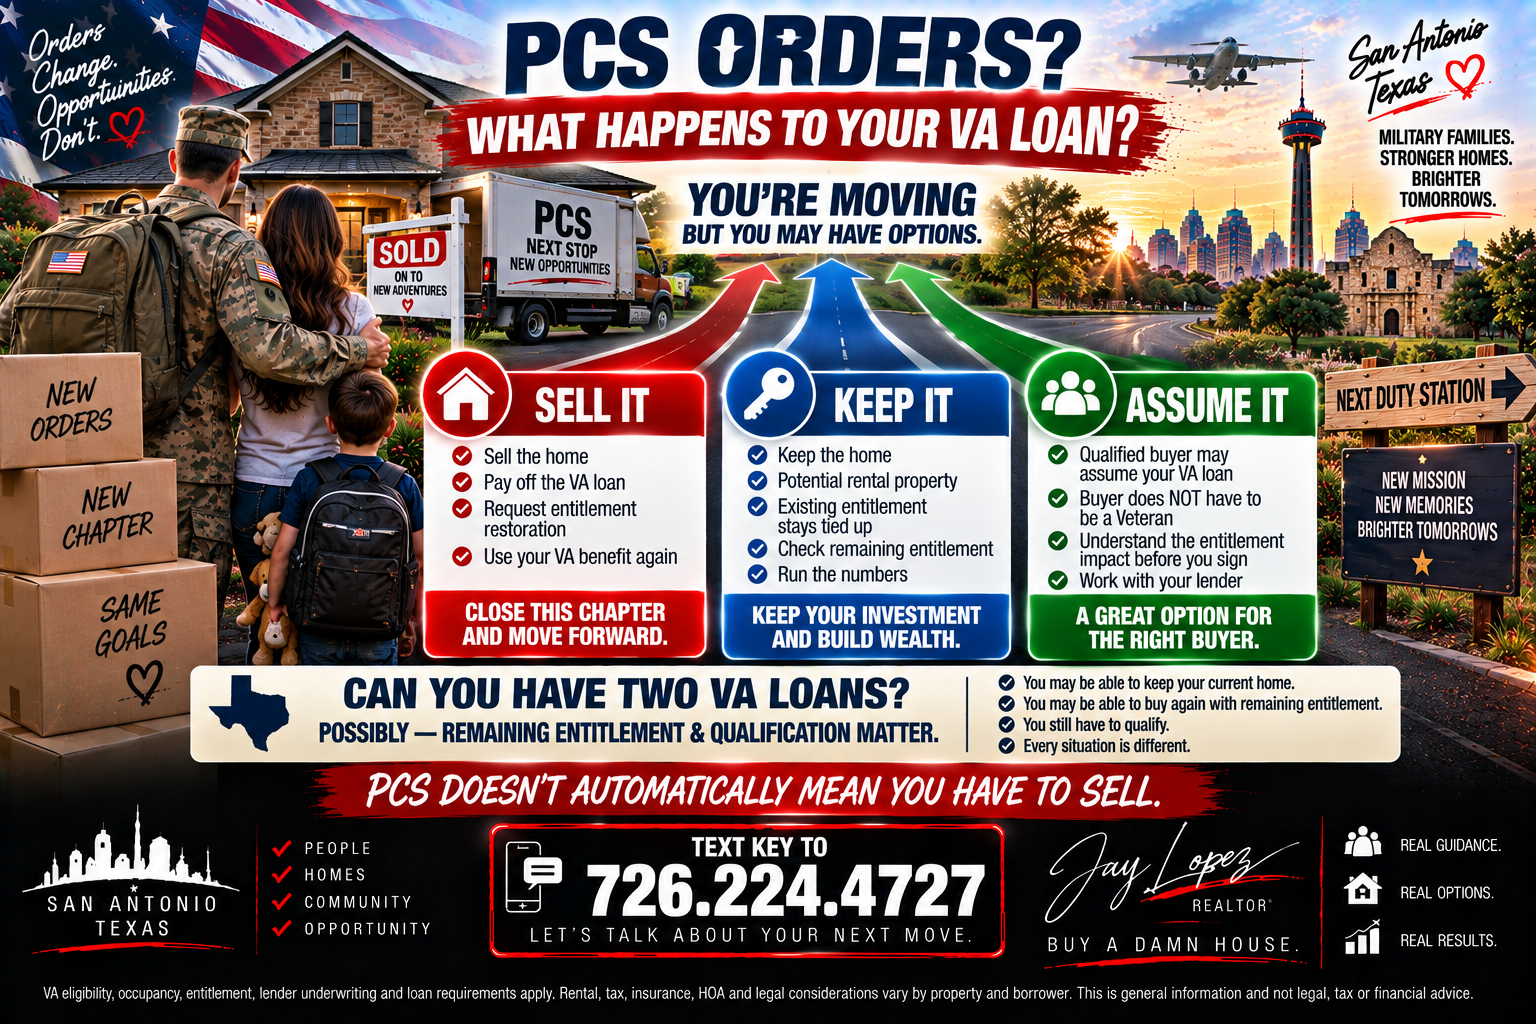
You bought a house with your VA loan.
You've been there a couple of years.
Everything is going great.
And then the military says:
📦 SURPRISE! YOU'RE MOVING.
😂
Welcome to PCS life.
And one of the first questions military homeowners ask is:
“WHAT HAPPENS TO MY VA LOAN WHEN I PCS?”
Here's the important part:
PCS ORDERS DO NOT AUTOMATICALLY MEAN YOU HAVE TO SELL YOUR HOUSE.
Depending on your circumstances, you may potentially:
🏠 Sell the home
🔑 Keep it and rent it
💰 Pay off or refinance the existing VA loan
🇺🇸 Use remaining VA entitlement to purchase another primary residence
or:
🤝 Have a qualified buyer assume your VA loan
VA specifically says the home-loan benefit can be used more than once, and in some cases a Veteran can keep an existing VA-financed property and use remaining entitlement to purchase another home.
Let's break down the options.
First: Does a PCS Violate the VA Occupancy Requirement?
This is where people get nervous.
When you originally used your VA purchase loan, the property had to be intended for your own personal occupancy. VA still requires a new VA-financed purchase to be a home you intend to occupy.
But that does not mean:
“You can never move.”
Military members get reassigned.
People change jobs.
Families grow.
Life happens.
Your original occupancy certification and what happens years later because of a legitimate move are not the same thing as buying a property with no intention of making it your home.
OPTION #1: Sell the House
This is probably the easiest option to understand.
You PCS.
You sell the house.
At closing, your existing VA mortgage is paid off from the sale proceeds.
If the property is sold and the VA-backed loan is paid in full, you may request restoration of the entitlement that was tied to that loan.
That restored entitlement may then be available for another qualifying VA purchase.
So:
BUY → LIVE THERE → PCS → SELL → PAY OFF VA LOAN → RESTORE ENTITLEMENT → USE VA AGAIN
That's one common path.
Does Entitlement Automatically Restore the Second You Sell?
Don't simply assume everything has updated.
VA says you can request a COE with entitlement restoration online, through a lender, or by submitting VA Form 26-1880.
So if you're planning to buy immediately after selling:
GET THE ENTITLEMENT PIECE WORKING EARLY.
Your lender can help verify what your updated COE shows.
OPTION #2: Keep the House
Now things get interesting.
You may decide:
“I don't want to sell.”
Maybe you have a great interest rate.
Maybe you like the property.
Maybe you think you might return to San Antonio.
Maybe selling right now doesn't fit your financial plan.
A PCS by itself does not automatically require you to dispose of the property.
So you may consider keeping it.
Can You Rent Out a Home You Originally Bought With VA?
This is one of the biggest military homeowner questions.
If you legitimately purchased and occupied the property as your home and later PCS, keeping it as a rental can be possible.
But there's a huge distinction between:
✅ Buying your primary residence, living there, and later converting it because circumstances changed
and:
❌ Using a VA purchase loan to acquire a property you never intended to occupy as your home.
VA purchase loans are intended for personal occupancy.
If you're planning a rental conversion, also review your mortgage terms, insurance, HOA rules if applicable, landlord obligations, and lender requirements.
Keeping the House Does NOT Automatically Restore Your Entitlement
This is critical.
Let's say you bought your San Antonio house using VA financing.
You PCS.
You keep the property.
The VA loan is still outstanding.
The entitlement used to guaranty that loan generally remains tied up.
THAT DOESN'T NECESSARILY MEAN YOU CAN'T USE VA AGAIN.
It means we need to determine:
HOW MUCH ENTITLEMENT DO YOU HAVE LEFT?
VA says borrowers who don't qualify for restoration may still have remaining entitlement available for another purchase.
Can You Have Two VA Loans at the Same Time?
YES, IN SOME CIRCUMSTANCES.
This surprises a lot of Veterans.
VA recently reiterated that Veterans may be able to keep their current home and use remaining entitlement to purchase another home they intend to occupy.
That means this scenario can potentially happen:
🏠 House #1 — San Antonio
Existing VA loan.
You PCS.
You keep the property.
Then:
🏠 House #2 — New duty station
You use remaining entitlement toward another qualifying VA purchase.
TWO VA LOANS.
Potentially.
But Two VA Loans Doesn't Automatically Mean $0 Down on the Second House
This is where remaining entitlement matters.
When you don't have full entitlement available, VA uses the applicable county loan limit as part of determining remaining bonus entitlement.
VA explains that lenders may require a down payment if your remaining entitlement isn't sufficient to provide the guaranty needed for the new loan.
So:
“I CAN USE VA AGAIN”
doesn't necessarily equal:
“MY NEXT HOUSE WILL AUTOMATICALLY BE $0 DOWN.”
Your lender needs to calculate it.
Example: PCS and Remaining Entitlement
Let's say:
You used VA entitlement to buy a San Antonio home.
Then you receive PCS orders.
You keep that home and its VA loan.
Now you're buying at your new duty station.
Your lender looks at:
Entitlement already charged
Remaining entitlement
County loan limit where you're buying
New purchase amount
Income
Debts
and other underwriting requirements.
You may have enough remaining entitlement to purchase the second property without a down payment.
Or:
You may need some down payment.
RUN THE ACTUAL NUMBERS.
Don't assume.
You Still Have to Qualify for Both Houses
This is the other half people forget.
Entitlement is only one part of the equation.
Your lender still has to determine whether you qualify financially.
That means the lender evaluates things such as:
Income
Current mortgage
Debts
Credit
Proposed new housing expense
and other underwriting factors.
Your plan to rent the first property may affect the analysis, but don't assume:
“Rent will completely cancel my old mortgage.”
The lender determines what rental income, if any, can be counted and what documentation is required.
OPTION #3: Sell Through a VA Loan Assumption
Now we get to one of the most interesting features of VA loans.
🇺🇸 VA LOANS ARE ASSUMABLE.
An assumption means a qualified buyer takes over the existing VA-guaranteed mortgage obligation, subject to approval.
And here's something important:
THE BUYER DOESN'T NECESSARILY HAVE TO BE A VETERAN TO ASSUME THE LOAN.
VA's current assumption acknowledgment says any qualified purchaser, including a non-Veteran, may potentially assume the remaining balance if the loan is current and the purchaser satisfies applicable underwriting requirements.
That can potentially be attractive if your existing VA mortgage has a favorable rate.
But There Is a HUGE Entitlement Issue With Assumptions
This deserves giant letters.
🚨 ASSUMPTION DOES NOT AUTOMATICALLY RESTORE YOUR VA ENTITLEMENT.
If a non-Veteran—or a Veteran who doesn't substitute entitlement—assumes your VA loan, your entitlement can remain tied to that mortgage until the loan is paid in full.
That can affect your ability to use the VA benefit again.
So before saying:
“Awesome! Someone will assume my 3% loan!”
we need to ask:
“WHAT HAPPENS TO YOUR ENTITLEMENT?”
What Is Substitution of Entitlement?
Suppose another eligible Veteran buys your home and assumes your VA loan.
If that Veteran has sufficient available entitlement and meets VA requirements, they may potentially substitute their entitlement for yours.
If approved:
YOUR ENTITLEMENT CAN BE RESTORED.
VA specifically identifies substitution of entitlement as a way for the original Veteran's entitlement to be restored after an assumption.
That's a very different outcome from an assumption without substitution.
Assumption WITH vs. WITHOUT Substitution
Here's the easy version:
🇺🇸 ASSUMPTION WITH SUBSTITUTION
Qualified eligible Veteran assumes the loan and substitutes sufficient entitlement.
Potential result:
YOUR ENTITLEMENT MAY BE RESTORED.
🏠 ASSUMPTION WITHOUT SUBSTITUTION
Qualified buyer assumes the loan but doesn't substitute entitlement.
Potential result:
YOUR ENTITLEMENT REMAINS TIED TO THAT LOAN.
VA's current assumption guidance explicitly distinguishes these two outcomes.
That difference is enormous for a military homeowner who wants to use VA again.
Selling Normally vs. Assumption
Here's another simple comparison:
| Traditional Sale | VA Loan Assumption |
|---|---|
| Buyer's new financing generally pays off your VA mortgage | Buyer takes over existing VA mortgage |
| Prior loan paid off | Existing loan continues |
| Entitlement may be restored after applicable requirements are met | Entitlement may remain tied up unless qualifying substitution occurs |
| Existing mortgage rate usually doesn't transfer | Existing loan terms can make assumption attractive |
| Typical new-loan process | Assumption requires servicer/VA approval |
Don't choose between them based only on:
“My interest rate is amazing.”
Look at the entire situation.
What About the Equity?
This is another assumption issue people miss.
Imagine:
Your house is worth $400,000.
But:
Your VA loan balance is only $300,000.
There's approximately:
$100,000 DIFFERENCE
before transaction costs and other adjustments.
The buyer doesn't simply assume the $300,000 loan and magically receive the other $100,000.
They need a way to address the difference between the assumption balance and agreed purchase price.
That could involve:
Cash
Additional financing where permitted
or another acceptable structure.
That's why an assumption isn't automatically easy just because the mortgage rate is attractive.
OPTION #4: Refinance the Existing VA Loan
Depending on your goals, another strategy may involve refinancing the existing loan.
But refinancing has:
Costs
Qualification requirements
Interest-rate implications
and possible effects on entitlement.
VA allows a one-time restoration in certain circumstances when a prior VA loan has been paid in full but the Veteran still owns the property.
ONE-TIME means ONE-TIME.
This is not something I'd do casually just to “free up the VA.”
Have the lender explain exactly how the strategy affects your future VA benefit.
Should You Keep Your San Antonio House as a Rental?
That's not automatically a yes or no.
Run the numbers.
Ask:
What is my current mortgage payment?
What could the property realistically rent for?
What will property management cost?
What should I budget for repairs?
What about vacancy?
What happens to my homeowners insurance?
Does my HOA restrict leasing?
How far away will I be?
Do I actually want to be a landlord?
That last one matters.
😂
Because:
“I CAN RENT IT”
and:
“I WANT TO OWN A RENTAL PROPERTY FROM 1,200 MILES AWAY”
are two completely different statements.
Don't Compare Rent Only to Your Mortgage Payment
Suppose:
Mortgage payment = $1,900
and:
Expected rent = $2,200.
You might say:
“BOOM. $300 PROFIT.”
Not so fast.
😂
What about:
Vacancy
Repairs
Maintenance
Property management
Leasing costs
Insurance changes
HOA
Capital expenses
and unexpected problems?
Evaluate the property like an investment.
Not like somebody doing subtraction on a napkin.
What About Your VA Mortgage Rate?
This can be one reason a homeowner considers keeping the property.
If your existing VA mortgage has favorable terms compared with available replacement financing, giving up that loan may affect the decision.
But don't keep a bad rental solely because:
“My rate is low.”
A low interest rate doesn't automatically make a property a good investment.
What Happens to Your Homeowners Insurance?
If you're moving out and converting the property to a rental:
CALL YOUR INSURANCE PROFESSIONAL.
Your insurance needs may change when the home is no longer owner-occupied.
Don't move away and assume your existing homeowners policy automatically covers your new situation correctly.
What About Property Management?
For military homeowners PCS'ing out of San Antonio, this can become a major question.
If you're moving to:
Germany
Korea
Alaska
Virginia
or even just across Texas...
do you want a tenant calling you because:
“THE AC STOPPED WORKING.”
In August.
In San Antonio.
😂
A professional property manager can potentially handle:
Marketing
Tenant screening
Rent collection
Maintenance coordination
and other landlord responsibilities.
But property management costs money.
Build that into your rental analysis.
What If You Think You Might Come Back to San Antonio?
That's another reason some military homeowners consider keeping the property.
Maybe you expect to return to JBSA.
Maybe San Antonio is where you want to retire.
Maybe the house fits your long-term plan.
That's worth considering.
But don't base a major financial decision entirely on:
“Maybe I'll get stationed here again.”
Military orders have a funny way of ignoring our plans.
😂
PCS to San Antonio With an Existing VA Loan Somewhere Else?
Now flip the scenario.
You're PCS'ing to San Antonio.
You already have a VA loan on a home at your previous duty station.
You don't necessarily have to assume:
“I CAN'T USE VA AGAIN UNTIL I SELL.”
VA says remaining entitlement may allow another qualifying VA purchase while an existing VA loan remains outstanding.
The correct move is:
PULL YOUR COE AND RUN THE ENTITLEMENT CALCULATION.
The New San Antonio Home Must Still Be Your Residence
If you're using remaining or restored entitlement to purchase another home with VA financing, the new property still has to satisfy VA's occupancy requirement.
VA states that borrowers using remaining entitlement are still required to make the newly purchased property their residence.
So:
OLD HOUSE = POTENTIAL RENTAL
NEW VA HOUSE = YOUR NEW PRIMARY RESIDENCE
That's the basic idea.
Your PCS + VA Loan Decision Tree
Here's the simple version.
📦 YOU RECEIVE PCS ORDERS
OPTION A — SELL
🏠 Sell property
⬇️
💰 VA mortgage paid off
⬇️
🇺🇸 Request entitlement restoration
⬇️
🔑 Potentially use VA again
OPTION B — KEEP IT
🏠 Keep property
⬇️
🔑 Potentially convert to rental
⬇️
🇺🇸 Existing entitlement remains tied to loan
⬇️
🧮 Calculate remaining entitlement
⬇️
🏡 Potentially use VA again if entitlement and qualification permit
OPTION C — VA ASSUMPTION
🏠 Sell using assumption
⬇️
🤝 Qualified buyer assumes existing VA loan
⬇️
⚠️ Determine whether entitlement remains tied up
⬇️
🇺🇸 Eligible Veteran + qualifying substitution may restore entitlement
PCS Checklist for VA Homeowners
As soon as those orders arrive:
📄 1. PULL YOUR CURRENT VA COE
See what entitlement is charged.
💰 2. FIND YOUR CURRENT LOAN BALANCE
Know exactly what you owe.
🏠 3. ESTIMATE CURRENT PROPERTY VALUE
Understand your potential equity.
📊 4. GET A REALISTIC RENTAL ANALYSIS
Not a Zillow fantasy number.
😂
🧮 5. COMPARE SELLING VS. RENTING
Look at the actual numbers.
🇺🇸 6. HAVE A VA LENDER CALCULATE REMAINING ENTITLEMENT
Especially if you're buying at the next duty station.
🤝 7. CONSIDER ASSUMPTION ONLY AFTER UNDERSTANDING ENTITLEMENT
Don't give away future flexibility accidentally.
🛡️ 8. REVIEW INSURANCE
Especially if converting to a rental.
📝 9. REVIEW HOA AND LANDLORD REQUIREMENTS
Know the rules.
🏦 10. GET PRE-APPROVED FOR THE NEXT PURCHASE
Before assuming the second VA loan will work.
The Biggest PCS Mistake?
WAITING UNTIL THE LAST MINUTE.
Military moves already involve enough chaos.
You don't want to be 30 days from reporting and suddenly trying to figure out:
Should I sell?
Should I rent?
How much entitlement do I have?
Can I buy another house?
Can someone assume this loan?
Do I need a property manager?
😂
Start early.
The more time we have, the more options we can evaluate.
The Bottom Line
Receiving PCS orders doesn't automatically destroy your VA loan strategy.
Depending on your circumstances, you may be able to:
🏠 SELL THE HOME
and restore your entitlement after the applicable requirements are satisfied.
🔑 KEEP THE HOME
and potentially convert it into a rental.
🇺🇸 USE REMAINING ENTITLEMENT
to potentially purchase another primary residence with VA financing.
🤝 SELL THROUGH A VA ASSUMPTION
while carefully considering what happens to your entitlement.
VA itself describes the home-loan benefit as reusable and says some Veterans can keep an existing VA-financed property while using remaining entitlement for another qualifying purchase.
So don't automatically think:
“PCS ORDERS = I HAVE TO SELL.”
Instead ask:
“WHICH OPTION MAKES THE MOST SENSE FOR MY NEXT MOVE?”
PCS'ing to or From San Antonio?
Let's build the plan before the moving truck shows up.
🔑 Text KEY to 726.224.4727
Send me:
Current duty station
New duty station
Whether you currently own a home
and:
Approximate PCS date
Example:
“KEY — PCS from San Antonio to Virginia — own a VA home here — moving in February.”
We'll start looking at the real estate options, and your VA lender can verify your entitlement and financing.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house. 🇺🇸🔑
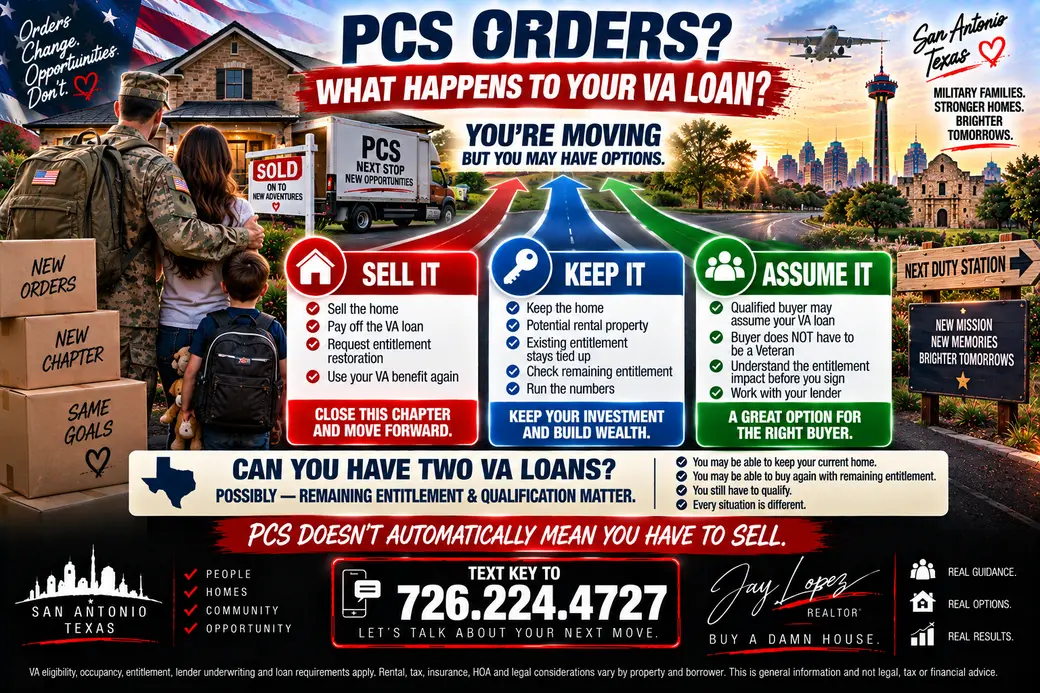
Featured Image Concept
This one should be visually different: a PCS decision-map infographic.
Background: military family beside packed moving boxes and a moving truck in front of their San Antonio home. Subtle American flag, Texas/San Antonio imagery, and a road leading toward a new duty station.
MAIN HEADLINE:
🇺🇸 PCS ORDERS?
WHAT HAPPENS TO YOUR VA LOAN?
Center:
📦 YOU'RE MOVING
BUT YOU MAY HAVE OPTIONS
Three large paths branching outward:
🏠 SELL IT
Pay off VA loan → Request entitlement restoration
🔑 KEEP IT
Potential rental → Existing entitlement stays tied up → Check remaining entitlement
🤝 ASSUME IT
Qualified buyer may take over the VA loan → Understand entitlement before you sign
Large callout:
🇺🇸 CAN YOU HAVE TWO VA LOANS?
POSSIBLY — REMAINING ENTITLEMENT & QUALIFICATION MATTER
Bottom banner:
PCS DOESN'T AUTOMATICALLY MEAN YOU HAVE TO SELL.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts