Can You Use a VA Loan to Buy New Construction?
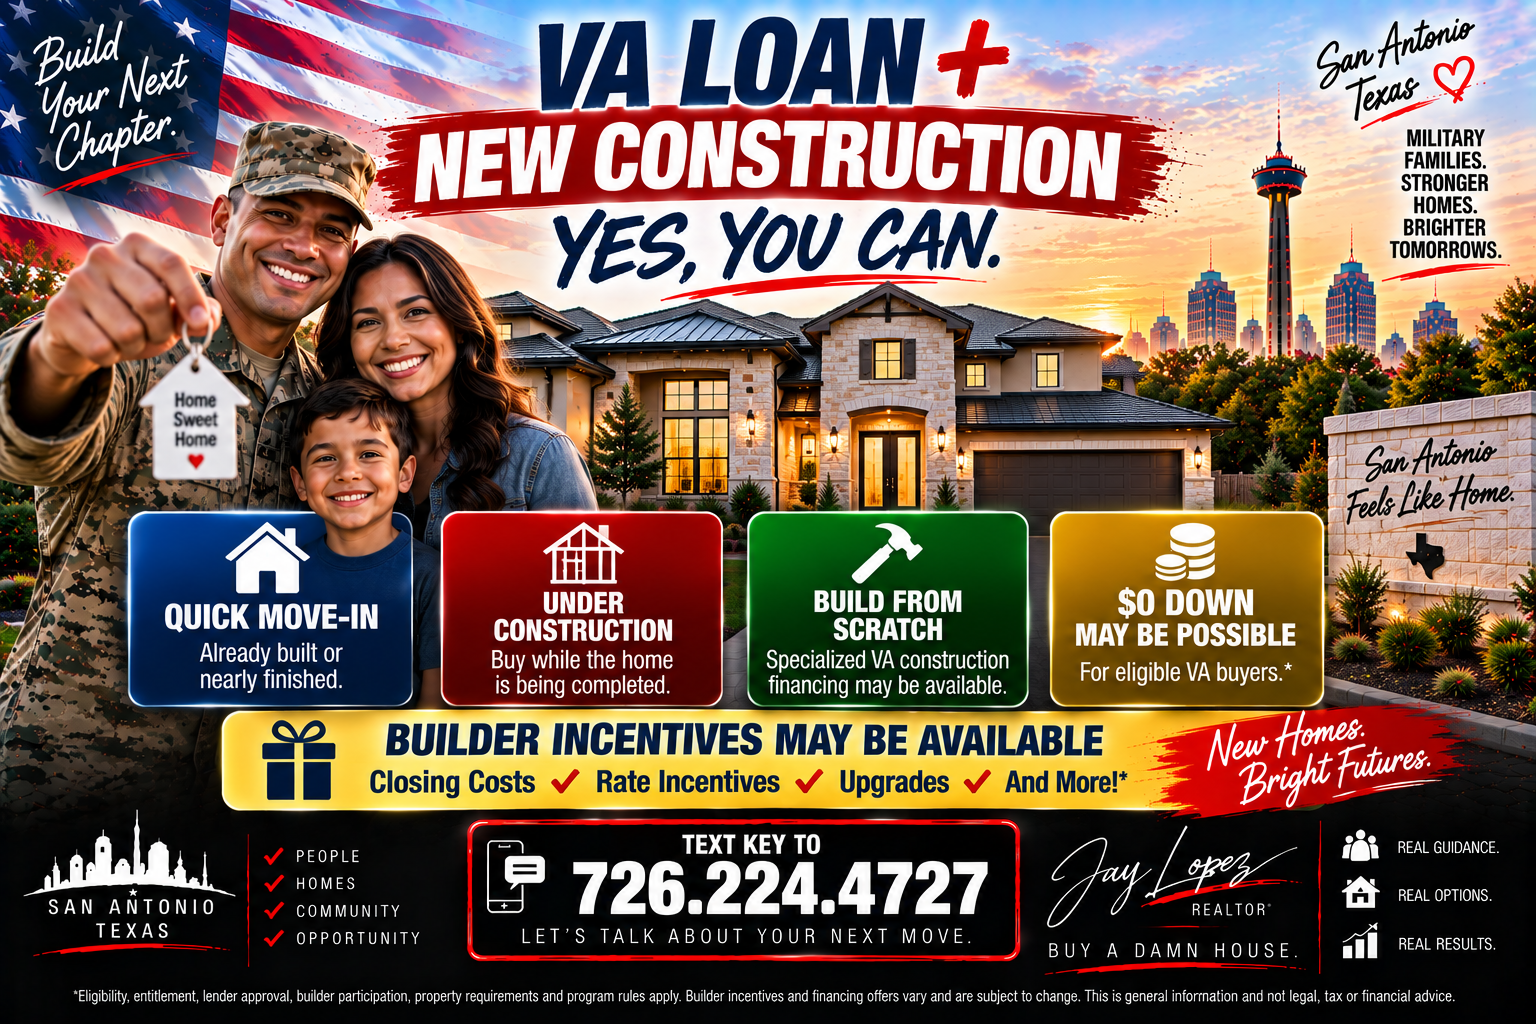
Here's a question I hear from Veterans and active-duty buyers all the time:
“CAN I USE MY VA LOAN TO BUY A BRAND-NEW HOUSE?”
The short answer?
YES.
VA home loan benefits can be used for eligible new-construction purchases.
But—and this is important—
NOT EVERY NEW-CONSTRUCTION DEAL WORKS THE SAME WAY.
There's a major difference between:
🏠 Buying a builder's completed inventory home
🏗️ Contracting for a home that's still being built
and
🔨 Using financing to buy land and construct a home
Those can involve very different financing processes.
So before walking into a model home and falling in love with the kitchen...
😂
Let's talk about how this actually works.
First: Yes, VA Loans Can Be Used for New Construction
VA home loan benefits aren't limited to older resale houses.
Eligible borrowers may use VA financing to purchase or construct a home that will be used as their primary residence, subject to VA, lender, property and occupancy requirements.
That means your VA benefit can potentially put a:
BRAND-NEW HOUSE
on the table.
And in a market like San Antonio—where new communities continue to be an important part of the housing inventory—that can give military buyers another category of homes to consider.
But “New Construction” Can Mean Several Different Things
This is where buyers get confused.
When somebody tells me:
“I want new construction.”
My next question is:
“WHAT KIND?”
Because there are several possibilities.
Option #1: Completed Inventory Home
This is often the simplest type for buyers to understand.
A builder has already constructed the house.
It's finished—or nearly finished—and available for purchase.
You may hear terms such as:
Inventory home
Spec home
or:
Quick move-in home
Depending on the builder and lender, an eligible buyer may potentially finance one of these homes using a standard VA purchase loan.
From the buyer's perspective, this can feel much closer to purchasing a resale home.
Option #2: A Home Currently Under Construction
Maybe the builder started the home two months ago.
The slab is down.
Framing is going up.
You pick some available finishes.
And the house is expected to be completed later.
Depending on the builder, lender and property, VA financing may potentially be used for the completed purchase.
But:
THE DETAILS MATTER.
Your lender needs to understand exactly what the builder is offering and how the transaction will be structured.
Option #3: Build From the Ground Up
Now we're talking about something different.
Maybe you want to:
Buy land
Choose your builder
Choose a floor plan
and
Build your home from scratch.
VA does allow eligible borrowers to use VA-backed financing to build a home, but VA construction lending is more specialized than a normal VA purchase mortgage.
One of the biggest practical challenges?
FINDING A LENDER THAT ACTUALLY OFFERS THE PRODUCT.
Just because a lender originates VA loans does not necessarily mean it offers VA construction financing.
That's an important distinction.
VA Loan vs. VA Construction Loan
Let's make this simple.
🏠 STANDARD VA PURCHASE
You're buying a completed or qualifying home from a seller or builder.
🏗️ VA CONSTRUCTION FINANCING
You're financing the construction of the home itself.
Different process.
Potentially different lender.
Different documentation.
Different timeline.
Different risk.
So when calling lenders, don't simply ask:
“Do you do VA?”
Ask:
“DO YOU OFFER VA CONSTRUCTION-TO-PERMANENT FINANCING?”
That's a much better question if you're trying to build from scratch.
Can You Buy New Construction With $0 Down?
POTENTIALLY, YES.
One of the major benefits of VA purchase financing is that eligible borrowers with sufficient entitlement may be able to purchase without a VA-required down payment, subject to lender approval and other program requirements.
That can also apply in qualifying new-construction transactions.
But remember what we've talked about throughout this VA series:
$0 DOWN DOES NOT AUTOMATICALLY MEAN $0 OUT OF POCKET.
You can still have expenses associated with the transaction.
What Could You Still Pay?
Depending on the transaction, costs may include things such as:
Earnest money
Option or other contract-related deposits
Inspection expenses
Appraisal-related charges
Prepaid items
Insurance
Allowable closing costs
and potentially other builder-specific deposits or charges.
How those amounts are treated depends on the contract and financing.
So don't walk into the builder saying:
“Jay said I don't need any money.”
😂
Jay did NOT say that.
Builder Deposits Can Be Different
This is especially important.
Builders often use their own purchase agreements, and those contracts may be substantially different from a typical Texas resale transaction.
A builder may require:
An earnest-money deposit
Upgrade deposits
Design-center deposits
or other amounts depending on the home and contract.
Those deposits may also have different refundability provisions.
READ THE BUILDER CONTRACT.
And understand it before putting money down.
Do I Need a Realtor When Buying From a Builder?
You can purchase directly from a builder.
But here's something buyers need to understand:
THE BUILDER'S SALES REPRESENTATIVE REPRESENTS THE BUILDER'S INTERESTS.
They're there to sell the builder's homes.
They're not automatically your personal real estate representative.
That's why having your own Realtor involved can be valuable.
And Bring Your Realtor the FIRST Time
This is important.
Builder registration and representation policies can vary.
Some builders require your agent to accompany you or register you during your initial visit.
So before you casually walk into:
“Just look around...”
call your Realtor.
😂
Because that innocent Saturday model-home tour can potentially affect how representation is handled.
Does Using a Realtor Automatically Cost More?
Don't assume that because you're represented, the builder simply adds your agent's compensation onto the home's price.
Compensation arrangements are transaction-specific and should be clearly understood.
The important question is:
WHO IS HELPING YOU EVALUATE THE DEAL?
The builder has professionals representing its interests.
You should understand who represents yours.
What Can Your Realtor Help With?
When buying new construction, I want to help you evaluate more than:
“Do you like the countertops?”
😂
We're looking at things such as:
Price
Available inventory
Builder incentives
Financing options
Closing-cost offers
Rate incentives
Upgrade packages
Lot premiums
Contract terms
Estimated taxes
HOA costs
Completion timeline
and the overall deal.
Because sometimes:
THE CHEAPEST HOUSE ISN'T THE BEST DEAL.
And sometimes:
THE BIGGEST INCENTIVE ISN'T THE BEST DEAL EITHER.
Builder Incentives Can Be Huge—but Read the Fine Print
Builders frequently use incentives to move inventory.
Depending on the builder and current promotion, you might see:
Closing-cost assistance
Interest-rate incentives
Temporary or permanent rate buydowns
Design upgrades
Appliance packages
Price reductions
or combinations of these.
Those incentives can be especially interesting for VA buyers.
But:
VERIFY EVERYTHING.
A headline saying:
“LOW RATE!”
doesn't necessarily mean every buyer qualifies.
The offer may require:
Specific inventory
Specific closing date
Preferred lender
Approved credit
Certain loan programs
or other conditions.
Should You Use the Builder's Preferred Lender?
Maybe.
Maybe not.
This is where we compare.
The builder's lender may offer significant incentives.
But you still want to evaluate the:
Interest rate
APR
Loan fees
Credits
VA funding fee treatment
Monthly payment
Cash needed at closing
and overall financing structure.
Don't choose the lender because:
“THEY'RE GIVING ME $10,000!”
until you know what the entire loan looks like.
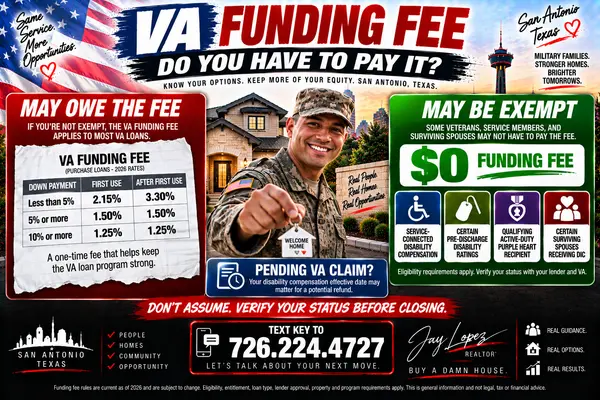
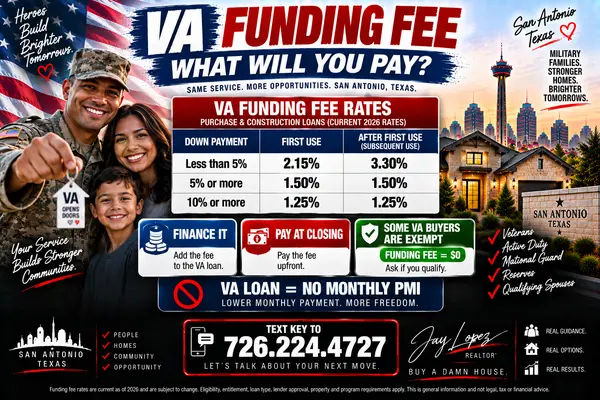
VA Funding Fee Still Matters
Remember Blogs #31 and #32?
Buying new construction doesn't automatically eliminate the VA funding fee.
A non-exempt VA borrower may still owe the applicable funding fee.
An eligible exempt borrower may not.
And depending on the financing structure, the fee may potentially be financed into the VA loan.
So before comparing builder offers:
KNOW YOUR FUNDING-FEE STATUS.
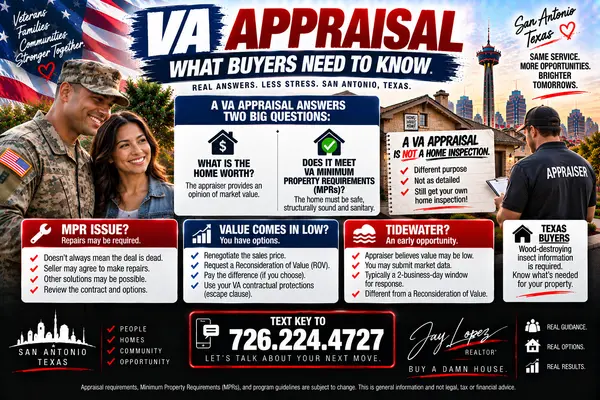
Does the New House Still Need a VA Appraisal?
YES, FOR VA FINANCING.
Being brand-new doesn't eliminate the appraisal requirement.
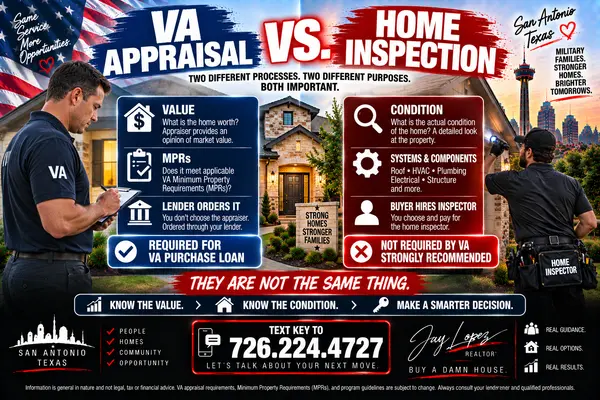
The VA appraisal still addresses:
VALUE
and applicable:
MINIMUM PROPERTY REQUIREMENTS
The exact requirements and documentation can depend on the type and stage of construction.
“But It's Brand New. Why Would I Need an Inspection?”
Here we go again.
😂
NEW DOESN'T MEAN PERFECT.
A house can be brand new and still have issues.
Construction involves:
Multiple subcontractors
Electrical work
Plumbing
HVAC
Roofing
Framing
Insulation
Drywall
Appliances
Fixtures
and a lot more.
Things can get missed.
Should You Inspect New Construction?
VA's appraisal is still not a substitute for a home inspection.
Depending on the stage of construction and your contract, buyers may consider inspections appropriate to the property and construction process.
For a completed inventory home, that might include a standard inspection before closing.
For a home being built from the ground up, some buyers may also discuss staged inspections with appropriate professionals.
The exact rights and timing depend on the builder contract.
What About the Builder's Final Walk-Through?
That's important.
But again:
FINAL WALK-THROUGH ≠ PROFESSIONAL HOME INSPECTION.
The builder may conduct an orientation or final walk-through where you identify visible items.
You might notice:
Paint touch-ups
Cabinet issues
Damaged trim
Doors needing adjustment
Cosmetic problems
and other items.
That's valuable.
But it serves a different purpose from an independent inspection.
What About Builder Warranties?
Many builders provide warranties of some type.
But:
READ THE ACTUAL WARRANTY.
Don't rely on:
“Don't worry, everything is covered.”
What's covered?
For how long?
Who handles the claim?
What's excluded?
Are different components covered for different periods?
Those are the questions that matter.
A warranty is useful.
But it isn't a reason to ignore problems before closing.
What About Property Taxes on New Construction?
This one can surprise buyers.
🚨 PAY ATTENTION TO TAX ESTIMATES.
When a home was previously vacant land or only partially completed, historical tax information may not reflect what taxes could look like once the completed home is fully assessed.
That means:
Looking at last year's taxes can give you the wrong impression.
When you're calculating affordability, ask the lender and other appropriate professionals what assumptions they're using for the completed property's taxes.
DON'T BUDGET USING A VACANT-LOT TAX BILL.
Military Buyers: Don't Build Your Budget Around BAH Alone
BAH can absolutely be part of your financial planning.
But:
BAH IS NOT A HOME-PRICE CALCULATOR.
Your housing allowance doesn't tell you:
“This is how expensive a house you should buy.”
Your real monthly housing cost can include:
Principal
Interest
Property taxes
Homeowners insurance
HOA
Utilities
Maintenance
and other expenses.
Buy the payment that works for your household.
Not the maximum somebody says you can qualify for.
New Construction Can Be Great for a PCS Timeline
For military buyers moving to San Antonio, completed or near-complete new construction can sometimes be especially useful.
Why?
You may be able to identify:
QUICK MOVE-IN HOMES
that are already built or approaching completion.
That can reduce some of the uncertainty associated with waiting months for a home to be built.
But don't assume a builder's estimated completion date is guaranteed.
Construction schedules can change.
Buying New Construction Before You Arrive in San Antonio
This is another situation where military buyers have options.
Depending on the builder, property and transaction, we may be able to help you evaluate homes remotely through:
Video walkthroughs
Photos
Virtual meetings
Builder information
Community information
and coordination with your lender and other professionals.
But I still want you making an informed decision.
Buying remotely doesn't mean:
BUY BLIND.
What About Communities Near JBSA?
San Antonio-area new construction can potentially be considered by buyers stationed at:
Lackland
Randolph
Fort Sam Houston
and other JBSA locations.
But I don't want to tell you:
“This is where military families should live.”
That's not how we choose your location.
Instead, let's compare objective factors such as:
Commute
Home prices
Available inventory
Property taxes
HOA
Amenities
Lot sizes
Builder options
and whatever matters to you.
Then you decide.
Can You Negotiate With a Builder?
SOMETIMES.
But builder negotiations can look different from resale negotiations.
A builder may be less willing to reduce the advertised sales price but more flexible with:
Closing-cost credits
Financing incentives
Upgrades
Appliances
Lot premiums
or other terms.
Or maybe the builder is already offering its strongest promotion.
It depends on:
Inventory
Community
Construction stage
Builder
and current market conditions.
Why Would a Builder Prefer Incentives Over Cutting the Price?
Because builders care about recorded sales prices in their communities.
If they heavily discount one home, that sale can potentially affect buyer expectations and future comparable-sale analysis.
So a builder might prefer offering value through incentives instead.
That doesn't mean the incentive is automatically better for you.
We still compare the numbers.
Example: Two Builder Offers
Let's say Builder A offers:
$10,000 price reduction
Builder B offers:
$10,000 toward qualifying closing costs or financing incentives
Which is better?
YOU DON'T KNOW YET.
😂
We need to compare:
Monthly payment
Interest rate
Cash needed at closing
Total financing
Home price
and how long you expect to own the property.
That's how you compare builder deals.
Can a Builder Pay VA Closing Costs?
Builders may offer credits toward allowable buyer costs, subject to VA, lender, contract and concession requirements.
That's one reason new construction can be attractive to VA buyers.
But again:
CURRENT PROMOTION + CURRENT RULES + YOUR LOAN = THE REAL ANSWER.
Don't rely on an advertisement alone.
Can the Builder Pay the VA Funding Fee?
Potentially, seller concessions can include payment of a buyer's VA funding fee when structured within applicable VA rules.
But:
THE BUILDER DOESN'T HAVE TO.
And an exempt VA borrower wouldn't owe the funding fee in the first place.
That's why we determine your specific situation before deciding which incentive has the most value.
Completed Inventory vs. Building From Scratch
Here's the easiest comparison:
| Completed / Quick Move-In | Build From Scratch |
|---|---|
| Home already built or nearly finished | Longer process |
| Easier to see exactly what you're buying | More customization may be possible |
| Closing may be sooner | Completion date may change |
| Standard VA purchase financing may be more straightforward | Specialized construction financing may be needed |
| Builder may be motivated on standing inventory | Deposits and construction terms may be different |
| Limited customization | More choices depending on builder |
Neither is automatically better.
It's about your:
TIMELINE + BUDGET + PRIORITIES.
Questions VA Buyers Should Ask a Builder
Before signing anything, ask:
1. Do you currently accept VA financing on this property?
2. Is this home complete, under construction or to-be-built?
3. What deposits are required?
4. Which deposits are refundable—and under what circumstances?
5. What incentives are currently available?
6. Do incentives require your preferred lender?
7. What's the estimated completion date?
8. What HOA fees apply?
9. What should I expect for property taxes once fully assessed?
10. What warranty is included?
11. What inspection rights does the contract provide?
12. What happens if the VA appraisal identifies an issue?
13. What happens if construction is delayed?
That's a much better conversation than:
“Do I get the free refrigerator?”
😂
Although...
Ask about that too.
Your San Antonio VA New-Construction Game Plan
Here's how I'd approach it:
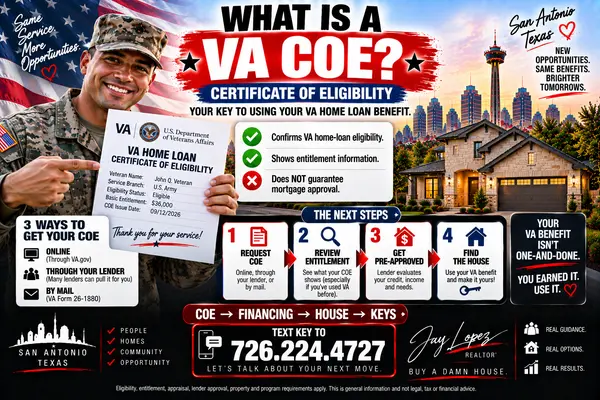
🇺🇸 STEP 1 — VERIFY VA ELIGIBILITY
Get your COE.
🏦 STEP 2 — GET PRE-APPROVED
Know your comfortable payment range.
💰 STEP 3 — VERIFY FUNDING-FEE STATUS
Exempt or non-exempt?
🏠 STEP 4 — DECIDE WHAT TYPE OF NEW CONSTRUCTION
Quick move-in?
Under construction?
Build from scratch?
📍 STEP 5 — IDENTIFY AREAS THAT FIT YOUR NEEDS
Commute, price, taxes, inventory and lifestyle.
👷 STEP 6 — COMPARE BUILDERS
Don't automatically stop at the first model home.
💵 STEP 7 — COMPARE INCENTIVES
Look at the whole deal.
📑 STEP 8 — UNDERSTAND THE BUILDER CONTRACT
Before handing over money.
🔍 STEP 9 — PLAN YOUR INSPECTIONS
New does not mean flawless.
🇺🇸 STEP 10 — COMPLETE THE VA APPRAISAL PROCESS
Value + applicable VA requirements.
🚶 STEP 11 — FINAL WALK-THROUGH
Make sure agreed items are addressed.
🔑 STEP 12 — CLOSE AND GET THE KEYS
Now you get to move into a house nobody else has lived in.
That's pretty cool.
The Bottom Line
🇺🇸 YES—VA BUYERS CAN BUY NEW CONSTRUCTION.
Depending on your situation, that might mean:
🏠 A completed inventory home
🚚 A quick move-in home
🏗️ A home currently under construction
or potentially:
🔨 Building from the ground up with appropriate VA construction financing.
Eligible borrowers may potentially use the VA benefit with no VA-required down payment, subject to entitlement, lender approval and other requirements.
Builder incentives may also help with allowable transaction costs.
But:
NEW CONSTRUCTION HAS ITS OWN RULES, CONTRACTS AND STRATEGIES.
Don't just walk into the model home and pick the prettiest kitchen.
Understand the deal.
Want to See VA-Eligible New Homes Around San Antonio?
This is where we can make the CTA especially useful.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
Approximate price range
JBSA location or area you're considering
and
When you need to move.
Example:
“KEY — Active Duty — $350K — Randolph — PCS in February.”
I'll help you start identifying new-construction options and current builder opportunities that fit your criteria.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information and new construction.
Buy a damn house. 🇺🇸🔑
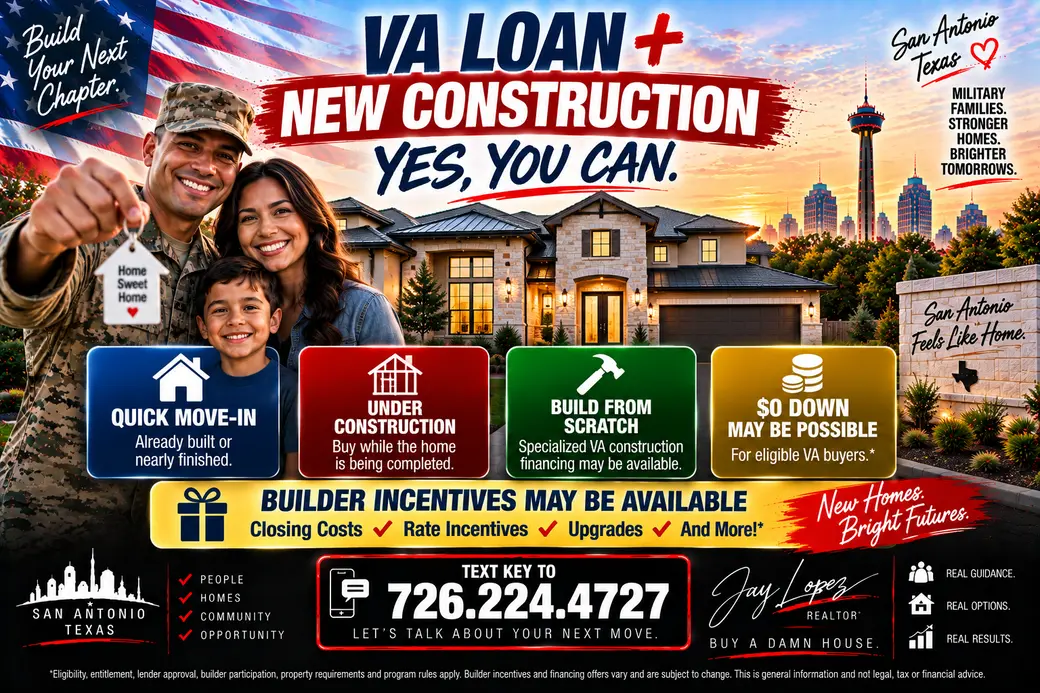
Featured Image Concept
This one should feel like a brand-new-home advertisement instead of another VA information chart.
Large beautiful new San Antonio home at sunset.
Military buyer/family standing in front holding keys.
American flag subtly incorporated into the sky.
Tower of the Americas in the distant skyline.
MAIN HEADLINE:
🇺🇸 VA LOAN + NEW CONSTRUCTION
YES, YOU CAN.
Four bold cards:
🏠 QUICK MOVE-IN
Already built or nearly finished
🏗️ UNDER CONSTRUCTION
Buy while the home is being completed
🔨 BUILD FROM SCRATCH
Specialized VA construction financing may be available
💰 $0 DOWN MAY BE POSSIBLE
For eligible VA buyers*
Then a bright builder-style banner:
BUILDER INCENTIVES MAY BE AVAILABLE
Closing Costs • Rate Incentives • Upgrades*
Bottom message:
NEW HOUSE. VA BENEFIT. SMART GAME PLAN.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts