What Credit Score Do You Need to Buy a House in Texas?
“I want to buy a house, but my credit isn't good enough.”
I hear that all the time.
My first question is usually:
Who told you that?
Was it a mortgage lender who actually reviewed your situation?
Or was it an app?
A friend?
Something you read online?
Your cousin who bought a house in 2017? 😂
Credit absolutely matters when you're buying a home. But there isn't one universal credit score that automatically determines whether everyone can or cannot buy a house.
Different loan programs have different requirements, and individual lenders may also have their own underwriting standards.
So before you disqualify yourself from buying a home in San Antonio—or anywhere else in Texas—let's talk about what your credit score actually means.
1. There Isn't One Magic Credit Score for Buying a House
People love simple answers.
“What credit score do I need?”
Unfortunately, mortgage financing doesn't work quite that simply.
The credit profile needed can depend on factors such as:
- Loan program
- Individual lender requirements
- Down payment
- Debt-to-income ratio
- Income
- Credit history
- Property
- Overall financial profile
That's why two people with the same credit score could potentially have very different financing situations.
Your score matters.
But it's not the only number that matters.
2. What About Conventional Loans?
Conventional mortgages are not insured or guaranteed by a government agency such as FHA or VA.
The credit requirements can depend on the specific conventional loan program, lender and overall borrower profile.
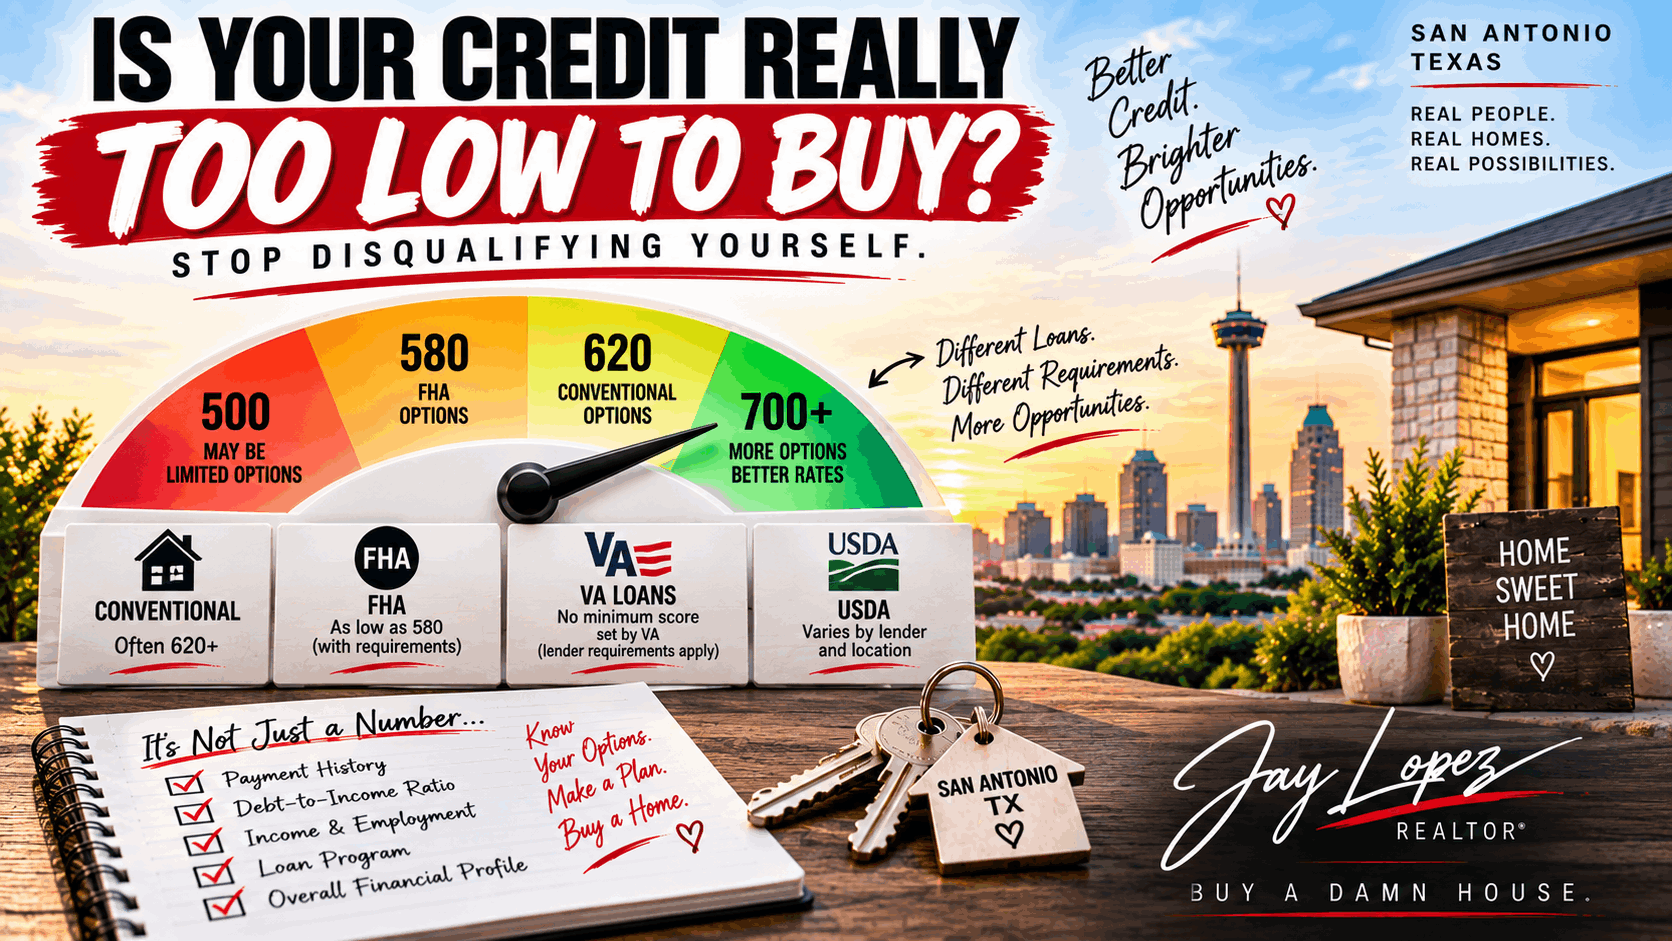
You'll often see 620 mentioned online as a common benchmark associated with certain conventional mortgage programs.
But don't interpret that as:
619 = impossible
620 = automatically approved
Mortgage qualification isn't a light switch.
Even when a borrower meets a particular program threshold, credit can affect other aspects of financing, including potential pricing and mortgage insurance.
The lender needs to review the entire application.
3. What Credit Score Do You Need for an FHA Loan?
FHA-insured loans can be an option for buyers with a variety of credit profiles.
HUD's FHA guidelines allow maximum financing for borrowers with a 580 or higher minimum decision credit score, while borrowers with scores between 500 and 579 are generally limited to 90% loan-to-value under FHA guidelines.
But there's an important distinction:
FHA guidelines and a particular lender's requirements aren't necessarily identical.
A lender may impose additional credit requirements—sometimes called lender overlays.
So seeing an FHA number online does not mean every lender will approve every borrower at that score.
That's why the right move is to speak with a lender who can evaluate your actual circumstances.
4. What Credit Score Do You Need for a VA Loan? 🇺🇸
This is particularly important for San Antonio's military community.
Here's something many Veterans don't realize:
VA itself does not establish a universal minimum credit score for its home loan guaranty.
Individual VA lenders evaluate creditworthiness and may establish their own credit standards.
That means you shouldn't automatically assume:
“My score is below ___, so I can't use my VA benefit.”
Talk to a qualified VA lender.
Let them review your situation.
If you don't qualify today, find out why and what needs to change.
That's far more useful than rejecting yourself based on a number you found online.
5. What About USDA Loans?
USDA-backed financing may provide another option for eligible buyers purchasing qualifying properties.
USDA qualification can involve:
- Creditworthiness
- Household income requirements
- Property eligibility
- Occupancy requirements
- Other program guidelines
Lender underwriting requirements also matter.
If you're considering areas outside central San Antonio, it may be worth asking your lender whether USDA financing and the property you're considering could qualify.
6. Your Credit Score Isn't Your Entire Credit Profile
This is important.
Your lender isn't necessarily looking at one number and ignoring everything else.
Your overall credit profile may include things such as:
Payment history
Amounts owed
Credit utilization
Age of accounts
Recent credit inquiries
Collections or derogatory accounts
Public-record or credit events when applicable
and other factors used in underwriting.
That's why blindly trying to raise your score without understanding what's actually on your credit report isn't always the best strategy.
7. Credit Karma Isn't Your Mortgage Lender
Consumer credit apps can be useful tools.
They can help you monitor your credit and watch for changes.
But the score you see in a consumer app isn't necessarily the exact credit score or scoring model a mortgage lender will use.
So don't panic if:
Your app says one number and your lender says another.
And definitely don't decide whether you're eligible for a mortgage based solely on the number displayed on your phone.
Use credit-monitoring apps for awareness.
Use a qualified mortgage professional for mortgage qualification.
8. Don't Start Closing Credit Cards Right Before Buying
Here's a mistake buyers sometimes make.
They decide:
“I'm buying a house, so I'm going to clean up my credit.”
Then they start closing accounts.
Be careful.
Closing accounts can potentially affect factors involved in your credit profile.
Before making major changes, talk to your lender.
The same goes for:
- Opening new credit cards
- Financing furniture
- Buying a vehicle
- Taking out personal loans
- Co-signing for somebody
- Making unusual large financial moves
When you're preparing for a mortgage, don't make major credit decisions without understanding how they could affect your financing.
9. Please Don't Buy the New Truck Before Closing 😂
You've found the house.
You're under contract.
Everything looks great.
Then:
“Jay! Check out my new $70,000 truck!”
Please don't do that to your lender. 😂
Taking on new debt before closing could affect your debt-to-income ratio, credit profile or loan qualification.
Mortgage lenders may verify financial information again during the process.
So until your transaction is completely closed:
Ask your lender before taking on new debt or making major financial changes.
The truck will still be there after closing.
10. What If You Have Collections?
Collections don't automatically tell us everything we need to know about whether you can qualify.
The type, amount, age and loan program can matter, along with lender requirements and the rest of your financial profile.
Don't automatically start paying or settling accounts solely because you assume that's what a mortgage lender wants.
Talk with your lender first.
Why?
Because changing a credit account can sometimes affect your credit profile in ways you weren't expecting.
Get professional guidance based on your actual report.
11. What About Late Payments?
Payment history is an important component of credit.
Recent late payments may be more concerning in some financing situations than older issues, but the exact impact depends on the circumstances and underwriting requirements.
If you have late payments:
Don't hide them.
Tell your lender what's going on.
Maybe it's something that prevents qualification today.
Maybe it isn't.
Maybe you simply need time to establish a stronger recent payment history.
Again:
We want a game plan, not a guess.
12. Can You Improve Your Credit Before Buying?
Potentially, yes.
But I don't want to give everybody the same generic:
“Pay everything off and your score will go up!”
Credit doesn't always behave that simply.
Depending on your situation, a lender or qualified credit professional may suggest focusing on particular issues.
The strategy could involve things such as:
- Paying bills on time
- Managing revolving balances
- Avoiding unnecessary new debt
- Correcting legitimate credit-report errors
- Allowing time for positive history
- Addressing specific accounts appropriately
The correct strategy depends on your credit profile.
13. How Long Does It Take to Improve Credit?
Here's another question with an annoying answer:
It depends. 😂
Some issues may be addressed relatively quickly.
Others take time.
If you're hoping to buy a home in the next year, don't wait until your lease has 30 days remaining before asking about your credit.
Start early.
If you discover you're not mortgage-ready today, having:
6 months
or
12 months
to work on the situation is a whole lot better than having 30 days.
14. A Higher Credit Score May Still Be Valuable
This article isn't saying:
“Credit scores don't matter.”
They absolutely can.
Even if you can qualify at a particular score, improving your overall credit profile may potentially affect available loan terms, pricing, mortgage insurance or other financing factors.
That's a conversation worth having with your lender.
Ask:
“If I buy now, what does my financing look like?”
Then ask:
“If I improve my credit, what could potentially change?”
Now you have information you can actually use.
15. Don't Wait for a “Perfect” Credit Score Either
There's another side to this.
Some buyers keep waiting because they want:
700
Then they hit 700 and decide they want:
720
Then 740.
Then mortgage rates need to drop.
Then prices need to drop.
Then suddenly three years have gone by.
You don't necessarily need perfect credit to explore buying a home.
You need to understand:
Where you are today
and
What your available options look like today.
Then you can decide whether buying now or waiting makes more sense for you.
What If Your Credit Isn't Good Enough Right Now?
Great.
Now we know.
That's actually progress.
Instead of:
“I probably can't buy a house.”
we can turn the conversation into:
“Here's what I need to work on before I buy.”
Maybe that's three months.
Maybe six.
Maybe twelve.
Maybe longer.
The important part is that you have a direction.
And when you're ready, we start looking at houses.
Stop Disqualifying Yourself
If you're thinking about buying a home in San Antonio but credit is the thing stopping you, don't reject yourself before a lender even reviews your situation.
Maybe you're ready.
Maybe you're closer than you think.
Maybe you need some work.
Let's find out.
🔑 Text KEY to 726.224.4727
Tell me:
“I'm worried about my credit.”
I'll help you figure out the next step and connect you with a lender who can evaluate your actual situation.
Follow @jaylopezrealtor for San Antonio homes, first-time buyer education, VA information, new construction and real estate tips.
Buy a damn house.
Categories
Recent Posts