Can You Buy a Manufactured Home With a VA Loan?
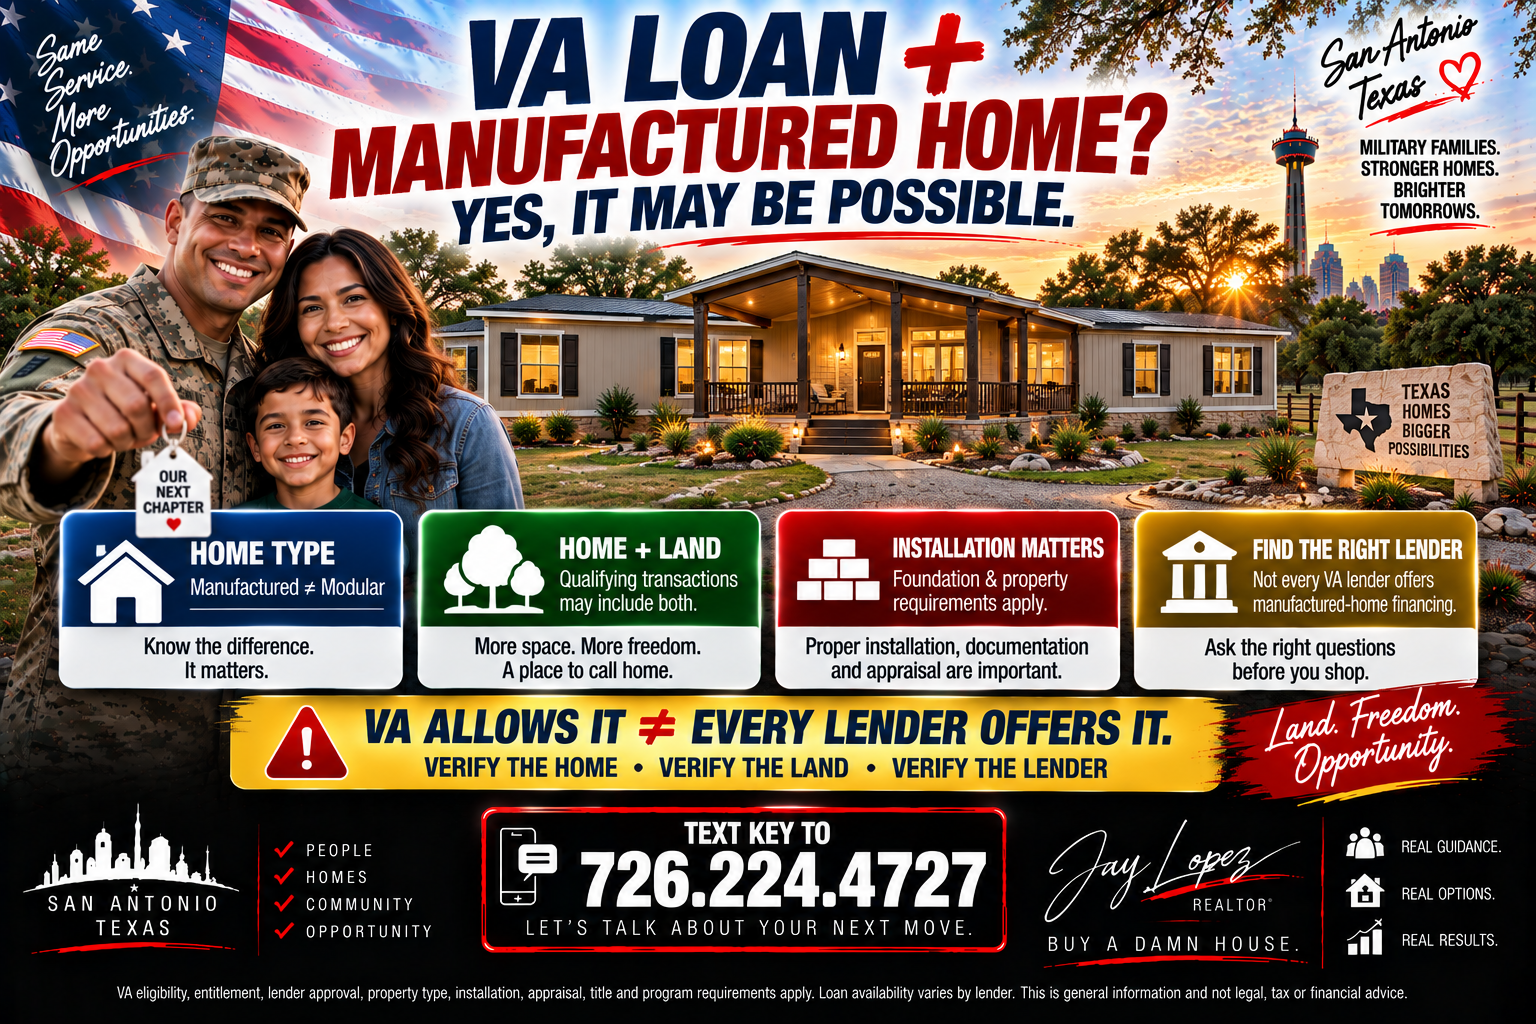
Here's one of those VA questions where the answer is:
YES... BUT THERE'S MORE TO IT.
Eligible Veterans and service members may be able to use VA financing to purchase a manufactured home, including certain transactions involving the home and the land.
But this is where I want you to understand the difference between:
VA ALLOWS IT
and:
EVERY VA LENDER OFFERS IT.
Those are absolutely not the same thing.
If you're considering a manufactured home around San Antonio or elsewhere in Texas, let's break down what you need to know before you start shopping.
First: What Is a Manufactured Home?
This terminology gets confusing fast.
People say:
Mobile home
Manufactured home
Modular home
Trailer
Prefab home
like they're all the same thing.
They're not.
For federal purposes, a manufactured home is generally a home constructed in a factory to the federal Manufactured Home Construction and Safety Standards—commonly known as the HUD Code—and transported to its site. The HUD Code took effect for homes manufactured beginning June 15, 1976.
That date matters.
A manufactured home built to the applicable HUD standards is different from an older mobile home built before those federal standards took effect.
Manufactured Home vs. Mobile Home
Here's the easiest distinction:
🏠 MANUFACTURED HOME
Built under the federal HUD Code after the federal standards took effect.
🚐 MOBILE HOME
A term commonly associated with factory-built homes constructed before June 15, 1976, although people still casually use “mobile home” to describe newer manufactured homes.
From a financing standpoint:
THE DISTINCTION MATTERS.
So don't rely only on what the seller calls it in an advertisement.
What About a Modular Home?
A modular home is different again.
A modular home is constructed in sections in a factory and assembled on-site, but it is generally built to applicable state and local building codes rather than the federal HUD manufactured-housing code.
Once completed, a modular home may look nearly identical to a traditionally site-built house.
So:
Manufactured ≠ Modular
And the financing treatment may differ.
Can VA Finance a Manufactured Home?
POTENTIALLY, YES.
VA's home loan program permits eligible borrowers to use the benefit for certain manufactured-home transactions, subject to VA requirements and lender approval.
Depending on the transaction, that may include buying:
A manufactured home and the land
or certain other qualifying manufactured-home arrangements.
But before you get excited about a listing:
CALL THE LENDER.
Why Finding the Right Lender Matters
This may be the biggest practical issue.
A lender can offer:
VA LOANS
without necessarily offering:
VA MANUFACTURED-HOME LOANS.
Individual lenders establish the loan products they choose to originate, subject to VA and other requirements.
So when calling lenders, don't simply ask:
“Do you do VA loans?”
Ask:
“DO YOU FINANCE MANUFACTURED HOMES USING VA?”
Then get more specific.
Questions to Ask the Lender Before Shopping
Ask:
1. Do you currently offer VA financing on manufactured homes?
2. What property types do you accept?
3. Do you require the borrower to own the land?
4. What foundation requirements apply?
5. Are there age requirements for the manufactured home?
6. Do you finance single-section homes, multi-section homes, or both?
7. What documentation will you need?
8. Can you finance the home and land together?
9. Do you finance a manufactured home being placed on land?
10. What additional lender overlays apply?
Get those answers before spending weeks looking at properties.
Does the Manufactured Home Need a Permanent Foundation?
This is another major issue.
VA property requirements for manufactured housing can involve how the home is installed and attached to the site, and lenders may require evidence that the foundation and installation satisfy applicable standards.
The exact transaction and property matter.
That's why a listing saying:
“Manufactured home on 2 acres!”
doesn't automatically tell us:
“VA ELIGIBLE.”
We need to know what we're actually dealing with.
What About the HUD Certification Labels?
Manufactured homes built under HUD standards generally have certification labels attached to the exterior of each transportable section.
You'll sometimes hear these called:
HUD tags
or:
HUD labels.
There's also typically a manufacturer's data plate inside the home containing important information about the property.
Those identifiers can become important during financing and appraisal.
So if we're considering an older manufactured home:
DOCUMENTATION MATTERS.
What If the HUD Labels Are Missing?
Don't immediately assume the deal is impossible.
But don't ignore it either.
Missing labels or documentation can create additional work because the lender and other parties may need acceptable verification of the home's manufacturing information and compliance.
This is exactly the kind of issue I want discovered:
BEFORE
we're two days from closing.
😂
Can the VA Loan Include the Land?
Depending on the qualifying transaction, VA financing may potentially involve both the manufactured home and the land on which it sits.
That's important because many Texas buyers aren't looking for:
“A manufactured home in a park.”
They're looking for:
HOME + LAND.
Maybe one acre.
Maybe five.
Maybe something outside the city.
That can be an attractive option—but the financing, title, appraisal, improvements and property requirements all need to work together.
What If I Already Own the Land?
That's another scenario worth discussing with a VA lender experienced in manufactured housing.
If you already own the lot and want to place a manufactured home on it, the transaction structure can differ from simply buying an existing home already attached to its site.
Before ordering the home:
TALK TO THE LENDER FIRST.
Do not buy a manufactured home and then discover afterward that your intended VA financing won't work.
Can I Use VA to Buy Just the Manufactured Home?
This becomes more complicated.
VA manufactured-home financing rules can vary depending on whether you're purchasing the home alone, the home plus land, or improving a lot for the home.
And lender availability can be much narrower for certain structures.
That's why this isn't the type of transaction where I want to say:
“Sure, VA does that!”
without knowing the exact deal.
The better answer is:
LET'S IDENTIFY THE PROPERTY AND FIND A LENDER THAT ACTUALLY OFFERS THE RIGHT VA PRODUCT.
Can You Get $0 Down?
Potentially.
Eligible VA borrowers with sufficient entitlement may be able to obtain qualifying VA financing without a VA-required down payment.
But just like every other article in this series:
$0 DOWN ≠ $0 OUT OF POCKET.
You could still have expenses associated with:
Closing costs
Prepaid items
Inspection expenses
Appraisal
Insurance
Contract deposits
and other transaction-specific costs.
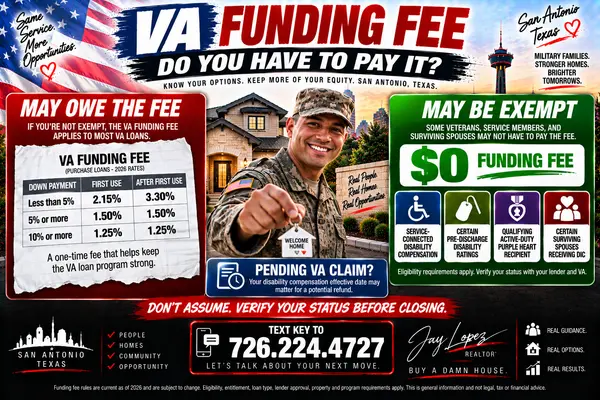
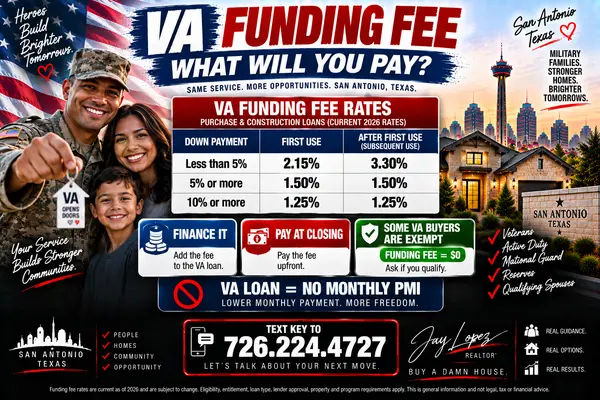
Does the VA Funding Fee Apply?
For non-exempt borrowers, a VA funding fee may apply.
Manufactured-home loan types can have their own funding-fee treatment depending on how the transaction is structured.
If you're exempt from the funding fee under VA rules, that can change the calculation.
So before comparing financing:
VERIFY YOUR FUNDING-FEE STATUS.
That's exactly why we covered Blogs #31 and #32 first.
Does a Manufactured Home Need a VA Appraisal?
YES, WHEN USING VA-BACKED PURCHASE FINANCING.
The appraisal addresses value and applicable VA property requirements.
But manufactured homes can create additional appraisal considerations because the appraiser needs to understand exactly what property is being financed.
For example:
Is land included?
What improvements are attached?
How is the home installed?
What comparable sales are available?
The more unusual the property, the more important good documentation becomes.
And Remember...
🚨 VA APPRAISAL ≠ HOME INSPECTION
That rule doesn't disappear because the house was built in a factory.
😂
The appraisal and inspection still have different purposes.
A qualified inspector can help evaluate the actual condition of the home and its accessible systems and components.
What Should You Inspect on a Manufactured Home?
Depending on the property, inspection considerations may include:
Roof
Plumbing
Electrical
HVAC
Water heater
Flooring and subfloor
Moisture
Exterior
Windows and doors
Foundation/support system
and other accessible components.
If the property uses:
Well
Septic
or other private systems,
those can create additional due-diligence and financing considerations.
Texas Buyers: Pay Attention to the Land Too
This is where manufactured homes can become especially interesting around the San Antonio area.
You may find a home sitting on a larger parcel.
Great.
But you're not just evaluating the house.
You're evaluating:
THE WHOLE PROPERTY.
That can include:
Access
Survey
Easements
Utilities
Water source
Septic
Flood considerations
Road maintenance
Restrictions
HOA or property-owner association requirements
and other property-specific factors.
Buying five acres isn't automatically better than buying a subdivision lot.
It just gives you a different list of questions.
Is the Home Real Property or Personal Property?
This is a major issue with manufactured housing.
Manufactured homes can sometimes be treated differently depending on how they're titled and whether they're legally attached to the land as real property.
For a real-estate mortgage transaction, we need to understand:
WHAT EXACTLY IS BEING CONVEYED?
The home?
The land?
Both?
How is the home titled?
Has the appropriate documentation been completed?
This is an area where the lender and title professionals become extremely important.
Don't Assume a Manufactured Home Listing Is Ready for VA Financing
Here's an example.
You see:
3 bedrooms
2 bathrooms
1.5 acres
$225,000
Looks fantastic.
You call me:
“JAY! I FOUND IT!”
😂
Before we celebrate, we need to determine things like:
What year was it manufactured?
Does it have the necessary identifying documentation?
How is it attached to the property?
How is it titled?
Does our VA lender finance this property type?
Will the property satisfy applicable requirements?
Is there adequate market data for the appraisal?
Now we're actually evaluating the deal.
Are Manufactured Homes Cheaper?
They can offer a different price point from many site-built properties.
But don't automatically assume:
“Manufactured = cheap.”
Your total cost can include:
Land
Home
Site preparation
Foundation
Utility connections
Well or water
Septic
Driveway
Transportation
Installation
and potentially other expenses.
A lower home price doesn't necessarily mean a lower completed-project cost.
Manufactured Home + Raw Land: Watch the Budget
Imagine:
Manufactured home: $180,000
and:
Land: $80,000
You might think:
“$260,000. Done.”
Not necessarily.
What about:
Site preparation?
Foundation?
Utility connections?
Septic?
Well?
Driveway?
Permitting?
Delivery and installation?
That's why buying an already installed manufactured home on land can be very different from creating the entire property from scratch.
What About Insurance?
Get insurance quotes early.
Manufactured-home insurance availability and cost can differ depending on:
Age
Location
Construction
Condition
Property characteristics
and the insurer.
Your lender will need acceptable insurance before closing.
Don't wait until the end of the transaction to investigate it.
What About Property Taxes?
If you're purchasing the home and land as real property, property taxes become part of the affordability calculation.
Don't look only at:
PURCHASE PRICE.
Your monthly housing budget can include:
Principal
Interest
Taxes
Insurance
and any applicable association costs.
Again:
BUY THE PAYMENT THAT WORKS FOR YOU.
What About VA Minimum Property Requirements?
The property still has to satisfy applicable VA requirements.
Manufactured doesn't mean:
“VA ignores the property standards.”
And it doesn't mean:
“VA won't finance it because it isn't site-built.”
The correct answer sits between those extremes.
The specific property has to qualify.
Can You Buy an Older Manufactured Home?
Potentially, but this is where the manufacturing date, documentation, property condition and lender requirements become especially important.
Remember:
JUNE 15, 1976
is a major dividing line because that's when HUD's federal manufactured-home construction standards took effect.
Lenders may also impose additional requirements beyond VA's baseline program rules.
So the older the home:
ASK MORE QUESTIONS EARLIER.
Can You Buy a Manufactured Home That Has Been Moved?
This can be another difficult area.
A home that has been relocated from its original installation site can create additional eligibility and lender issues.
Lender policies can be particularly restrictive here.
If the property has been moved:
TELL THE LENDER IMMEDIATELY.
Don't assume it doesn't matter.
Why Manufactured-Home VA Loans Can Be Harder to Find
Here's the frustrating part.
A Veteran may be eligible.
The property type may be permitted under VA rules.
And yet:
Lender A doesn't offer the loan.
That doesn't necessarily mean:
“VA DOESN'T ALLOW IT.”
It may mean:
“THAT LENDER DOESN'T OFFER IT.”
This distinction can save you a lot of frustration.
Military Buyers: Could This Be an Option Around San Antonio?
Potentially.
For a buyer who values:
More land
Fewer subdivision-style features
Space for hobbies
Room between neighbors
or simply a different housing price point,
manufactured housing may be worth exploring.
But I'm not going to tell you:
“This is the best option for military buyers.”
That's your decision.
We'll compare objective factors such as:
Price
Monthly payment
Commute
Land
Taxes
Utilities
Maintenance
Financing
and resale considerations.
Then you decide what fits.
Your VA Manufactured-Home Game Plan
If this is something you're considering, here's the order I'd use:
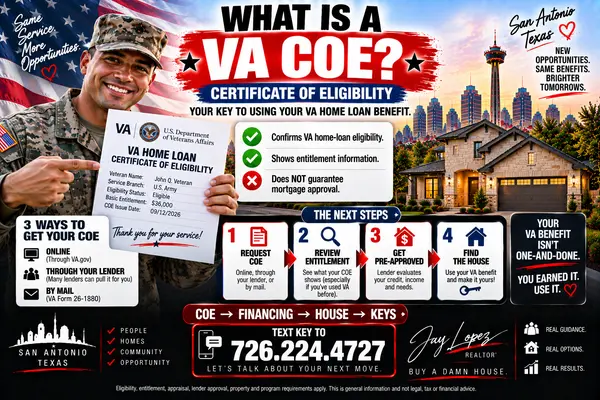
🇺🇸 STEP 1 — VERIFY VA ELIGIBILITY
Get your COE.
🏦 STEP 2 — FIND THE RIGHT VA LENDER
Specifically ask about manufactured homes.
💰 STEP 3 — GET PRE-APPROVED FOR THAT PROPERTY TYPE
Not just a generic VA pre-approval.
🏠 STEP 4 — IDENTIFY THE TYPE OF HOME
Manufactured?
Modular?
Older mobile home?
Know what you're buying.
📄 STEP 5 — VERIFY PROPERTY DOCUMENTATION
HUD information, title status and other required records.
🌳 STEP 6 — UNDERSTAND THE LAND
Owned land?
Included in purchase?
Utilities?
Septic?
Access?
🔍 STEP 7 — INSPECT THE PROPERTY
Appraisal does not replace inspection.
🇺🇸 STEP 8 — COMPLETE THE VA APPRAISAL
Value + applicable property requirements.
🏦 STEP 9 — COMPLETE UNDERWRITING
Property and borrower both have to work.
🔑 STEP 10 — CLOSE
Home + land + VA benefit.
Questions to Ask Before Making an Offer
Save this list.
Is this legally a manufactured home or modular home?
When was it manufactured?
Is the land included?
How is the home titled?
Has it been moved from another location?
Is it permanently installed?
Are the HUD labels/data information available?
What utilities serve the property?
Is there a well or septic system?
Does my lender finance this exact property type?
What inspection or engineering documentation may be required?
What does the VA appraisal need?
Those questions can save you from wasting a lot of time.
The Bottom Line
🇺🇸 YES—VA FINANCING MAY BE USED FOR QUALIFYING MANUFACTURED HOMES.
But manufactured housing has additional layers that buyers need to understand.
The biggest issues are often:
PROPERTY TYPE
LAND
FOUNDATION / INSTALLATION
TITLE & DOCUMENTATION
APPRAISAL
and:
FINDING A VA LENDER THAT ACTUALLY FINANCES MANUFACTURED HOMES.
Don't see a manufactured home online and immediately assume:
“VA won't finance that.”
But don't assume the opposite either.
VERIFY THE HOME. VERIFY THE LAND. VERIFY THE LENDER.
Then make your decision.
Looking for a VA Home Around San Antonio?
Whether you're looking at a traditional home, new construction or manufactured housing, let's figure out which options actually fit your situation.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
Approximate budget
Home only or home + land
and:
When you're planning to buy.
Example:
“KEY — Veteran — $250K — looking for a home with land.”
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house. 🇺🇸🔑
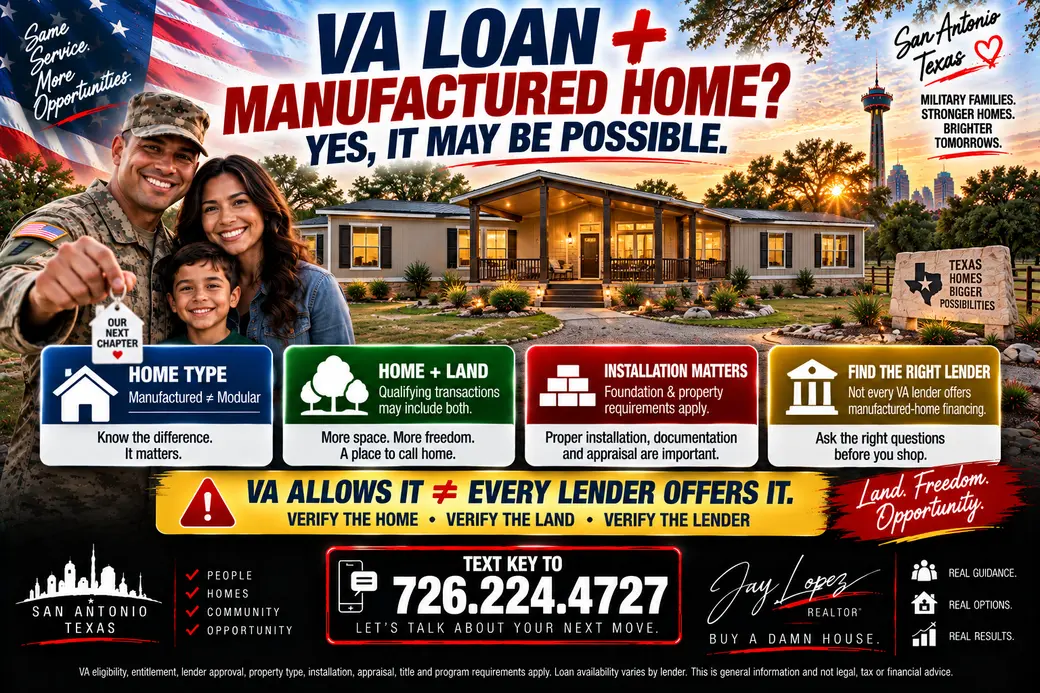
Featured Image Concept
Let's make this look completely different from the last new-construction image.
Use a beautiful modern double-section manufactured home on Texas acreage at golden hour—covered porch, clean landscaping, mature oak trees, long driveway and plenty of land.
Military buyer standing near the property holding keys.
Subtle San Antonio/Texas identity rather than a downtown-heavy background.
MAIN HEADLINE:
🇺🇸 VA LOAN + MANUFACTURED HOME?
YES, IT MAY BE POSSIBLE.
Four large checklist cards:
🏠 HOME TYPE
Manufactured ≠ Modular
🌳 HOME + LAND
Qualifying transactions may include both
🔩 INSTALLATION MATTERS
Foundation & property requirements apply
🏦 FIND THE RIGHT LENDER
Not every VA lender offers manufactured-home financing
Large warning strip:
VA ALLOWS IT ≠ EVERY LENDER OFFERS IT
Then:
VERIFY THE HOME • VERIFY THE LAND • VERIFY THE LENDER
Bottom CTA:
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts