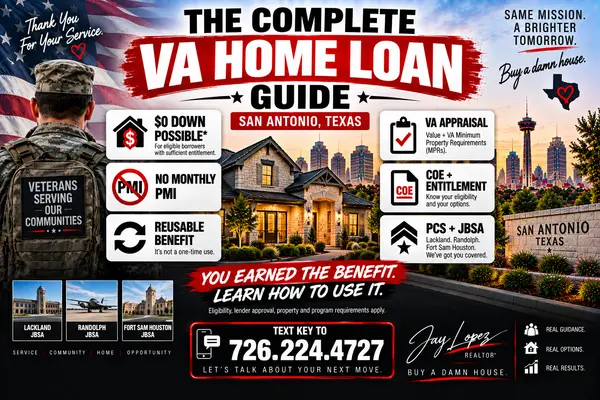
Can You Really Buy a House With $0 Down Using a VA Loan?
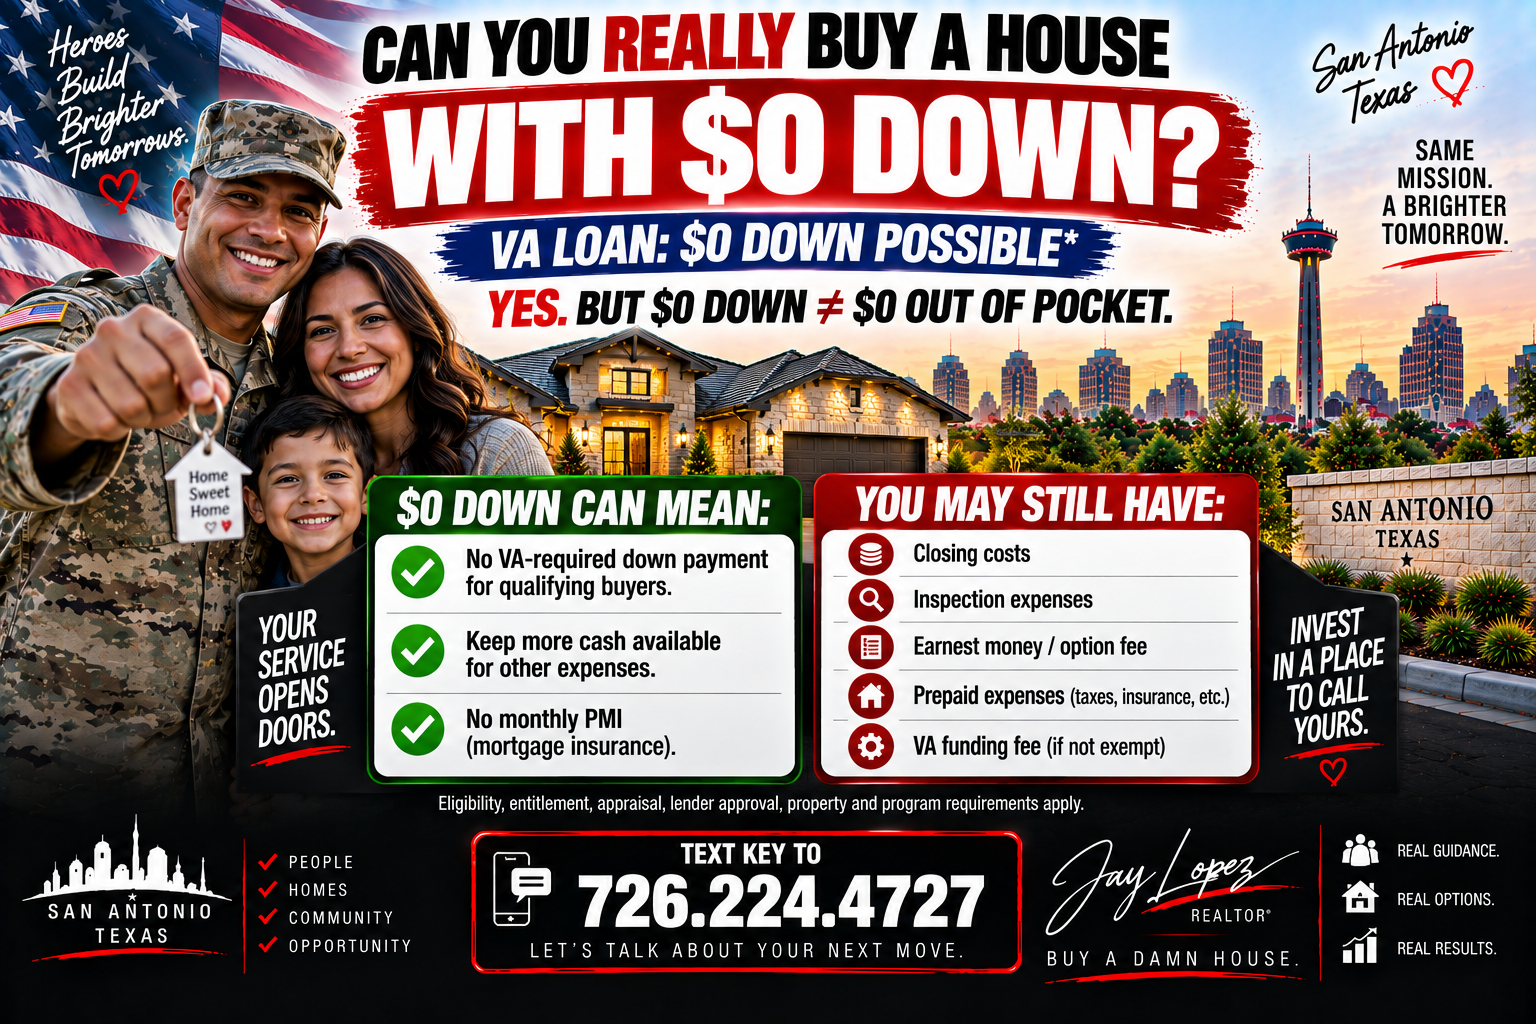
You've probably seen the advertisement:
BUY A HOUSE WITH $0 DOWN!
And your immediate reaction might be:
“Okay...what's the catch?”
Fair question.
Because we've all seen advertisements that sound amazing until you read the 47 lines of tiny print at the bottom.
😂
But the zero-down feature of the VA home loan program is real.
VA says an eligible borrower using a VA-backed purchase loan may be able to buy with no down payment, provided the sales price isn't above the home's appraised value and applicable VA and lender requirements are met.
However...
There's an important distinction every Veteran should understand:
$0 DOWN DOES NOT MEAN $0 OUT OF POCKET.
Let's break that down.
What Does “$0 Down” Actually Mean?
A down payment is the portion of the purchase price you pay upfront rather than finance.
With many mortgage programs, the buyer contributes a percentage of the purchase price as a down payment.
With qualifying VA financing?
An eligible borrower may potentially finance 100% of the purchase price, subject to the property's appraised value, entitlement, lender approval and other program requirements.
For example:
Purchase price: $300,000
A qualifying VA borrower may potentially have:
Required down payment: $0
That is very different from saying:
Total money needed to buy the house: $0.
Why Does VA Allow Zero Down?
VA-backed purchase loans are generally made by private lenders.
The Department of Veterans Affairs guarantees a portion of the loan against loss.
That VA guaranty allows lenders to offer eligible borrowers certain favorable terms, including the possibility of purchasing without a down payment.
It's one of the major benefits of the program.
So Who Can Potentially Use $0 Down?
First, you need to be eligible for the VA home loan benefit.
That generally starts with your:
Certificate of Eligibility — COE
The COE establishes your eligibility for the VA home loan benefit and provides entitlement information.
But your COE is not a mortgage approval.
You still need to satisfy your lender's standards for credit, income and other requirements, and the property must satisfy applicable requirements.
What Is VA Entitlement?
This is where things sometimes get confusing.
Your entitlement is connected to the amount VA will guarantee on your loan.
For many first-time VA users with full entitlement, the calculation can be relatively straightforward.
But if you've previously used your VA benefit—or currently have another VA-backed loan—your remaining entitlement may affect how much you can borrow without a down payment.
So don't assume:
“I've used VA before, so zero down isn't available anymore.”
Have a VA-knowledgeable lender review your COE and entitlement.
Do You Need Perfect Credit for $0 Down?
No universal VA rule says:
“You must have exactly ___ credit score.”
VA itself does not establish one universal minimum credit score for its guaranty.
However, lenders evaluate credit and can impose their own standards.
So:
VA eligibility ≠ automatic loan approval.
Your lender still evaluates your overall mortgage profile.
Here's the Part People Miss: Closing Costs
Let's say your required down payment is:
$0
Awesome.
You can still encounter closing costs.
VA's current guidance explains that purchase-loan closing costs vary based on the loan, property location, lender fees, funding-fee status and other factors.
Those can potentially include items associated with:
The loan
Title
Appraisal
Insurance
Taxes
Recording
and other transaction expenses.
That's why:
ZERO DOWN ≠ FREE HOUSE.
😂
Can You Finance Your Closing Costs Into the VA Purchase Loan?
Generally, not the ordinary closing costs.
VA states that on a purchase or construction/permanent loan, the VA funding fee can be financed into the loan, but other fees and charges can't simply be rolled into the purchase loan amount in the same way.
That makes closing-cost planning important.
But there may be other ways the transaction is structured.
Can the Seller Help With Closing Costs?
Potentially, yes.
VA allows sellers or builders to provide credits toward certain buyer closing costs. VA distinguishes ordinary closing-cost credits from seller concessions, with concessions subject to a 4% limit based on the home's reasonable value.
The details matter.
And most importantly:
Seller assistance is negotiated.
A seller isn't automatically required to pay your costs simply because you're using VA financing.
This Is Where Your Offer Strategy Matters
Imagine two scenarios.
Scenario A
Home price: $325,000
Buyer wants $0 down.
Buyer pays applicable closing expenses from available funds.
Scenario B
Home price: $325,000
Buyer wants $0 down.
Buyer negotiates allowable seller assistance toward certain closing expenses.
Both may involve a VA loan.
But the buyer's potential cash requirement can look very different.
That's why we evaluate the entire offer, not simply the down payment.
What About New Construction?
This is where San Antonio VA buyers may find additional opportunities.
Builders periodically offer incentives on qualifying inventory homes.
Depending on the current promotion, those incentives might include:
Closing-cost assistance
Rate incentives
Temporary or permanent rate buydowns
or other offers.
But builder promotions can change quickly and typically have eligibility, financing and property requirements.
Never assume the advertisement applies to every buyer or every home.
Verify the actual offer.
Could a VA Buyer Buy With Very Little Cash Out of Pocket?
Potentially.
Imagine an eligible VA buyer with sufficient entitlement who:
Uses qualifying VA financing
Has no required down payment
and
Negotiates allowable assistance toward certain closing costs.
That combination can potentially reduce the amount of cash needed substantially.
But I'm deliberately not promising:
“MOVE IN FOR $0!”
Because every transaction is different.
You may still need funds during the process.
What About Earnest Money?
Earnest money and down payment are not the same thing.
In a Texas purchase contract, the buyer and seller may negotiate earnest money as part of the transaction.
If you deposit earnest money, that doesn't automatically mean you've suddenly made a mortgage down payment.
The funds are handled according to the contract and ultimately accounted for in the closing transaction as applicable.
So even a zero-down VA buyer may need accessible funds earlier in the process.
What About the Option Fee?
Texas contracts may also include a separately negotiated option fee to establish a termination option.
Again:
Option fee ≠ mortgage down payment.
It's part of the real estate contract.
That's another reason I don't want Veterans hearing:
“VA is zero down!”
and assuming they need absolutely no money available during the purchase process.
What About the Home Inspection?
The home inspection is another potential buyer expense.
And please don't say:
“I'm getting a VA appraisal, so I don't need an inspection.”
Nope.
VA APPRAISAL ≠ HOME INSPECTION.
They serve different purposes.
Budgeting for appropriate inspections can be part of a responsible home-buying plan.
What About the VA Appraisal?
VA financing generally requires an appraisal as part of the loan process.
The appraisal addresses value and applicable VA property requirements.
Here's where the zero-down feature becomes especially important:
VA describes no-down-payment financing as available when the sales price isn't higher than the home's appraised value.
So what happens if the price is above the VA-established value?
That's a different situation.
Example: Purchase Price Is Higher Than Appraised Value
Imagine:
Contract price: $350,000
VA appraised value: $340,000
That doesn't mean VA automatically finances:
$350,000 with nothing down.
The buyer and seller may need to evaluate their options based on the contract, financing and VA requirements.
That could involve negotiation or other transaction-specific decisions.
Don't assume the zero-down benefit means VA will finance any price a buyer agrees to pay.
What Is the VA Funding Fee?
Many VA borrowers also encounter the:
VA FUNDING FEE
This is a one-time fee associated with many VA loans.
For purchase and construction loans, the current VA funding-fee rate depends on whether it's your first or subsequent use and how much, if anything, you put down. VA currently lists a 2.15% fee for first use with less than 5% down and 3.3% for subsequent use with less than 5% down, unless the borrower qualifies for an exemption.
Unlike ordinary purchase closing costs, the funding fee can generally be financed into the loan.
Some Veterans Don't Pay the Funding Fee
Certain borrowers are exempt.
VA's current guidance includes qualifying borrowers receiving or eligible for VA compensation for a service-connected disability, certain surviving spouses receiving DIC, qualifying active-duty Purple Heart recipients and certain other circumstances.
Have your exemption status verified.
Don't assume.
VA Doesn't Require Monthly Mortgage Insurance
Here's another major feature.
VA-backed purchase loans don't require monthly PMI or MIP.
That's important because some other low-down-payment financing can include monthly mortgage-insurance costs.
So when comparing loan programs, don't compare only:
Down payment.
Compare the whole estimated monthly payment and total financing structure.
Should You Put Money Down Anyway?
Here's something Veterans sometimes don't realize:
You CAN make a down payment on a VA loan.
Just because zero down may be available doesn't mean you must finance the entire eligible amount.
Why might somebody choose to put money down?
Depending on the situation, it could:
Reduce the loan balance
Reduce the monthly principal-and-interest payment
and, for a non-exempt borrower, potentially affect the funding-fee percentage when applicable thresholds are met. VA's current purchase-loan funding-fee schedule has lower rates at 5% and 10% down.
Whether that's the best use of your cash is a conversation to have with your lender and financial professionals.
Don't Empty Your Savings Just Because You Can
Suppose you have:
$30,000 saved.
And you're eligible for zero-down VA financing.
Should you automatically put all $30,000 down?
Not necessarily.
Consider your broader financial picture.
You may need money for:
Emergency reserves
Moving
Repairs
Furniture
Future expenses
and life in general.
You don't want to get the keys and immediately have:
$86 left in checking.
😂
San Antonio VA Buyers: Look at the TOTAL Deal
Let's say you're comparing two homes.
HOME A — RESALE
Lower purchase price.
But perhaps fewer seller contributions.
HOME B — NEW CONSTRUCTION
Higher purchase price.
But perhaps there's a current qualifying financing or closing-cost incentive.
Which is better?
You can't tell from those facts alone.
We need to compare:
Price
Estimated payment
Taxes
Insurance
HOA
Financing
Closing costs
Incentives
and your longer-term plans.
$0 Down Is a Tool—Not the Entire Strategy
This is the point I want Veterans to remember.
The VA loan isn't valuable simply because:
“I don't have to put money down.”
Its value can involve several features working together.
Potential zero down.
No monthly mortgage insurance.
Reusable benefit.
Different closing-cost rules.
And other protections and program features.
But it still needs to fit:
YOUR finances and YOUR goals.
Your Zero-Down VA Checklist
Before you start shopping, answer these:
🇺🇸 Do I have VA home loan eligibility?
📄 Has my COE been reviewed?
🏦 Have I spoken with a VA-knowledgeable lender?
💰 Do I understand my estimated cash-to-close?
🧾 Do I know whether I'm funding-fee exempt?
📊 Do I know my comfortable monthly payment?
🏠 Do I understand the VA appraisal?
🔍 Have I budgeted for inspections?
📍 Do I know where I want to live around San Antonio?
If yes?
Now let's go find the house. 🔑
So...Can You Really Buy a House With $0 Down Using VA?
YES—qualifying VA buyers may be able to purchase with no down payment required by the VA program.
But remember:
$0 DOWN ≠ $0 OUT OF POCKET.
That's the sentence I want you to remember.
Don't shop based on an advertisement.
Find out:
Your eligibility
Your entitlement
Your financing
Your cash requirements
and
Your actual payment.
Then make the decision.
Want to See What $0-Down VA Could Look Like for You?
Let's start with the numbers.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
Your approximate timeline
and
Where you'd like to live around San Antonio.
Example:
“KEY — Veteran — 4 months — near Randolph.”
We'll start there.
Follow @jaylopezrealtor for San Antonio VA homes, PCS information, new construction and military home-buying education.
Buy a damn house. 🇺🇸🔑
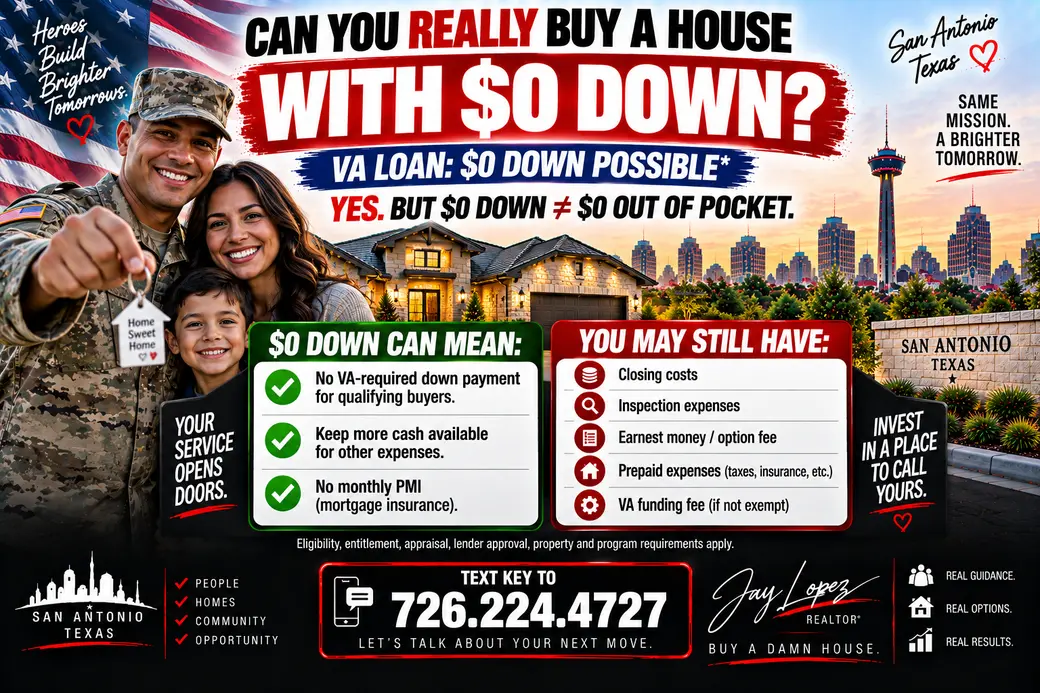
Featured Image Concept
This one should be extremely simple and scroll-stopping, because the "$0 DOWN" is the hook.
Main Headline
🇺🇸 CAN YOU REALLY BUY A HOUSE WITH $0 DOWN?
Huge center:
VA LOAN: $0 DOWN POSSIBLE*
Under it:
YES. BUT $0 DOWN ≠ $0 OUT OF POCKET.
Split the graphic:
LEFT — $0 DOWN CAN MEAN
✅ No VA-required down payment for qualifying buyers
✅ Keep more cash available
✅ No monthly PMI
RIGHT — YOU MAY STILL HAVE
💰 Closing costs
🔍 Inspection expenses
📝 Earnest money / option fee
🏡 Prepaid expenses
🇺🇸 VA funding fee if not exempt
Bottom qualifier:
Eligibility, entitlement, appraisal, lender approval, property and program requirements apply.
Visual: Veteran/military household standing in front of a modern San Antonio home holding keys, with subtle American flag elements and the Tower of the Americas in the background.
Use the patriotic red/white/blue + Jay's black/deep-red branding established with Blog #26.
Bottom CTA:
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts