The Complete VA Home Loan Guide for San Antonio Buyers
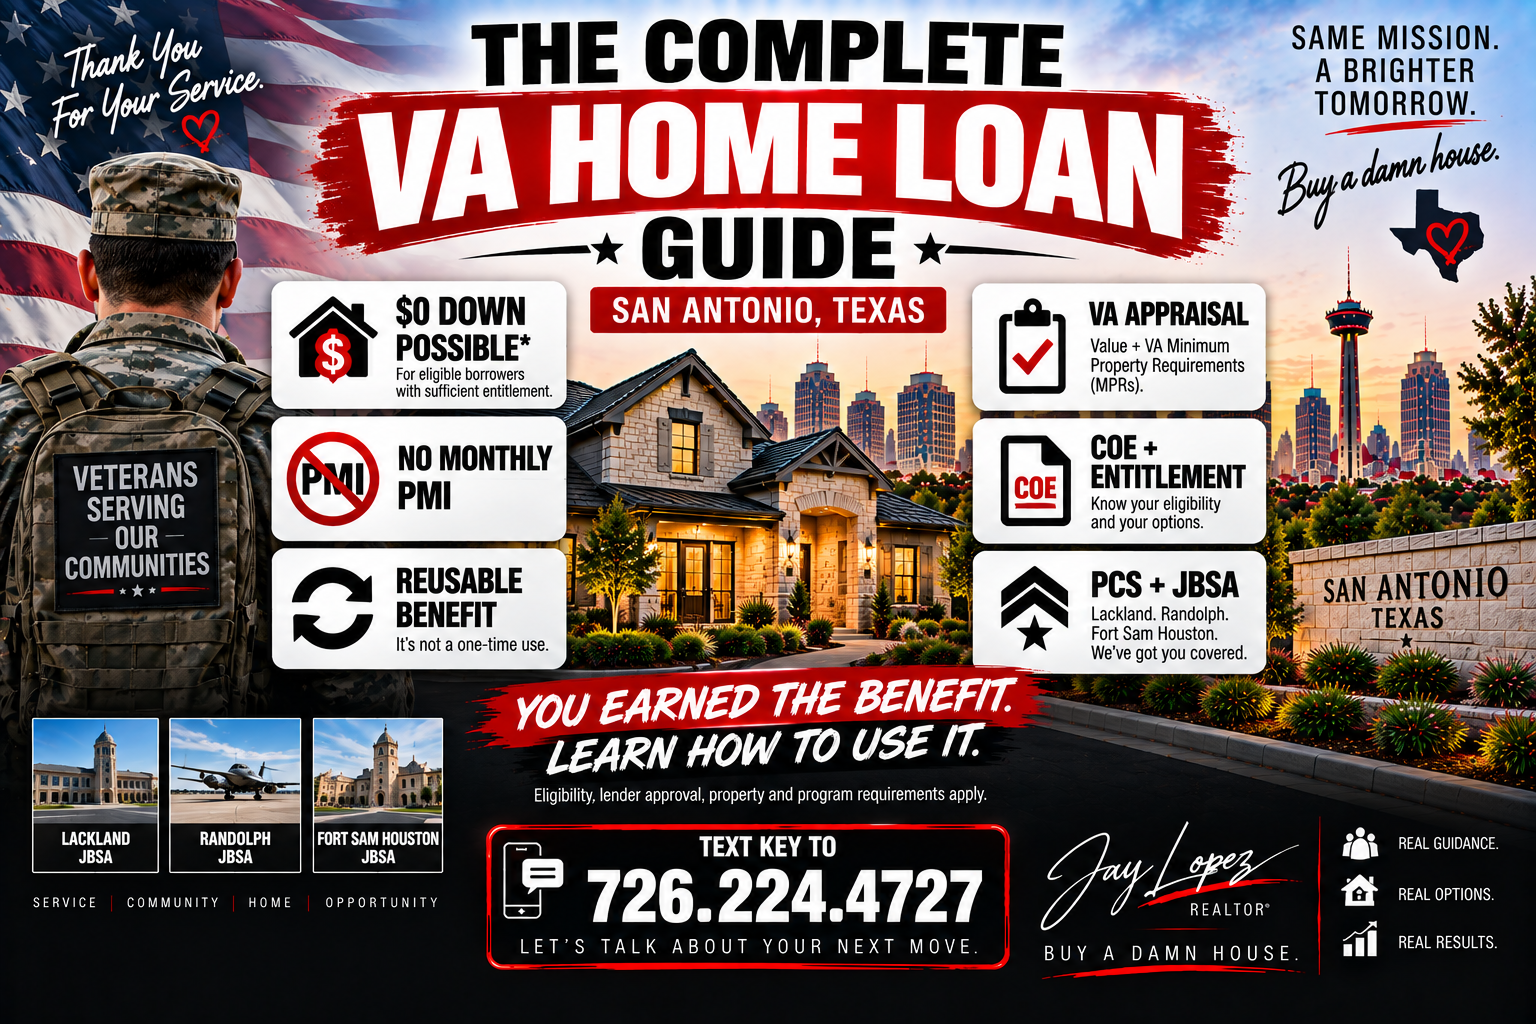
You served.
You earned a VA home loan benefit.
And yet I've met Veterans who know more about their rifle qualification from 20 years ago than they do about one of the most valuable housing benefits available to them today.
😂
Some Veterans assume:
“VA loans are too complicated.”
“Sellers don't like them.”
“I can only use my VA loan once.”
“I need perfect credit.”
“Zero down sounds too good to be true.”
Let's clear this up.
If you're an eligible Veteran, active-duty service member or other qualifying borrower looking to buy in the San Antonio area, understanding the VA loan program can open up options you may not realize you have.
🇺🇸 Welcome to the VA Home Loan Guide.
First: What Is a VA Home Loan?
A VA home loan isn't generally money loaned directly to you by the Department of Veterans Affairs.
Instead, eligible borrowers typically obtain financing through a private lender, and the VA guarantees a portion of the loan.
That guaranty can allow lenders to offer qualified borrowers features that can make VA financing particularly attractive.
Why Are VA Loans So Popular?
Depending on eligibility and the transaction, some of the major features can include:
🇺🇸 No down payment required by the VA program for eligible borrowers with sufficient entitlement
🇺🇸 No monthly private mortgage insurance
🇺🇸 Competitive financing opportunities
🇺🇸 Limits on certain borrower-paid closing costs
🇺🇸 Potential seller concessions within VA rules
🇺🇸 The benefit may be reusable
That doesn't mean every Veteran automatically qualifies for every home or loan amount.
You still have lender underwriting, VA requirements and property requirements.
But it's a benefit worth understanding.
Who May Be Eligible for a VA Home Loan?
VA home loan eligibility depends on qualifying service and other requirements.
Potentially eligible borrowers can include certain:
Veterans
Active-duty service members
National Guard members
Reserve members
and
Surviving spouses
depending on the applicable eligibility rules.
The best way to establish whether you have the necessary eligibility is through your:
Certificate of Eligibility — COE
What Is a COE?
Your Certificate of Eligibility tells the lender that VA records indicate you meet the service requirements for the home loan benefit and provides entitlement information.
It does not mean:
“Congratulations, you're approved for a mortgage.”
😂
Eligibility and mortgage qualification are separate.
You can have a COE and still need to satisfy your lender's underwriting requirements.
Many VA-approved lenders can request the COE electronically, or eligible borrowers can obtain it through VA resources.
Can You Really Buy With $0 Down?
For an eligible borrower with sufficient entitlement:
Potentially, yes.
VA financing can allow qualified borrowers to purchase without a down payment required by the VA loan program.
That's one of the biggest benefits.
But let's fix a common misunderstanding:
$0 DOWN ≠ $0 OUT OF POCKET
You may still have other expenses associated with the transaction.
What Could a VA Buyer Still Need Money For?
Depending on your contract and transaction, costs can potentially include:
Earnest money
Option fee
Home inspection
Closing costs
Prepaid property taxes
Homeowners insurance
and other transaction expenses.
Some of these amounts may ultimately be credited or accounted for at closing depending on the contract.
Your lender and title company can give you transaction-specific numbers.
What About Closing-Cost Assistance?
This is where negotiation can become important.
Depending on the transaction and applicable VA rules, a seller may be able to pay certain buyer closing costs and provide allowable concessions.
That doesn't mean:
“VA buyers always get their closing costs paid.”
No.
It's negotiated.
The market, property, offer and seller all matter.
New Construction Can Be Interesting for VA Buyers
San Antonio has a lot of new-home construction.
Builders sometimes advertise incentives on qualifying inventory that may include things such as:
Closing-cost assistance
Financing incentives
Rate buydowns
or other promotions.
For a qualified VA buyer, those incentives can potentially affect the overall transaction significantly.
But promotions change frequently.
Always verify:
The current incentive
Which homes qualify
Required financing
Lender requirements
and all other conditions.
Do VA Loans Have Mortgage Insurance?
VA-backed loans don't require monthly private mortgage insurance.
That's a significant distinction from certain other low-down-payment financing options.
However, many VA borrowers encounter another cost:
The VA Funding Fee
What Is the VA Funding Fee?
The VA funding fee is a one-time charge that applies to many VA-backed or direct home loans.
The amount can vary based on factors such as:
Type of VA loan
Whether you've used the benefit before
and
Down payment
among other applicable factors.
The funding fee can often be financed into the loan rather than paid entirely in cash at closing.
But don't assume the fee applies to you.
Some Eligible Borrowers May Be Exempt From the Funding Fee
Certain borrowers may qualify for an exemption under VA rules.
For example, qualifying disability-related circumstances can result in funding-fee exemption.
Other statutory exemptions can also apply.
Your COE and lender can help determine whether you're exempt.
Don't guess.
Have it verified.
Does the VA Have a Minimum Credit Score?
This is one of the most common VA myths.
The VA does not establish one universal minimum credit score for VA-guaranteed loans.
But...
Individual lenders can establish their own credit standards.
So when somebody says:
“You need exactly ___ credit score for a VA loan.”
they may actually be describing a particular lender's requirement rather than a universal VA rule.
What If Your Credit Isn't Great?
Talk to a VA-knowledgeable lender.
Don't automatically decide:
“I can't use my VA benefit.”
Your lender can evaluate:
Credit history
Income
Debts
Assets
and the overall mortgage profile.
If you're not ready today, ask:
“What specifically would I need to work on?”
Now you have a plan.
What Is VA Entitlement?
This is one of the more confusing parts of the VA benefit.
Entitlement is essentially the amount of VA guaranty associated with your home loan benefit.
You may hear terms such as:
Basic entitlement
and
Bonus or additional entitlement.
But for most buyers, the practical question is:
“How much entitlement do I currently have available?”
Your lender can review your COE and help determine how your entitlement affects the transaction.
Is There a VA Loan Limit?
This requires an important distinction.
Eligible Veterans with full entitlement generally aren't subject to a VA-imposed loan limit simply because of the VA guaranty.
But that does not mean:
“The VA lets me borrow unlimited money.”
😂
You still need to qualify with the lender.
Your:
Income
Debt
Credit
Property value
and underwriting all matter.
Borrowers with remaining rather than full entitlement can face different guaranty calculations, and county loan limits can become relevant.
Can You Use Your VA Loan More Than Once?
Yes.
The VA benefit isn't necessarily a one-and-done benefit.
Eligible Veterans may be able to use it multiple times.
Entitlement can potentially be restored after certain circumstances, such as disposing of a property and satisfying the VA-backed loan.
There are also situations in which a borrower may have remaining entitlement while another VA-backed loan is still outstanding.
This gets technical quickly.
Your lender should review your COE rather than relying on a generic internet calculator.
Can You Have Two VA Loans at the Same Time?
In some circumstances:
Potentially.
For example, a service member may PCS and retain a property financed with VA while purchasing another primary residence using remaining entitlement.
Whether this works depends on factors including:
Remaining entitlement
County loan limits when relevant
Loan amounts
Occupancy
Income
Debt
and lender underwriting.
This is not automatically available to everyone.
But don't assume:
“I already have a VA loan, so I can't use VA again.”
Have your entitlement calculated.
VA Loans Are for Primary Residences
VA purchase loans are generally intended to finance a home you will occupy as your residence.
They're not designed simply to purchase:
An investment property you never intend to occupy.
Occupancy requirements apply.
That becomes especially important when discussing PCS situations and previous VA-financed properties.
Can You Buy a Multi-Unit Property?
VA financing may potentially be used for certain properties containing multiple residential units when applicable VA requirements are satisfied and the Veteran intends to occupy one of the units as a home.
That's different from simply purchasing a non-owner-occupied investment property.
If you're considering this strategy, work with a lender familiar with VA property and occupancy requirements.
What Is a VA Appraisal?
Once you're under contract and using VA financing, the lender generally orders a VA appraisal through the VA appraisal process.
The VA appraisal serves important purposes involving:
VALUE
and
VA Minimum Property Requirements — MPRs
The appraiser evaluates whether the property meets applicable VA requirements and develops an opinion of value.
The VA Appraisal Is NOT a Home Inspection
I want this one in giant letters:
VA APPRAISAL ≠ HOME INSPECTION
The VA appraisal is not designed to replace a comprehensive home inspection performed for the buyer.
A home inspector may evaluate components such as:
Roof
HVAC
Plumbing
Electrical
Foundation
Appliances
and other systems and conditions.
A VA appraisal and buyer's inspection serve different purposes.
What Are VA Minimum Property Requirements?
VA Minimum Property Requirements are designed to help ensure properties securing VA-guaranteed loans meet applicable standards.
Issues can vary significantly by property.
Potential concerns might involve matters affecting things such as:
Safety
Sanitation
Structural soundness
and other VA requirements.
Don't try to predict the appraisal by walking around with a homemade VA checklist.
Let the professionals evaluate the property.
What If the VA Appraisal Comes in Low?
Suppose your contract price is:
$350,000
but the appraisal's value conclusion is lower.
That doesn't automatically mean:
“Deal over.”
The parties may have options depending on the contract and circumstances.
Those might involve:
Reviewing the appraisal
Negotiating
Changing financing/cash structure
or other contract-specific alternatives.
VA transactions also include protections relating to reasonable value.
Your Realtor and lender should walk you through the actual situation rather than assuming the outcome.
What Is the VA Escape Clause?
VA purchase transactions generally include language protecting the VA buyer from being obligated to complete the purchase solely because the agreed purchase price exceeds the property's VA-established reasonable value, subject to applicable rules and the agreement.
This is often referred to as the:
VA Escape Clause
or
VA Amendatory Clause.
It doesn't automatically cancel the contract.
And it doesn't prevent a Veteran from choosing to proceed under circumstances permitted by the contract and VA requirements.
Are VA Offers Weak?
This myth needs to die.
😂
A VA offer isn't automatically:
“weak.”
An offer should be evaluated based on its actual terms.
That includes things such as:
Price
Financing
Earnest money
Option period
Closing date
Requested concessions
and the buyer's financial position.
VA financing is simply one part of the offer.
Can the Seller Refuse a VA Offer?
A seller generally evaluates offers and decides which acceptable offer to pursue, subject to applicable laws.
A seller isn't automatically required to accept an offer because the buyer is using VA financing.
That's why presentation and offer strategy matter.
Our job is to build a competitive offer around:
Your goals + the property + current market conditions.
Can You Buy New Construction With VA?
Yes, potentially.
VA financing can be used with qualifying new construction when the borrower, lender, builder and property satisfy applicable requirements.
But there are different scenarios.
A completed builder inventory home
is different from:
A construction loan where the home is built from the ground up.
Not every lender offers every type of VA construction financing.
So if your goal is:
“I want to buy land and build my dream house using VA.”
start with a lender that actually handles that type of VA financing.
What About Quick Move-In Homes?
This can be a particularly useful category for San Antonio buyers.
A quick move-in or inventory home may already be:
Completed
or
Under construction.
That can give buyers some of the benefits of purchasing a new home without waiting for an entire build cycle.
Depending on the builder, home and financing, incentives may also be available.
Can VA Buyers Purchase Manufactured Homes?
VA financing may be available for qualifying manufactured homes and lots when applicable requirements are met.
But lender availability can be more limited.
Property requirements matter.
The home must satisfy the applicable VA and lender requirements.
So this is another area where:
Find the lender BEFORE finding the house
can save you a lot of frustration.
Can You Assume a VA Loan?
VA-backed loans may be assumable under applicable requirements and approval processes.
That can become particularly interesting when an existing VA loan has terms that are attractive compared with current financing.
But assumptions can involve important issues regarding:
Qualification
Remaining loan balance
Difference between loan balance and purchase price
and potentially the original Veteran's entitlement.
Never assume:
“VA loan = easy assumption.”
Understand the details first.
PCS Orders: What Happens to Your VA Loan?
This is a huge San Antonio topic.
Maybe you bought near:
Randolph
Lackland
or
Fort Sam Houston
and then orders arrive.
PCS orders do not automatically mean:
“You have to sell the house immediately.”
Depending on your situation, you may consider options such as:
Selling
or potentially
Keeping the property
subject to your financial, loan, insurance, tax and other considerations.
And if you want to buy at your next duty station using VA again, remaining entitlement may become important.
Buying Before You Arrive in San Antonio
Military buyers do this all the time.
You're stationed somewhere else.
Your PCS orders say:
SAN ANTONIO.
You may be able to handle much of the home-buying process remotely.
That can include:
Video tours
Virtual meetings
Electronic document signing
Lender coordination
Inspection review
and other remote processes.
The exact closing process depends on the transaction and title/lender requirements.
Don't Choose an Area Based Only on Distance From Base
San Antonio is spread out.
Five miles doesn't always mean:
“Five minutes.”
😂
If you're PCSing to JBSA, evaluate actual commute patterns along with:
Budget
Home type
Location preferences
Taxes
HOA
and your personal needs.
We can search around the duty station without pretending there's one universally “best” area.
VA Home-Buying Process: Step by Step
Here's the simplified roadmap.
STEP 1 — VERIFY ELIGIBILITY
🇺🇸 Obtain/review your COE.
STEP 2 — TALK TO A VA LENDER
🏦 Review financing and qualification.
STEP 3 — GET PRE-APPROVED
✅ Understand your potential budget and financing.
STEP 4 — BUILD THE HOME SEARCH
📍 Location + commute + payment + needs.
STEP 5 — TOUR HOMES
🏠 Resale and/or qualifying new construction.
STEP 6 — MAKE AN OFFER
📝 Negotiate the contract.
STEP 7 — INSPECTION & OPTION PERIOD
🔍 Evaluate the property and applicable deadlines.
STEP 8 — VA APPRAISAL
📊 Value + applicable VA property requirements.
STEP 9 — UNDERWRITING
🏦 Lender completes the loan approval process.
STEP 10 — FINAL WALK-THROUGH
👀 Confirm the property's condition as appropriate.
STEP 11 — CLOSING & FUNDING
✍️ Complete closing requirements.
STEP 12 — KEYS
🔑 Welcome home.
Before Closing: Don't Do Anything Financially Weird 😂
Once you're under contract:
Don't suddenly:
Finance a new truck
Open five credit cards
Finance furniture
Take out a personal loan
or make significant financial/employment changes without discussing them with your lender.
The lender may continue verifying information through closing.
Keep your finances boring.
And Protect Yourself From Wire Fraud
If you're wiring funds for closing:
VERIFY THE INSTRUCTIONS DIRECTLY WITH THE TITLE COMPANY.
Use trusted contact information.
Don't rely solely on an unexpected email.
If someone suddenly tells you:
“Our wiring instructions changed.”
Stop.
Verify independently before sending money.
The Biggest VA Loan Mistake?
Honestly?
It's not:
Choosing the wrong house.
It's often:
Never investigating the benefit at all.
Veterans sometimes rent for years because they assume:
They need a huge down payment.
Their credit isn't good enough.
They already used VA once.
or
VA financing is too difficult.
Maybe buying isn't right for you today.
But find out based on actual information.
Start With Three Things
If you're a Veteran or service member thinking about buying in San Antonio, start here:
🇺🇸 1. COE
🏦 2. VA-KNOWLEDGEABLE LENDER
🔑 3. REALTOR WHO UNDERSTANDS VA BUYERS
Then build the plan.
Using Your VA Benefit in San Antonio?
Let's figure out what your next move looks like.
🔑 Text KEY to 726.224.4727
Send me:
Your duty station or Veteran status
Your approximate timeline
and
Where around San Antonio you'd like to live.
Example:
“KEY — Veteran — 6 months — Northeast San Antonio.”
Or:
“KEY — PCS Randolph — November.”
We'll start there.
Follow @jaylopezrealtor for San Antonio VA homes, PCS information, new construction and home-buying education.
Buy a damn house. 🇺🇸🔑
Featured Image Concept
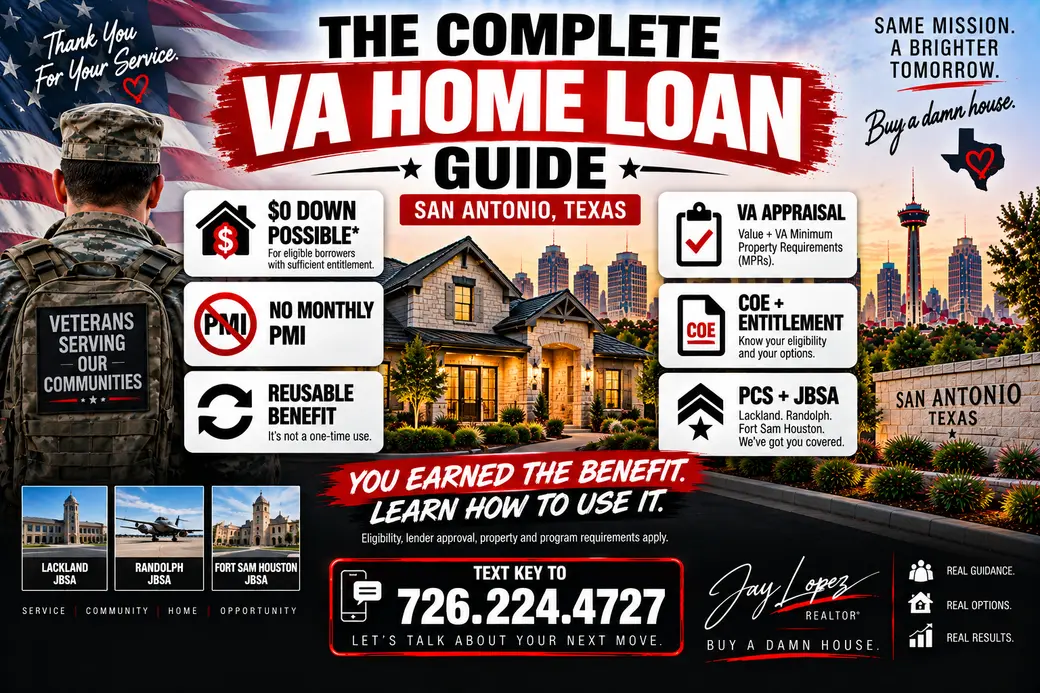
Since this begins our 25-blog VA/Military section, I'd make the image look like a major pillar-guide cover, almost like a military field manual meets modern real estate.
Main Headline
🇺🇸 THE COMPLETE VA HOME LOAN GUIDE
SAN ANTONIO, TEXAS
Large center visual:
VA HOME LOAN
surrounded by six strong benefit/education callouts:
$0 DOWN POSSIBLE*
For eligible borrowers with sufficient entitlement
NO MONTHLY PMI
REUSABLE BENEFIT
VA APPRAISAL
COE + ENTITLEMENT
PCS + JBSA
Small qualifier:
Eligibility, lender approval, property and program requirements apply.
Visual background: attractive San Antonio home with subtle military imagery—not combat imagery—with the San Antonio skyline/Tower of the Americas behind it and subtle references to JBSA / Lackland / Randolph / Fort Sam Houston.
Bottom:
YOU EARNED THE BENEFIT. LEARN HOW TO USE IT.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts