Can You Use Your VA Home Loan Benefit More Than Once?
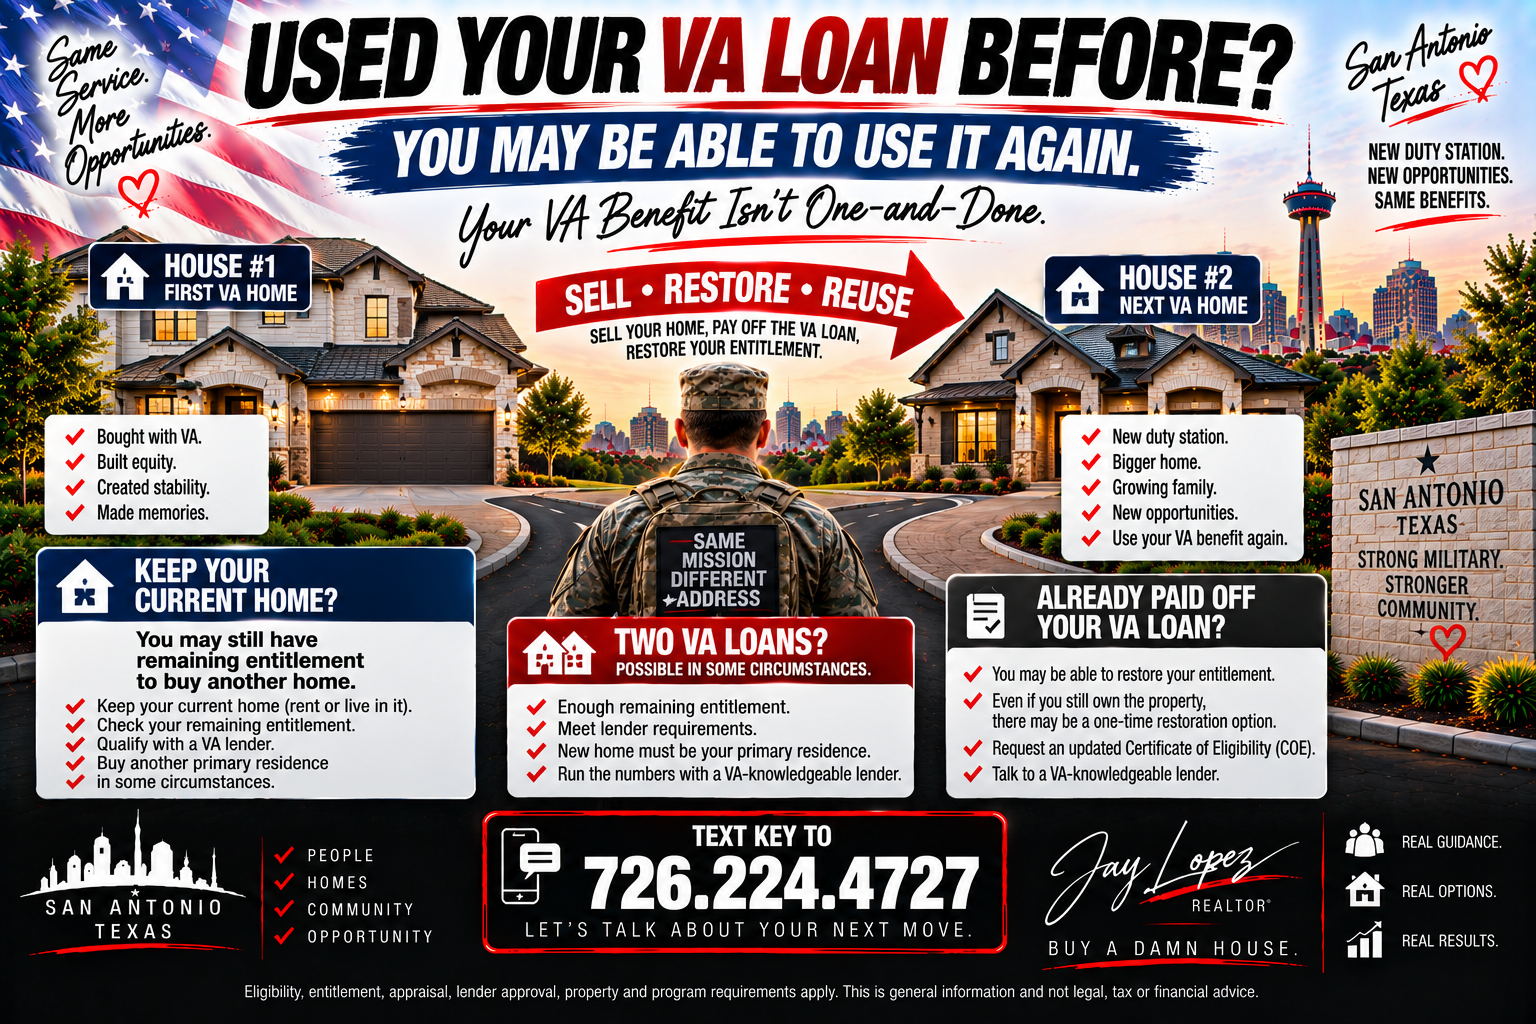
Here's one of the VA loan myths I hear all the time:
“I already used my VA loan, so I can't use it again.”
Good news.
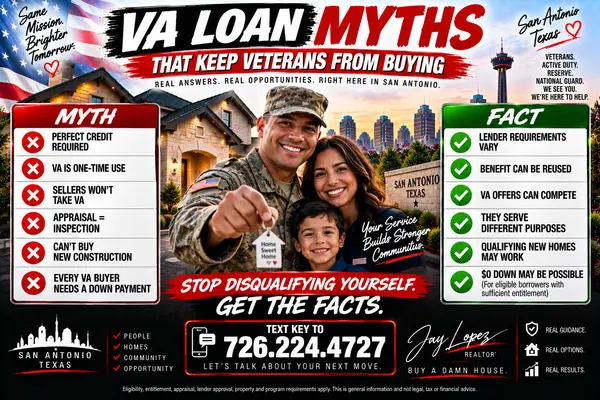
🇺🇸 THE VA HOME LOAN IS NOT A ONE-TIME BENEFIT.
VA specifically says there's no limit to the number of times you can use your VA home loan benefit, provided you continue to meet the applicable requirements.
That can be a huge deal for Veterans and military families.
Maybe you bought your first house years ago.
Maybe you're selling and moving.
Maybe you refinanced the old VA loan.
Maybe you've received PCS orders to San Antonio.
Maybe you want to keep your current house and buy another primary residence.
All of those situations lead us to one important word:
ENTITLEMENT.
Let's make it understandable.
First: Your VA Benefit Doesn't Expire After One Purchase
Using a VA-backed loan once doesn't mean you've burned your benefit.
Think of it less like a:
“ONE FREE VA LOAN” coupon
😂
and more like a benefit that can potentially be reused throughout your life.
VA recently reiterated that the home loan is a lifetime benefit and, in some circumstances, Veterans can even use remaining entitlement to purchase another primary residence while an existing VA-backed loan is still outstanding.
The question isn't:
“Have I used VA before?”
The better question is:
“How much entitlement do I currently have available?”
What Is VA Entitlement?
Your VA entitlement relates to the amount of guaranty VA provides to the lender.
It is not cash sitting in an account for you to withdraw.
Your:
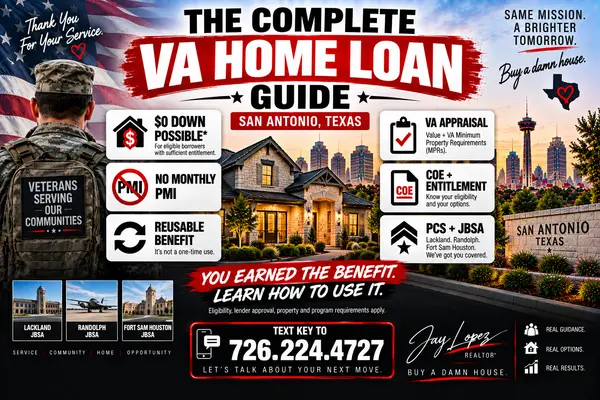
Certificate of Eligibility — COE
provides important entitlement information.
If you've previously used your VA benefit, your current COE becomes especially important because it can help show how much entitlement has already been charged.
Scenario #1: You Sell the House and Pay Off the VA Loan
This is probably the easiest scenario to understand.
Imagine:
You bought House #1 using VA.
Years later:
You sell House #1.
The VA-backed loan is paid in full.
You now want to buy House #2.
Under VA rules, previously used entitlement may be restored when the property securing the prior VA loan has been sold and the loan has been paid in full.
Once properly restored, you may be able to use the benefit again.
VA PURCHASE #1 → SELL → PAY OFF → RESTORE → VA PURCHASE #2
And potentially again later.
Wait...Is Restoration Automatic?
Don't assume it is.
VA provides a process for requesting an updated Certificate of Eligibility with restoration of entitlement.
A lender may be able to request the COE electronically for you, or you can request it yourself. VA also identifies VA Form 26-1880 as a method for requesting a COE/restoration.
So after selling your previous VA-financed home:
UPDATE YOUR COE.
Don't rely on what you remember from your last transaction.
Scenario #2: You Paid Off the VA Loan but Still Own the House
Now things get more interesting.
Maybe you bought a house with VA years ago.
Then you:
Paid the loan completely off
or perhaps refinanced the VA loan into another type of financing.
But:
You kept the property.
Can you restore that previously used entitlement?
Potentially.
VA provides for a one-time restoration when the prior VA loan has been paid in full but you haven't sold the property.
Notice the important words:
ONE TIME.
Example: Keeping Your First House
Imagine you bought a San Antonio house with VA.
Years later, you refinance that VA loan into conventional financing.
You still own the house.
Then you decide:
“I want to buy another primary residence using VA.”
The one-time restoration provision may potentially allow the entitlement previously tied to the first loan to be restored even though you still own the property.
But because this is a special one-time restoration, don't make assumptions about future entitlement.
Have VA and your lender evaluate the situation.
Scenario #3: You Still Have the Original VA Loan
Here's the one that surprises a lot of Veterans.
Suppose:
You own House #1.
House #1 still has a VA-backed mortgage.
And now:
You need to buy House #2 as your new primary residence.
Can you potentially use VA again?
YES, IN SOME CIRCUMSTANCES.
You may have what's called:
REMAINING ENTITLEMENT.
VA states that a borrower who hasn't restored all previously used entitlement may still have remaining entitlement available for another VA-backed loan.
This Is Especially Important for PCS Moves
Imagine you're stationed somewhere else.
You purchased a home using VA.
Then you receive orders:
PCS → JBSA SAN ANTONIO
Now you have a decision.
Do you:
Sell the old house?
or
Keep the old house and explore buying in San Antonio?
If you want to keep the old property, don't automatically assume:
“I can't use VA again because my entitlement is tied up.”
You may still have enough remaining entitlement for another purchase. VA published a September 2026 example specifically illustrating how a borrower can have two active VA-backed loans when enough remaining entitlement and other requirements are satisfied.
Yes—You Can Potentially Have Two VA Loans
This is worth putting in giant letters:
🇺🇸 TWO VA LOANS AT THE SAME TIME MAY BE POSSIBLE.
That does not mean everybody qualifies.
Several things still matter:
Remaining entitlement
Purchase price
Applicable county loan limit calculations
Income
Debts
Credit
Occupancy
and
Lender underwriting.
But the myth:
“One VA mortgage at a time. Period.”
is simply too broad.
What Does “Remaining Entitlement” Mean?
If some of your entitlement remains tied to an existing VA-backed loan, VA calculates how much guaranty may still be available.
When you don't have full entitlement, the applicable county loan limit becomes relevant to determining remaining bonus entitlement.
VA explains the general calculation as:
25% of the applicable county loan limit
minus
entitlement already used
equals
remaining bonus entitlement.
Your lender can use that information to determine how much VA guaranty remains available for another loan.
Don't Try to Become a VA Entitlement Mathematician at Midnight 😂
You can absolutely learn how the calculation works.
But there's a much easier starting point:
GET AN UPDATED COE.
Then have a VA-knowledgeable lender calculate your available entitlement for the specific county where you're considering buying.
Because:
Purchase price matters.
Existing entitlement matters.
Location can matter when entitlement isn't fully restored.
And your overall qualification matters.
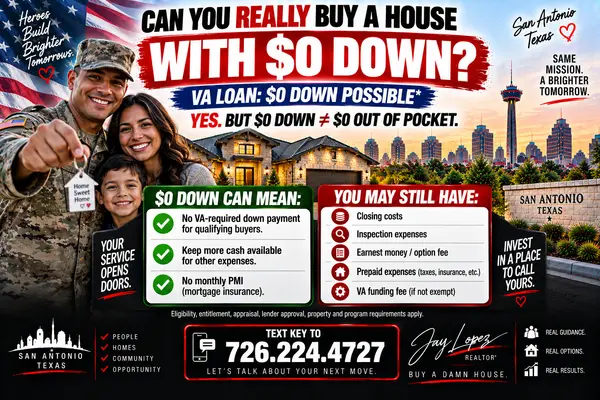
Does Remaining Entitlement Guarantee Another $0-Down Purchase?
No.
This is important.
You may have enough remaining entitlement to support another purchase without a down payment.
Or you may not.
VA explains that when remaining entitlement doesn't provide enough guaranty for the proposed loan, a lender may require a down payment.
So:
Second VA loan
doesn't automatically mean:
Second $0-down VA loan.
Run the actual calculation.
What If You Have Full Entitlement Again?
This is another important distinction.
VA says borrowers with full entitlement aren't subject to a VA loan limit based on the guaranty.
But that does NOT mean:
“Unlimited house!”
😂
Your lender still determines what you qualify to borrow based on factors including your income, debts, credit history and assets, and the property's appraisal must support the transaction.
What If Someone Assumes Your VA Loan?
Now we have another possibility.
VA loans can be assumable when applicable requirements are satisfied.
Suppose you sell your property and another qualified Veteran assumes your VA loan.
If that qualified Veteran substitutes their own entitlement for the entitlement you used, your entitlement may potentially be restored.
That substitution piece is extremely important.
Don't Assume Selling Through an Assumption Automatically Restores Your Entitlement
This can be a major misunderstanding.
If somebody assumes your VA loan, you need to understand:
What happens to YOUR entitlement?
An assumption and a substitution of entitlement are related issues but should not simply be treated as identical.
If you're selling a VA-financed property through an assumption and plan to use VA again:
Talk with your loan servicer, VA and appropriate professionals about the entitlement consequences before completing the transaction.
This is too important to guess about.
What About Foreclosure or a VA Claim?
Here's another situation where entitlement can become complicated.
If VA suffers a loss because it paid a guaranty claim, the entitlement associated with that loss may not simply become available again as though nothing happened.
VA guidance says a loss suffered by the government generally must be repaid before that entitlement can be restored.
If this applies to you:
Talk directly with VA.
Don't rely on a generic online entitlement calculator.
What About Occupancy?
Using VA again doesn't turn the benefit into an investment-property loan program.
VA purchase financing generally requires that you intend to occupy the new property as your residence.
VA specifically notes that its home loan benefit cannot simply be used to buy a vacation home or non-owner-occupied investment property.
So imagine:
You keep your previous home.
PCS to San Antonio.
Buy a San Antonio home using remaining entitlement.
The new home still needs to satisfy applicable VA occupancy requirements.
Can You Keep the Old House as a Rental?
Potentially, depending on your circumstances.
But there are multiple issues beyond simply asking:
“Will VA let me?”
You may need to evaluate:
Existing mortgage terms
Insurance
Property management
Taxes
Rental income treatment
Lender underwriting
Maintenance
and your overall financial risk.
Owning two properties isn't automatically a brilliant investment strategy.
It means:
You own two houses.
And houses occasionally decide they need expensive things.
😂
Two Houses = Two Sets of Responsibilities
Think beyond:
“Can I qualify?”
Ask:
“Do I actually want this?”
You could potentially have:
Two mortgage payments
Two insurance policies
Two sets of maintenance expenses
Two roofs
Two HVAC systems
and possibly:
Two tenants calling you when something breaks.
Qualification and good financial strategy aren't always the same thing.
Does Using VA Again Change the Funding Fee?
It can.
For borrowers who aren't exempt from the VA funding fee, whether the benefit is being used for the first time or a subsequent time can affect the applicable funding-fee percentage under current VA rules.
That's another reason your lender needs to know:
You've used VA before.
Don't compare financing based solely on interest rate.
Compare the entire loan structure and cash requirement.
Should You Use VA Again Just Because You Can?
Not necessarily.
Maybe VA is an excellent fit.
Maybe another financing option works better for your specific transaction.
Compare:
Estimated payment
Interest rate
Fees
Cash required
Mortgage insurance
Funding fee
and your broader financial plan.
The VA benefit is a tool.
A powerful one.
But:
THE GOAL ISN'T TO USE VA.
THE GOAL IS TO BUY THE RIGHT HOME WITH FINANCING THAT MAKES SENSE FOR YOU.
San Antonio Military Buyers: This Matters a Lot
With:
JBSA-Lackland
JBSA-Randolph
Fort Sam Houston
and the broader military community around San Antonio, we regularly have buyers who aren't purchasing their first home.
They may already own property from:
A previous duty station
A previous VA purchase
or
Earlier military service.
That's why the question:
“Have you ever used your VA loan before?”
shouldn't end the conversation.
It should start the entitlement conversation.
Your VA Reuse Checklist
If you've previously used VA and want to buy again:
🇺🇸 1. GET YOUR UPDATED COE
See what entitlement is currently shown.
🏠 2. IDENTIFY WHAT HAPPENED TO THE PREVIOUS PROPERTY
Sold?
Still own it?
Loan paid off?
VA loan still active?
Assumed by someone else?
💰 3. DETERMINE WHETHER ENTITLEMENT WAS RESTORED
Don't assume.
🧮 4. CALCULATE REMAINING ENTITLEMENT IF NEEDED
Have your lender run the actual numbers.
🏦 5. GET PRE-APPROVED
Entitlement isn't the same as mortgage qualification.
📍 6. CONFIRM THE NEW HOME FITS VA OCCUPANCY REQUIREMENTS
📊 7. COMPARE THE FULL FINANCING STRUCTURE
Then:
GO SHOPPING. 🔑
The Bottom Line
If somebody told you:
“You already used your VA loan. You can't use it again.”
send them this article.
😂
VA says the benefit can be used multiple times. You may be able to restore previously used entitlement, and in some circumstances you may even have enough remaining entitlement to purchase another primary residence while an existing VA-backed loan is still outstanding.
The answer depends on your specific situation.
So don't guess.
CHECK YOUR COE.
CHECK YOUR ENTITLEMENT.
RUN THE NUMBERS.
Then decide what makes sense.
Used Your VA Loan Before?
That doesn't mean you're finished.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
Whether you currently own a home
Whether that home has a VA loan
and
Your San Antonio timeline.
Example:
“KEY — Active Duty — VA home in Florida — PCS Randolph in January.”
We'll start there.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house. 🇺🇸🔑
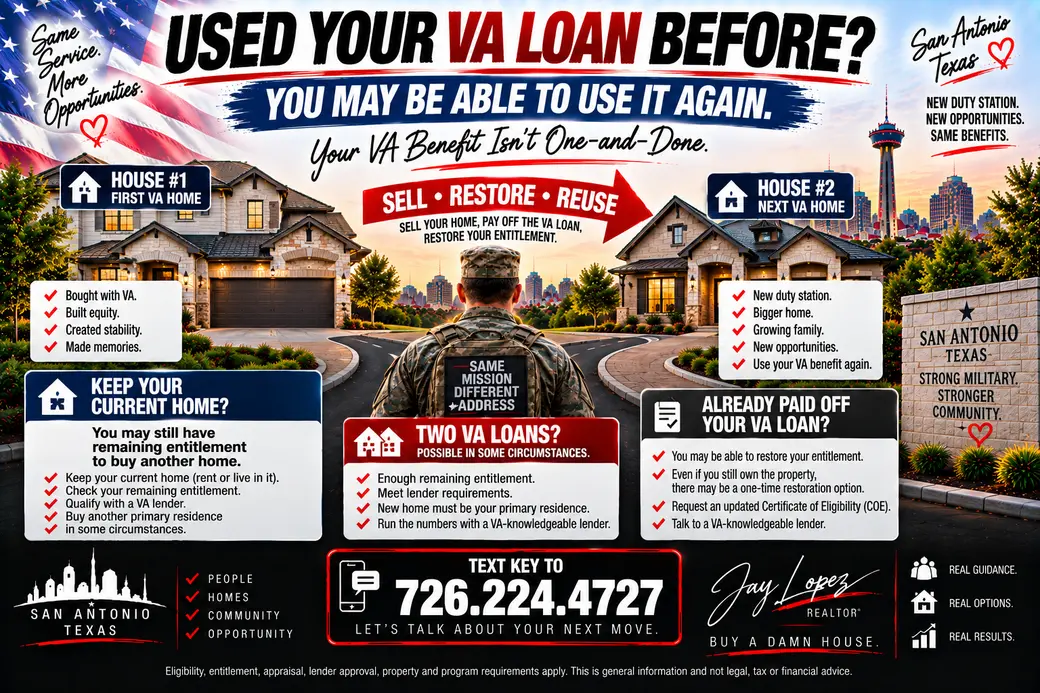
Featured Image Concept
This one should visually hammer home REUSE.
Main Headline:
🇺🇸 USED YOUR VA LOAN BEFORE?
Huge underneath:
YOU MAY BE ABLE TO USE IT AGAIN.
Center visual: Veteran standing between two homes.
HOUSE #1
FIRST VA HOME
Arrow:
SELL • RESTORE • REUSE
leading to:
HOUSE #2
NEXT VA HOME
Then a second pathway underneath:
KEEP HOUSE #1
⬇
REMAINING ENTITLEMENT?
⬇
HOUSE #2 MAY STILL BE POSSIBLE
Small callout:
TWO VA LOANS?
Possible in some circumstances.
Bottom:
YOUR VA BENEFIT ISN'T ONE-AND-DONE.
CHECK YOUR COE. CHECK YOUR ENTITLEMENT.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts