VA Loan Myths That Keep Veterans From Buying Homes
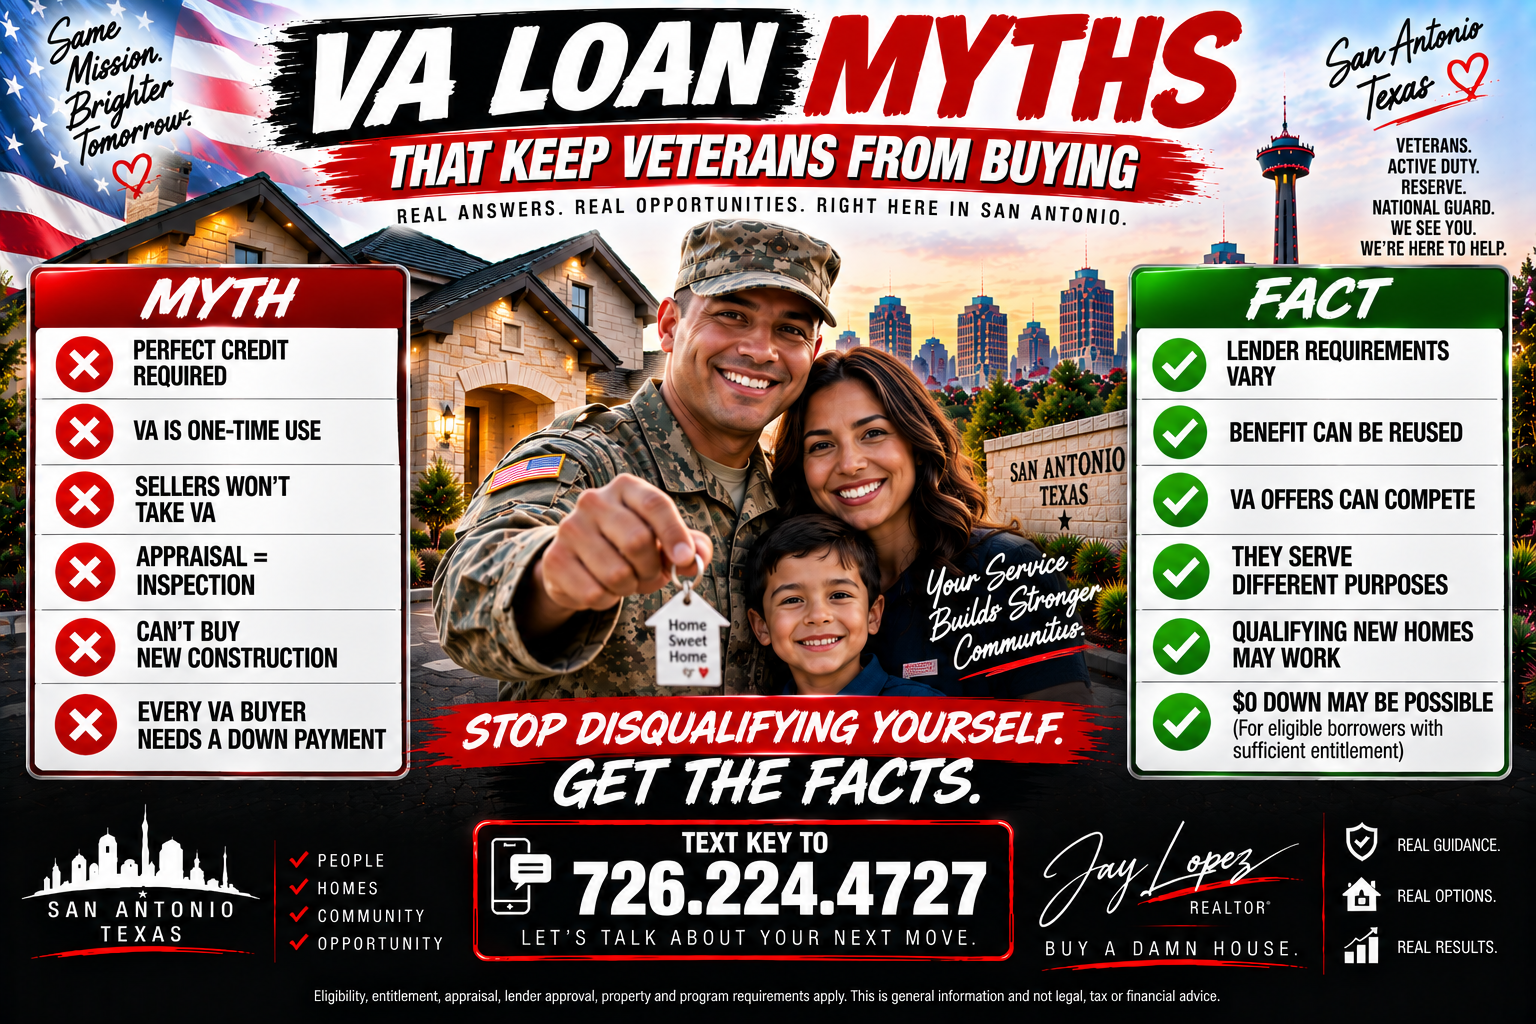
Veterans hear some wild things about VA loans.
“You need perfect credit.”
“You can only use VA once.”
“Sellers won't accept VA.”
“The appraisal is basically an inspection.”
“VA loans take forever.”
“You can't buy new construction.”
And one of my favorites:
“The VA loan is only for first-time buyers.”
Nope.
The problem with these myths isn't just that they're annoying.
They can cause Veterans and military families to eliminate themselves from homeownership before they've even explored their options.
So let's bust some myths.
🇺🇸 MYTH #1: You Need Perfect Credit for a VA Loan
❌ MYTH
The Department of Veterans Affairs does not establish one universal minimum credit score for VA-guaranteed loans.
But that doesn't mean:
“Credit doesn't matter.”
It does.
Private lenders make most VA loans, and lenders can establish their own underwriting requirements and credit standards.
So one lender may have requirements that differ from another.
The better question isn't:
“Is my credit good enough for VA?”
It's:
“What does a VA lender say about my specific financial profile?”
🇺🇸 MYTH #2: You Can Only Use Your VA Loan Once
❌ DEFINITELY A MYTH
The VA home loan benefit can potentially be used more than once.
Veterans may be able to restore their entitlement after certain circumstances, such as selling a property and paying off the associated VA-backed loan.
There are also situations where a Veteran may have remaining entitlement available while another VA-backed loan still exists.
That's particularly important for military households dealing with PCS moves.
So:
Used VA before?
Don't automatically assume you're done.
Check your entitlement.
🇺🇸 MYTH #3: VA Is Only for First-Time Home Buyers
❌ MYTH
You don't have to be a first-time buyer to use a VA-backed purchase loan.
You could potentially be:
Buying your first home
Selling and buying another
PCSing to another location
or
Using restored entitlement again later.
Eligibility and entitlement matter.
Whether you've owned a house before isn't what determines whether you're allowed to explore VA financing.
🇺🇸 MYTH #4: Every VA Buyer Gets $0 Down
This one needs a little nuance.
⚠️ SOMETIMES TRUE — BUT NOT AUTOMATIC
An eligible VA borrower with sufficient entitlement may potentially purchase with no down payment required by the VA loan program, provided the transaction meets applicable requirements.
But circumstances involving remaining entitlement or a purchase price above the appraised value can change the calculation.
And lender approval is still required.
So:
VA can offer $0-down financing.
But don't turn that into:
“Every Veteran can buy every house with no money down.”
Those aren't the same statement.
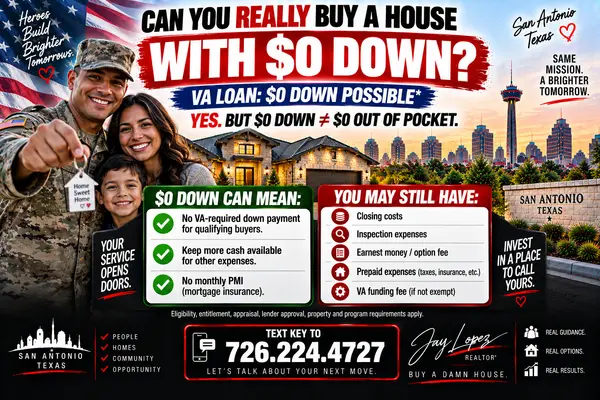
🇺🇸 MYTH #5: $0 Down Means You Need $0 to Buy
❌ MYTH
This one deserves repeating from Blog #27:
$0 DOWN ≠ $0 OUT OF POCKET
A qualifying buyer might not have a required mortgage down payment.
But the transaction can still involve expenses such as:
Earnest money
Option fee
Home inspection
Closing costs
Prepaid expenses
and other transaction-specific costs.
Seller assistance or builder incentives may potentially help with certain allowable costs when negotiated and permitted.
But don't start shopping assuming:
“I don't need a dollar.”
Know your numbers first.
🇺🇸 MYTH #6: VA Loans Always Have Mortgage Insurance
❌ MYTH
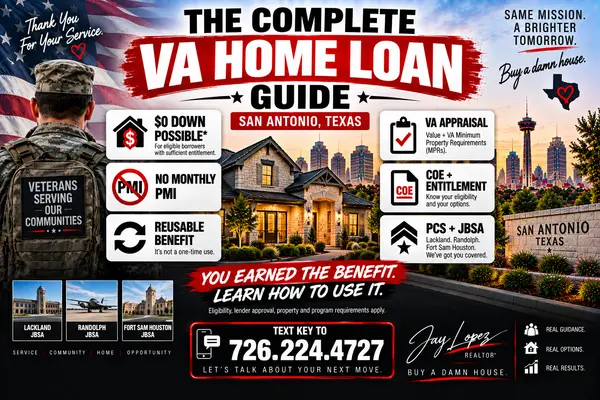
VA-backed purchase loans don't require monthly private mortgage insurance.
That's one of the program's significant features.
However, many VA borrowers may have a one-time:
VA FUNDING FEE
The funding fee is not the same thing as monthly PMI.
And certain eligible borrowers may be exempt from paying the funding fee.
🇺🇸 MYTH #7: Every Veteran Pays the VA Funding Fee
❌ MYTH
Some eligible borrowers are exempt.
Whether an exemption applies depends on VA requirements and the borrower's circumstances.
Instead of assuming:
“I'll have a funding fee.”
or:
“I'm a Veteran, so I'm exempt.”
have your actual status verified.
Your lender and Certificate of Eligibility can help determine how the funding fee applies to your transaction.
🇺🇸 MYTH #8: The VA Appraisal Is a Home Inspection
❌ BIG MYTH
I will keep saying this until every Veteran in San Antonio hears me:
VA APPRAISAL ≠ HOME INSPECTION
😂
The VA appraisal addresses the property's value and applicable VA Minimum Property Requirements.
A buyer's home inspection serves a different purpose.
A home inspector may evaluate numerous systems and components so you can better understand the property's condition.
One does not simply replace the other.
🇺🇸 MYTH #9: A House Has to Be Perfect to Pass the VA Appraisal
❌ MYTH
VA isn't requiring every house to look like it was built yesterday.
An older home can potentially qualify for VA financing.
What matters is whether the property satisfies applicable VA requirements.
There can be property-condition issues that need to be addressed.
But:
Older house ≠ automatically VA-ineligible.
If you're interested in the property, don't reject it simply because it isn't brand new.
🇺🇸 MYTH #10: VA Appraisals Always Come in Low
❌ MYTH
There's no rule saying:
“VA appraisals must be lower than the contract price.”
An appraiser develops an opinion of value based on the applicable appraisal process and market evidence.
Sometimes an appraisal supports the contract price.
Sometimes it doesn't.
That's true of appraisals generally.
The important thing is understanding what happens if there's a value issue rather than assuming one will occur.
🇺🇸 MYTH #11: Sellers Hate VA Loans
❌ WAY TOO BROAD
Some sellers or agents may have misconceptions about VA financing.
Others may have successfully completed plenty of VA transactions.
The financing type is only one component of an offer.
A seller may also evaluate:
Price
Closing date
Earnest money
Option terms
Requested concessions
Buyer qualification
and other negotiated terms.
Don't walk into a transaction believing:
“We're automatically the weak offer because I'm VA.”
Build the strongest offer that fits your goals and financial situation.
🇺🇸 MYTH #12: VA Buyers Can't Compete in Multiple-Offer Situations
❌ MYTH
VA financing doesn't automatically prevent a buyer from competing for a property.
The right strategy depends on the home and market conditions.
That could involve decisions about:
Price
Timing
Concessions
Option period
Earnest money
and other terms.
The goal isn't to make the most aggressive offer imaginable.
It's to make a strong offer you can actually live with.
🇺🇸 MYTH #13: VA Loans Take Forever to Close
❌ NOT INHERENTLY TRUE
There isn't one universal closing timeline for every VA purchase.
Timing depends on things like:
The lender
Borrower documentation
Appraisal
Property condition
Title work
Underwriting
and the contract.
A well-organized VA transaction with experienced professionals can move through the process efficiently.
But nobody should promise:
“Every VA loan closes in exactly ___ days.”
Every transaction is different.
🇺🇸 MYTH #14: VA Buyers Can't Buy New Construction
❌ MYTH
VA financing can potentially be used to purchase qualifying new construction.
That includes certain completed or quick move-in builder inventory homes when all applicable requirements are met.
And San Antonio has a lot of new construction.
Depending on the builder and current promotion, qualifying buyers may also find incentives such as:
Closing-cost assistance
Financing incentives
or
Rate buydowns.
Promotions change, so verify the actual offer.
🇺🇸 MYTH #15: You Can Use Any Builder and Any Lender for a VA Construction Loan
❌ NOT NECESSARILY
Buying a completed new-construction home and obtaining a true construction loan are different things.
If you're trying to:
Buy land + build from the ground up
you need to make sure your lender actually offers the type of VA construction financing you need and that the builder/property can satisfy applicable requirements.
Don't design the entire dream house first and ask about financing afterward.
Financing first. Dream house second.
🇺🇸 MYTH #16: VA Loans Are Only for Single-Family Houses
❌ MYTH
VA financing isn't necessarily limited to a traditional detached single-family home.
Certain other residential property types may potentially qualify when applicable VA and lender requirements are satisfied.
That can include some:
Condominiums
Manufactured homes
and
Multi-unit residential properties
depending on the property and financing.
Property eligibility can get technical.
Verify before falling in love with the listing.
🇺🇸 MYTH #17: You Can't Buy a Condo With VA
❌ MYTH
VA financing may potentially be used for an eligible condominium.
However, condominium approval requirements can matter.
So don't assume:
“It's a condo, VA won't work.”
And don't assume the opposite:
“Every condo qualifies.”
Have the property checked.
🇺🇸 MYTH #18: You Can't Buy a Manufactured Home With VA
❌ MYTH
VA financing may potentially be available for qualifying manufactured homes and lots.
But lender availability and property requirements can make these transactions different from purchasing a typical site-built home.
If this is your goal:
Find the right lender early.
🇺🇸 MYTH #19: You Can't Have Two VA Loans
❌ NOT ALWAYS TRUE
There are circumstances where a borrower can potentially have more than one VA-backed loan at the same time.
This can become relevant when a service member:
Owns a VA-financed property
then
PCSs to another duty station
and wants to purchase another primary residence.
The key question becomes:
How much entitlement remains?
Qualification, occupancy, entitlement and lender requirements still matter.
🇺🇸 MYTH #20: PCS Orders Mean You Have to Sell Your VA-Financed House
❌ MYTH
Receiving PCS orders doesn't automatically require you to sell the property.
Depending on your circumstances, there may be different options to evaluate.
Those decisions can involve:
Financing
Occupancy
Entitlement
Insurance
Taxes
Property management
and your financial goals.
This is an area where you want individualized professional guidance rather than barracks-room financial advice.
😂
🇺🇸 MYTH #21: You Can't Buy Until You Physically Arrive in San Antonio
❌ MYTH
Military buyers frequently begin the process before arriving.
Depending on the transaction, we can potentially use:
Video tours
Virtual meetings
Electronic signatures
Remote lender communication
and other tools to help manage a purchase from another location.
You don't necessarily have to land at SAT with your luggage and start house hunting the next morning.
🇺🇸 MYTH #22: You Need a Huge Amount of Savings Before Talking to Anyone
❌ MYTH
Maybe you need more savings before you're ready to buy.
Maybe you don't.
The point is:
You don't know until you run the numbers.
Talk to a lender.
Learn:
Your potential financing
Estimated cash requirements
Estimated payment
and
What, if anything, you should work on.
Then decide.
🇺🇸 MYTH #23: Talking to a Lender Means You Have to Buy
❌ ABSOLUTELY NOT
Talking to a lender means:
You're getting information.
That's it.
Maybe you're ready now.
Maybe you're six months away.
Maybe buying isn't right for you.
A good conversation should give you clarity.
Not pressure.
🇺🇸 MYTH #24: Your BAH Determines How Much House You Can Buy
❌ MYTH
Your Basic Allowance for Housing may be part of your overall financial picture, but:
BAH is not a home-price calculator.
Don't say:
“My BAH is $2,300, therefore I should buy a house with a $2,300 payment.”
Your housing budget should consider your broader finances, debts, expenses, savings and goals.
And your lender determines mortgage qualification based on applicable underwriting requirements.
🇺🇸 MYTH #25: If You're Eligible for VA, You Should Automatically Buy
❌ MYTH
This may be the most important one.
VA eligibility gives you an option.
It doesn't mean buying is automatically the right decision.
If you're:
Moving again soon
Financially stretched
Not ready for maintenance
or simply
Prefer renting right now
then renting may make sense.
The goal isn't:
USE VA AT ALL COSTS.
The goal is:
UNDERSTAND THE BENEFIT AND MAKE AN INFORMED DECISION.
Stop Disqualifying Yourself Based on Something You Heard
This is what drives me crazy.
A Veteran says:
“I can't buy because my credit isn't 700.”
Who told you that?
“My buddy said VA loans only work once.”
Who told your buddy?
“Sellers won't take VA.”
Which seller?
“VA houses have to be perfect.”
According to whom?
😂
There is an incredible amount of secondhand VA loan information floating around.
Some of it is outdated.
Some of it applies to one lender.
Some of it applies to one transaction.
And some of it is simply wrong.
Get Your Information From the Right People
Your home-buying team may include:
🏦 A VA-knowledgeable lender
For financing and qualification.
🔑 A Realtor familiar with VA transactions
For property search, offers and transaction strategy.
🏠 A qualified inspector
For property-condition information.
📑 A title company
For title and closing.
And when you need authoritative information about the benefit itself:
🇺🇸 The U.S. Department of Veterans Affairs.
The VA Benefit Isn't Magic
Let's also be realistic.
A VA loan doesn't mean:
Guaranteed approval.
It doesn't mean:
Every property qualifies.
It doesn't mean:
Every offer gets accepted.
It doesn't mean:
You'll never spend money.
And it doesn't mean:
Buying is automatically better than renting.
What it does provide is a powerful financing option for eligible borrowers.
Learn how it actually works before deciding whether to use it.
Think a VA Loan Myth Is Keeping You From Buying?
Let's find out.
🔑 Text KEY to 726.224.4727
Send me:
Veteran / Active Duty
What you've heard about VA
and
Your approximate buying timeline.
Example:
“KEY — Veteran — I was told my credit is too low — 6 months.”
We'll start with facts instead of assumptions.
Follow @jaylopezrealtor for San Antonio VA home-buying education, PCS information, new construction and military real estate.
Buy a damn house. 🇺🇸🔑
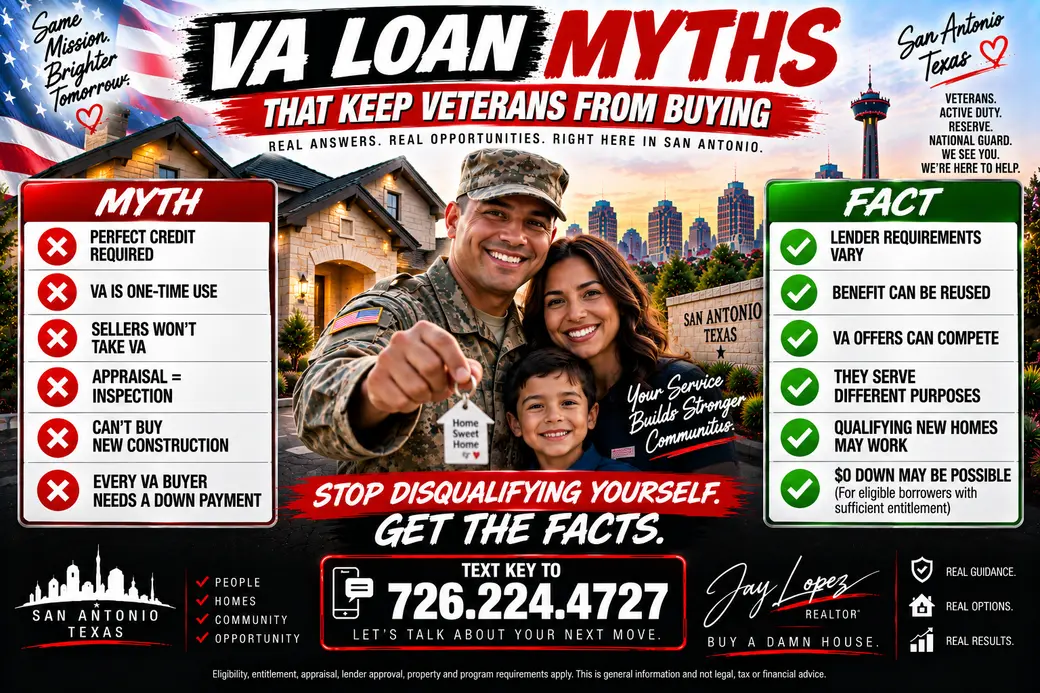
Featured Image Concept
This one should be a big MYTH vs. FACT graphic.
Main Headline:
🇺🇸 VA LOAN MYTHS
THAT KEEP VETERANS FROM BUYING
Center:
MYTH ❌ / FACT ✅
Use 6 short examples:
❌ PERFECT CREDIT REQUIRED
✅ LENDER REQUIREMENTS VARY
❌ VA IS ONE-TIME USE
✅ BENEFIT CAN BE REUSED
❌ SELLERS WON'T TAKE VA
✅ VA OFFERS CAN COMPETE
❌ APPRAISAL = INSPECTION
✅ THEY SERVE DIFFERENT PURPOSES
❌ CAN'T BUY NEW CONSTRUCTION
✅ QUALIFYING NEW HOMES MAY WORK
❌ EVERY VA BUYER NEEDS A DOWN PAYMENT
✅ $0 DOWN MAY BE POSSIBLE
Center visual: confident Veteran/military household holding house keys in front of a modern San Antonio home. San Antonio skyline and Tower of the Americas behind them.
Bottom:
STOP DISQUALIFYING YOURSELF. GET THE FACTS.
TEXT KEY — 726.224.4727
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts