How Much House Can I Afford in San Antonio?
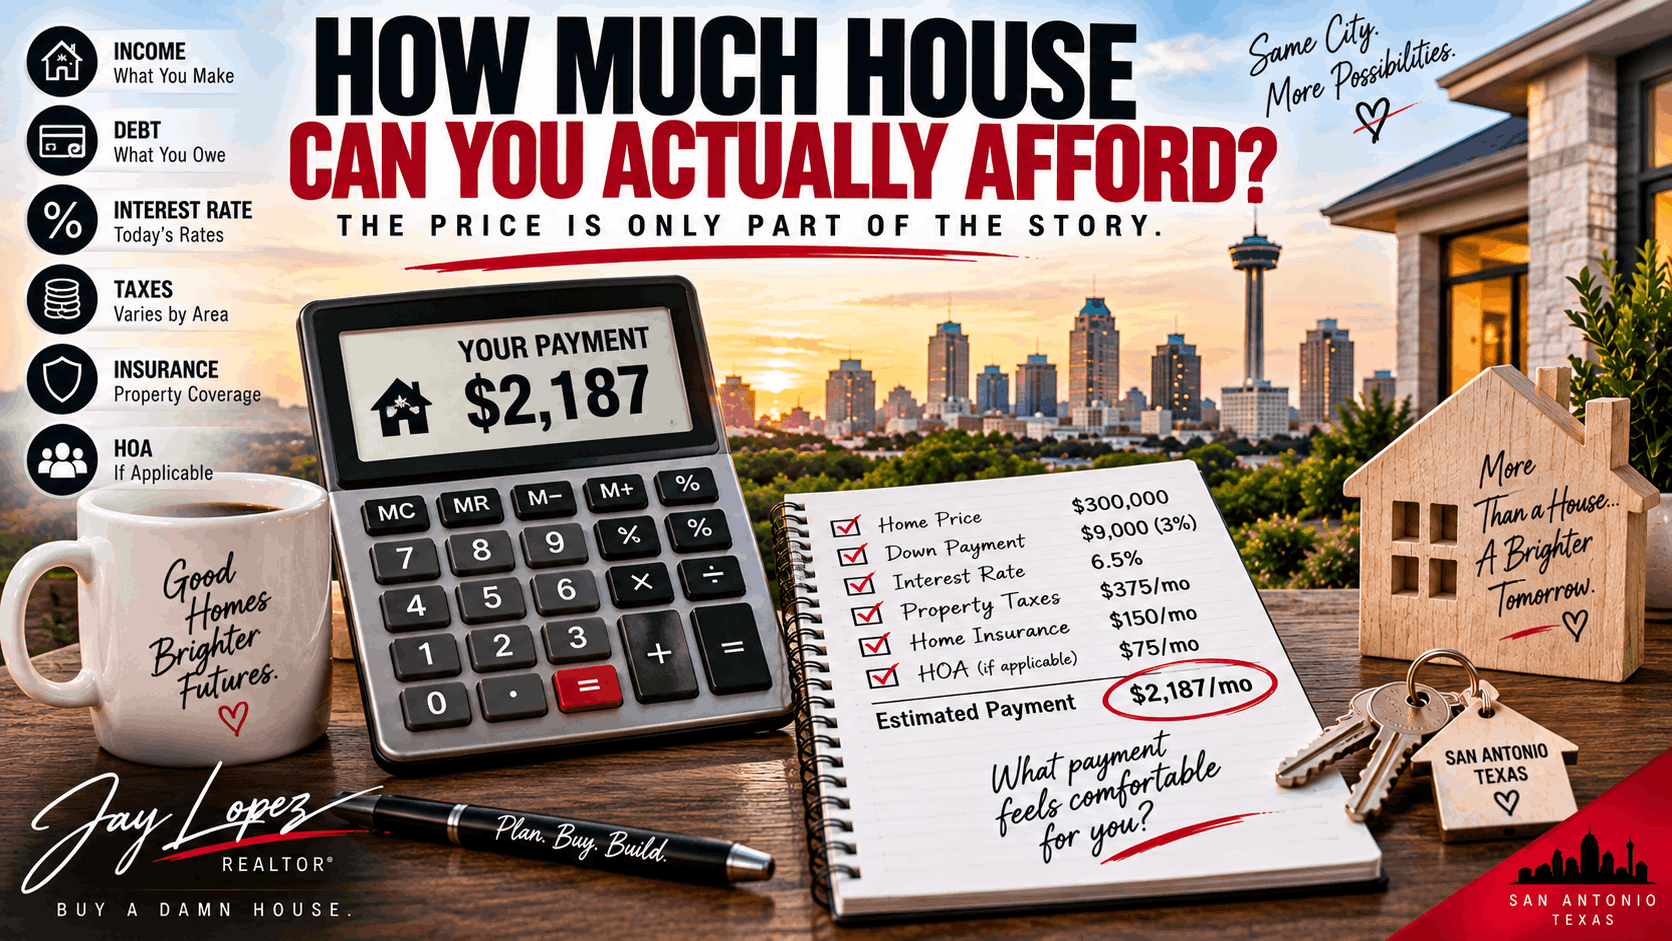
If you're thinking about buying a house, you've probably done this at least once:
Open a real estate app.
Set the maximum price to $300,000.
Look around.
Change it to $350,000.
Look around some more.
Then quietly change it to $400,000 because that kitchen was really nice. 😂
There's just one problem.
The price of the house doesn't tell you whether you can comfortably afford it.
When I work with buyers in San Antonio, I'm much more interested in another number:
What monthly housing payment are you comfortable with?
Because qualifying for a certain loan amount and actually wanting that payment coming out of your bank account every month are two different things.
Let's break down what can determine how much house you may be able to afford.
1. Start With Your Monthly Payment
Most buyers begin with:
“I want a $350,000 house.”
I'd rather start with:
“I want my housing payment around $____ per month.”
Why?
Because your purchase price is only one piece of the puzzle.
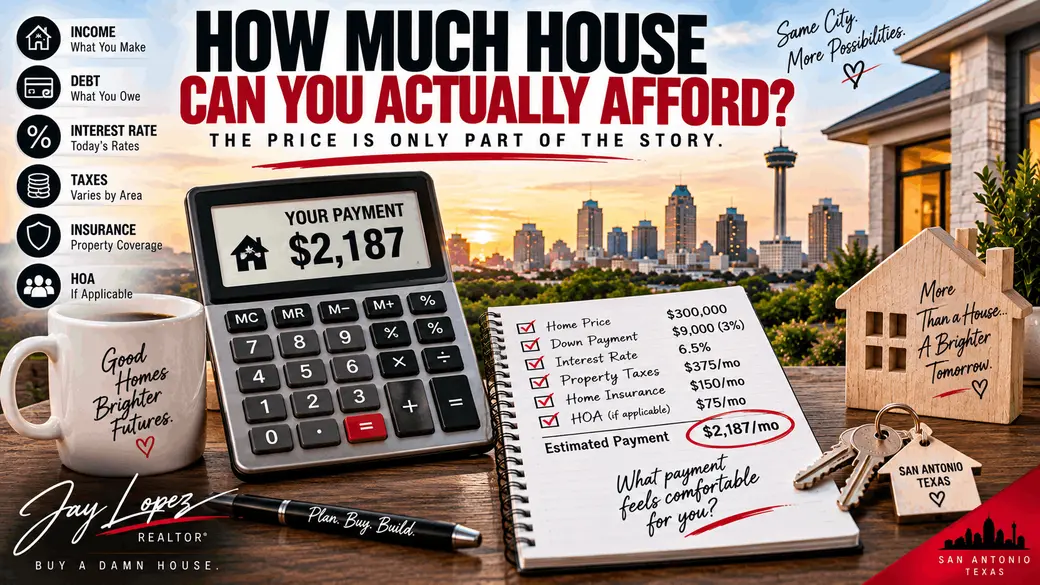
Depending on your financing and property, your monthly housing expense may include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- HOA dues or assessments
- Other property-related expenses
That's why two houses with exactly the same price can potentially have different monthly costs.
Don't shop only by price. Shop by the whole financial picture.
2. Your Income Matters
Your lender will look at your income when determining how much financing you may qualify for.
But lenders don't simply look at your salary and say:
“Great. Here's your house.”
They'll generally evaluate documented qualifying income along with other parts of your financial profile.
Depending on your situation, income could include wages, salary, certain self-employment income, or other qualifying sources that meet lender and loan-program requirements.
Your lender determines what income can actually be used for qualification.
3. Your Existing Debt Matters Too
Your income is only one side of the equation.
The other side is the debt you're already paying.
That could include things such as:
Car payments
Student loans
Credit cards
Personal loans
Other mortgage obligations
Certain recurring debts
Lenders commonly evaluate your debt-to-income ratio, often called DTI.
In simplified terms, it compares certain monthly debt obligations with your qualifying monthly income.
Different loan programs and lenders may have different requirements.
That's why your coworker who earns roughly the same amount as you may qualify for a completely different mortgage amount.
4. Your Down Payment Can Change the Numbers
The amount you put down can affect your financing.
A larger down payment generally means you're borrowing less.
Depending on the loan, it can also affect things such as mortgage insurance and other financing costs.
But remember what we discussed in Blog #4:
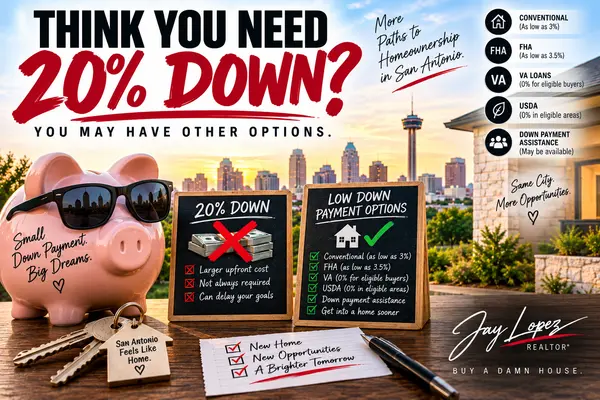
You don't necessarily need 20% down.
Qualified borrowers may have conventional, FHA, VA, USDA or other financing options with smaller down-payment requirements.
The right question isn't:
“What's the smallest amount I can put down?”
It's:
“Which financing structure makes sense for my situation?”
5. Interest Rates Matter
Interest rates can significantly affect affordability.
If the interest rate changes while the home price stays exactly the same, the principal-and-interest portion of the payment changes.
That's why buyers shouldn't assume:
“If rates drop, I'll automatically be able to afford more.”
Maybe.
But home prices, inventory, taxes, insurance and other variables may also change.
Instead of trying to perfectly predict future rates, ask your lender:
“What does buying look like with today's numbers?”
Then decide whether those numbers work for you.
6. Property Taxes Matter in San Antonio
This is particularly important when comparing homes around the San Antonio area.
Property tax obligations can vary based on the property, taxing jurisdictions, applicable exemptions and other factors.
That means two similarly priced houses can have different estimated tax expenses.
And that can change the monthly housing payment.
This becomes especially important when you're comparing:
Different neighborhoods
Different municipalities
New construction communities
Homes with different taxing jurisdictions
Don't look at the purchase price alone.
Ask about the estimated total monthly payment for the specific property you're considering.
7. Homeowners Insurance Matters
Insurance is another cost buyers sometimes underestimate.
Your homeowners insurance premium can be affected by multiple factors involving the property and coverage.
The cost isn't necessarily identical from one house to another.
When you're getting serious about a particular property, obtain actual insurance quotes rather than relying entirely on a generic online estimate.
A $50 or $100 difference here and there starts to matter when you're building a monthly budget.
8. Don't Forget the HOA
Some San Antonio-area communities have homeowners associations.
If the property has an HOA, those dues should be part of your affordability calculation.
The amount and frequency vary by community.
You also want to understand what the HOA provides and review the applicable documents as part of your transaction.
Again:
House price ≠ total cost of owning the house.
9. Mortgage Insurance May Affect Your Payment
Depending on your loan program, down payment and other factors, mortgage insurance may be part of your payment or financing costs.
The rules aren't identical across every loan program.
For example, conventional mortgage insurance works differently from FHA mortgage insurance, and VA-backed loans have their own structure.
Your lender should show you how the specific financing you're considering affects both:
Cash needed upfront
and
Monthly payment
10. What Does Your Lifestyle Cost?
This part doesn't show up on a mortgage application the same way it shows up in your actual life.
Maybe you love traveling.
Maybe you eat out frequently.
Maybe you have expensive hobbies.
Maybe you want money available for retirement.
Maybe you have family obligations.
Maybe you just don't want your entire paycheck disappearing into your house.
That's important.
If a lender says you qualify for a certain amount, you don't have to spend every dollar you're qualified to borrow.
Being approved for it doesn't automatically mean you'll be comfortable with it.
I want you to own your house.
I don't want your house to own you.
11. Don't Forget Maintenance
Renters can call the landlord when something breaks.
Homeowners usually get to meet the repair bill personally. 😂
You should have room in your budget for maintaining the property.
Eventually:
The air conditioner needs attention.
The water heater gets older.
Something leaks.
Something breaks.
The yard needs work.
The house decides it would like some of your money.
That's homeownership.
Having financial reserves can make those moments a lot less stressful.
12. What Does $300,000 vs. $400,000 Actually Mean?
Let's say you're deciding between homes at different price points.
It isn't enough to say:
“That's only $50,000 more.”
The difference can affect:
- Loan amount
- Down payment
- Principal and interest
- Property taxes
- Insurance
- Mortgage insurance
- Cash needed at closing
Instead of comparing price tags, ask your lender for payment scenarios.
For example:
What does approximately $300,000 look like?
What does approximately $350,000 look like?
What does approximately $400,000 look like?
Then decide where your comfort zone is.
13. Online Mortgage Calculators Are a Starting Point — Not the Final Answer
Mortgage calculators can be useful.
I use numbers all the time when helping buyers understand possibilities.
But don't mistake a generic calculator for an actual loan estimate.
Online calculators may use assumptions for:
Interest rates
Taxes
Insurance
Mortgage insurance
HOA
and other costs.
Those assumptions may not match the property you're considering.
Use calculators to learn.
Use your lender's actual numbers to make decisions.
14. Your Maximum Approval Isn't Necessarily Your Shopping Budget
Let's say your lender tells you that you qualify up to a particular amount.
You don't automatically have to shop at that maximum.
You might decide:
“I qualify up to $425,000, but I feel much better around $350,000.”
Great.
Now I know where to search.
We can focus on homes that fit your financial comfort level rather than constantly trying to push you to the top of your approval.
That's how I want the relationship to work.
15. What If the Homes in Your Budget Aren't What You Expected?
Then we adjust.
Maybe we change:
Location
Square footage
Age of the home
Lot size
Bedroom count
New construction vs. resale
Features
Commute
Real estate is usually a series of trade-offs.
Maybe moving 15 minutes farther out gets you another bedroom.
Maybe giving up the giant backyard keeps the payment comfortable.
Maybe new construction has an incentive worth evaluating.
Maybe a resale property gives you more house for your particular budget.
That's where knowing the San Antonio market becomes valuable.
So…How Much House Can You Afford?
Here's the answer:
I can't tell you from a blog.
And anybody who gives you an exact number without understanding your finances probably shouldn't be giving you that number either.
But we can help you figure it out.
Start with three questions:
1. What are you currently paying for housing?
2. What monthly housing payment would you feel comfortable with?
3. How much money do you currently have available for the purchase while keeping appropriate reserves?
Then talk with a qualified lender.
Once we know the financing parameters, I can help you see what those numbers may actually buy around San Antonio.
Now we're not guessing.
We're shopping with a game plan.
Let's Find Your Comfortable Number
If you've been scrolling through homes wondering:
“Can I actually afford this?”
Let's find out.
Maybe your budget gets you more house than you expected.
Maybe we need to adjust the location.
Maybe you're not quite ready.
Maybe you're ready right now.
There's only one way to know.
🔑 Text KEY to 726.224.4727
Send me:
1. Your comfortable monthly housing payment
2. The San Antonio area you're interested in
3. Whether you're renting now
We'll start there.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts