5 Signs You May Be Ready to Stop Renting
Every year, the same thing happens.
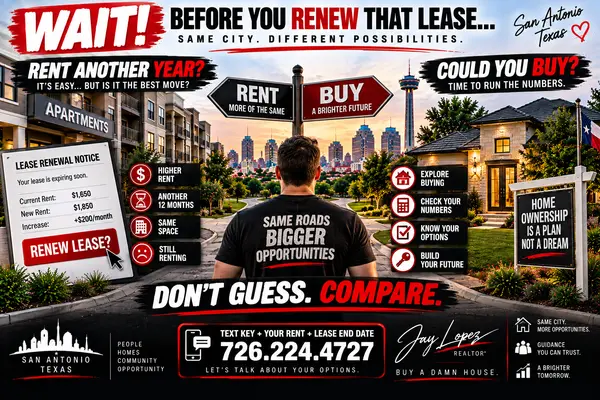
Your lease renewal shows up.
You look at the new rent.
You make the face.
😑
Then you sign another lease.
Not necessarily because renting is your best option.
Sometimes it's simply because:
You never checked whether buying was an option.
Now, I'm not going to tell every renter in San Antonio:
“YOU NEED TO BUY A HOUSE RIGHT NOW!”
That's ridiculous.
Renting can absolutely make sense.
But there comes a point when some renters should at least run the numbers.
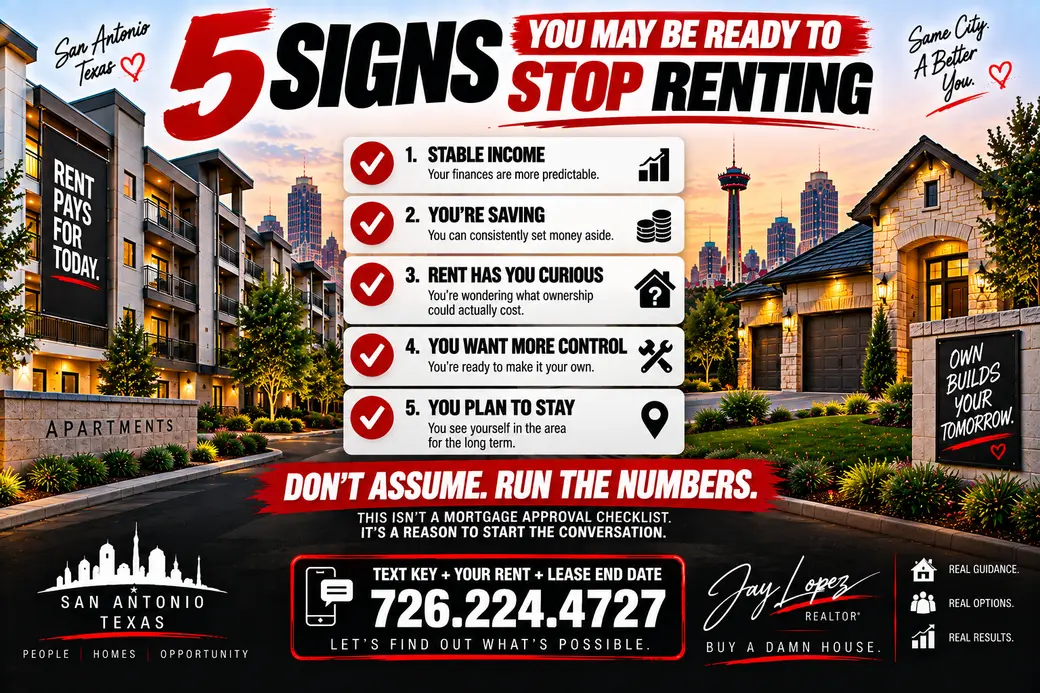
Here are five signs you may have reached that point.
Sign #1: Your Income Has Become More Stable
Think about where you were a few years ago.
Maybe you were:
Starting your career
Changing jobs
Finishing school
Getting out of the military
Moving frequently
or simply figuring life out.
Buying a house probably wasn't high on the priority list.
But things change.
Maybe now you've had stable employment and income for a while.
You're paying your bills.
You've established a routine.
And you're starting to think:
“I'm probably going to be here for a while.”
That's worth paying attention to.
Stable Doesn't Mean Perfect
You don't need to have your entire life mapped out until retirement.
😂
Mortgage qualification depends on your specific income, employment, credit, debt and financing situation.
But if your finances have become more predictable, it may be worth having a conversation with a lender.
Not because you're definitely buying.
Because you want to know what's possible.
Sign #2: You're Saving Money Consistently
Here's another big one.
After:
Rent
Utilities
Car payment
Groceries
Insurance
Entertainment
and everything else...
Is there money left?
And are you consistently saving some of it?
That's important.
Homeownership requires more than making the monthly payment.
Depending on the transaction, buyers may need money for:
Down payment
Closing costs
Prepaid expenses
Earnest money
Option fee
Inspection
Moving
and other expenses.
And after closing?
You still want emergency reserves.
Your Savings Account Should Survive Closing Day 😂
Buying a home and having:
$14.72 left in checking
isn't the goal.
A house needs maintenance.
Appliances eventually break.
Things happen.
So if you're starting to consistently save money and build reserves, that's one indication you may be moving toward homeownership readiness.
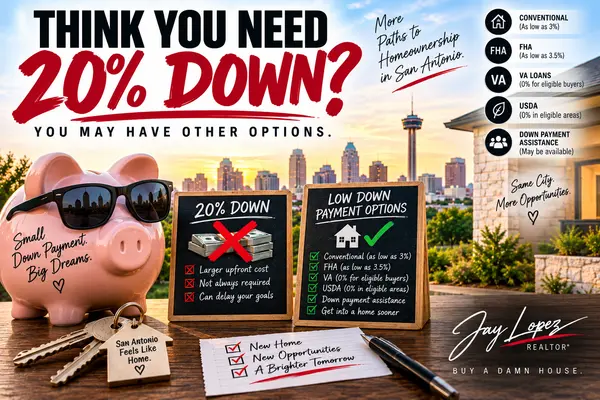
But What If You Don't Have 20% Down?
Good news.
You may not need it.
The idea that every buyer must put 20% down is one of the biggest misconceptions in real estate.
Depending on eligibility and lender requirements, buyers may have access to financing such as:
Conventional
FHA
VA
USDA
and potentially qualifying assistance programs.
Some conventional options can allow relatively low down payments for qualified borrowers.
FHA financing may allow a 3.5% down payment for borrowers meeting applicable requirements.
Eligible VA borrowers with sufficient entitlement may potentially purchase with no down payment required by the VA loan program.
So don't decide you're five years away simply because you haven't saved 20%.
Find out what applies to you.
Sign #3: Your Rent Is Starting to Make You Curious
Notice what I didn't say.
I didn't say:
“Renting is throwing money away.”
It isn't.
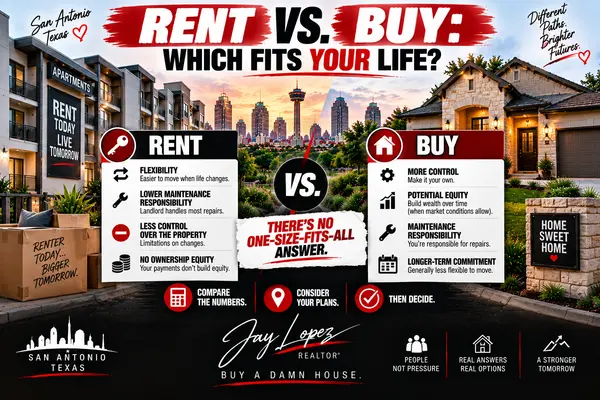
You're paying for somewhere to live.
You're also getting flexibility and avoiding many ownership responsibilities.
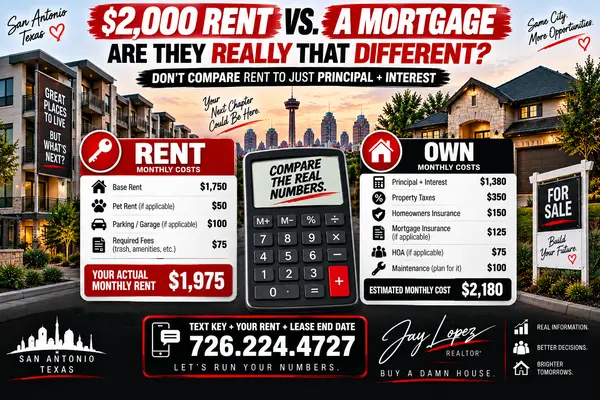
But let's say you're currently spending:
$1,900 per month
between rent and recurring rental fees.
That's:
$22,800 per year.
It doesn't automatically mean you could own a comparable home for the same monthly amount.
But it absolutely gives us a reason to ask:
“What would owning actually cost me?”
Compare the REAL Numbers
Don't compare:
$1,900 rent
to
$1,900 principal and interest.
That's not an apples-to-apples comparison.
Depending on the home and financing, ownership costs may include:
Principal
Interest
Property taxes
Homeowners insurance
Mortgage insurance, when applicable
HOA fees, when applicable
plus maintenance and repairs.
We want the real estimated monthly cost.
Then compare it with what you're spending now.
What If Owning Costs More?
Maybe it does.
Then we ask:
Is the difference comfortable?
Does ownership fit your longer-term plans?
Do you have adequate savings?
Do the responsibilities of owning make sense for you?
And maybe the answer is:
“No. Renting still works better.”
That's fine.
Now you've made an informed decision instead of assuming.
Sign #4: You Want More Control Over Where You Live
Maybe you're tired of asking:
“Can I paint this wall?”
“Can I have another dog?”
“Can I change this?”
“Can I install that?”
“Why did my rent go up again?”
😂
One attraction of homeownership is having more control over your living space, subject of course to laws, deed restrictions, HOA rules and other property-specific limitations.
Want to paint the bedroom?
Go for it.
Want to create a home office?
Great.
Want to spend an entire weekend building something in the backyard and then wonder why you started?
Welcome to homeownership. 😂
You're Also Accepting Responsibility
Control comes with responsibility.
When you're renting and the water heater dies?
You call the landlord.
When you own the house?
Congratulations.
You ARE the landlord.
Homeowners need to plan for:
Repairs
Maintenance
Insurance
Taxes
and unexpected expenses.
If you're comfortable taking on those responsibilities, that's another sign ownership may fit where you are in life.
Sign #5: You Expect to Stay in the Area
This one matters.
Buying and selling real estate involves transaction costs.
Home values can move up or down.
There's no guarantee that buying a house today means you'll make money selling it next year.
So if you know:
“I'm probably leaving San Antonio in nine months.”
renting may offer valuable flexibility.
But if you're thinking:
“I could see myself staying here for several years.”
then buying may deserve a closer look.
Military Buyers: Your Situation Is Different
San Antonio is Military City USA.
And military buyers have another factor:
PCS orders.
You might want to own but also know another move could eventually happen.
That doesn't automatically mean buying is wrong.
But your expected timeline deserves serious consideration.
Ask:
How long might I realistically be here?
What happens if I PCS?
Would I sell?
Would keeping the property ever make sense for my circumstances?
How does my VA entitlement work?
Those questions should be part of the decision.
Bonus Sign: You're Constantly Looking at Houses Anyway 😂
You know who you are.
You're sitting on the couch at 11:47 p.m.
Your spouse asks:
“What are you doing?”
And you respond:
“Nothing.”
Meanwhile you've looked at:
37 houses
6 new construction communities
and
a property 45 minutes away because the kitchen looked cool.
😂
At some point...
Maybe stop browsing imaginary houses.
And find out what you could actually buy.
The Biggest Sign You May Be Ready?
It isn't your age.
It isn't getting married.
It isn't having kids.
It isn't hitting some magical salary.
It's this:
You're financially curious enough to find out.
Because there's a huge difference between:
“I don't think I can buy.”
and
“I talked with a lender, reviewed my numbers and now I know what I need to do.”
One is an assumption.
The other is a plan.
What If You're Not Ready Yet?
Perfect.
Seriously.
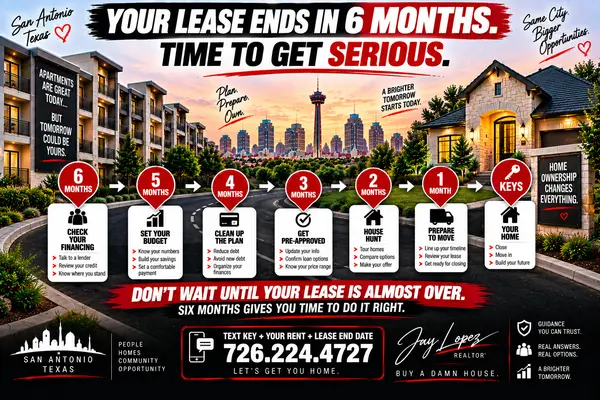
Suppose you talk with a lender and discover you need:
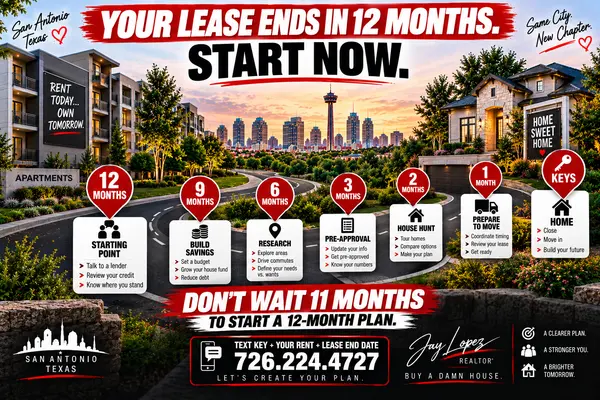
Six months.
Now we build a six-month plan.
Maybe you need to:
Save additional money
Reduce certain debt
Address specific credit issues
or simply allow more time.
Now your next lease renewal isn't:
“Well...maybe next year.”
It's:
“Here's what I'm working toward.”
That's completely different.
What If You ARE Ready?
Then we move to the next questions:
What's your comfortable monthly payment?
Which areas around San Antonio fit your needs?
Resale or new construction?
What financing makes sense?
When does your lease end?
What are your must-haves?
Then we build the home search around those answers.
Take the 5-Sign Test
Give yourself one point for each statement that applies:
✅ My income and finances are relatively stable.
✅ I'm consistently saving money.
✅ My monthly rent has me wondering what ownership might cost.
✅ I want more control over my living space.
✅ I expect to remain in the area long enough to seriously consider ownership.
Here's the important part:
This isn't a mortgage qualification test.
Getting five points doesn't mean:
“Congratulations! You're approved!” 😂
And getting two doesn't mean you can't buy.
It's simply a way to identify whether it's worth having the conversation.
Your actual readiness depends on your finances, financing, property and personal circumstances.
Still Renting? Let's Find Out Where You Stand.
I'm not asking you to buy a house tomorrow.
I'm asking you to stop guessing.
🔑 Text KEY to 726.224.4727
Send me:
Your monthly rent
Your lease expiration
and
Where you'd like to live around San Antonio.
Example:
“KEY — $1,850 — February — Far West Side.”
We'll start there.
No imaginary internet qualification.
Real numbers. Real options. Your decision.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts