Your Lease Ends in 90 Days—Is It Too Late to Start Buying a Home?
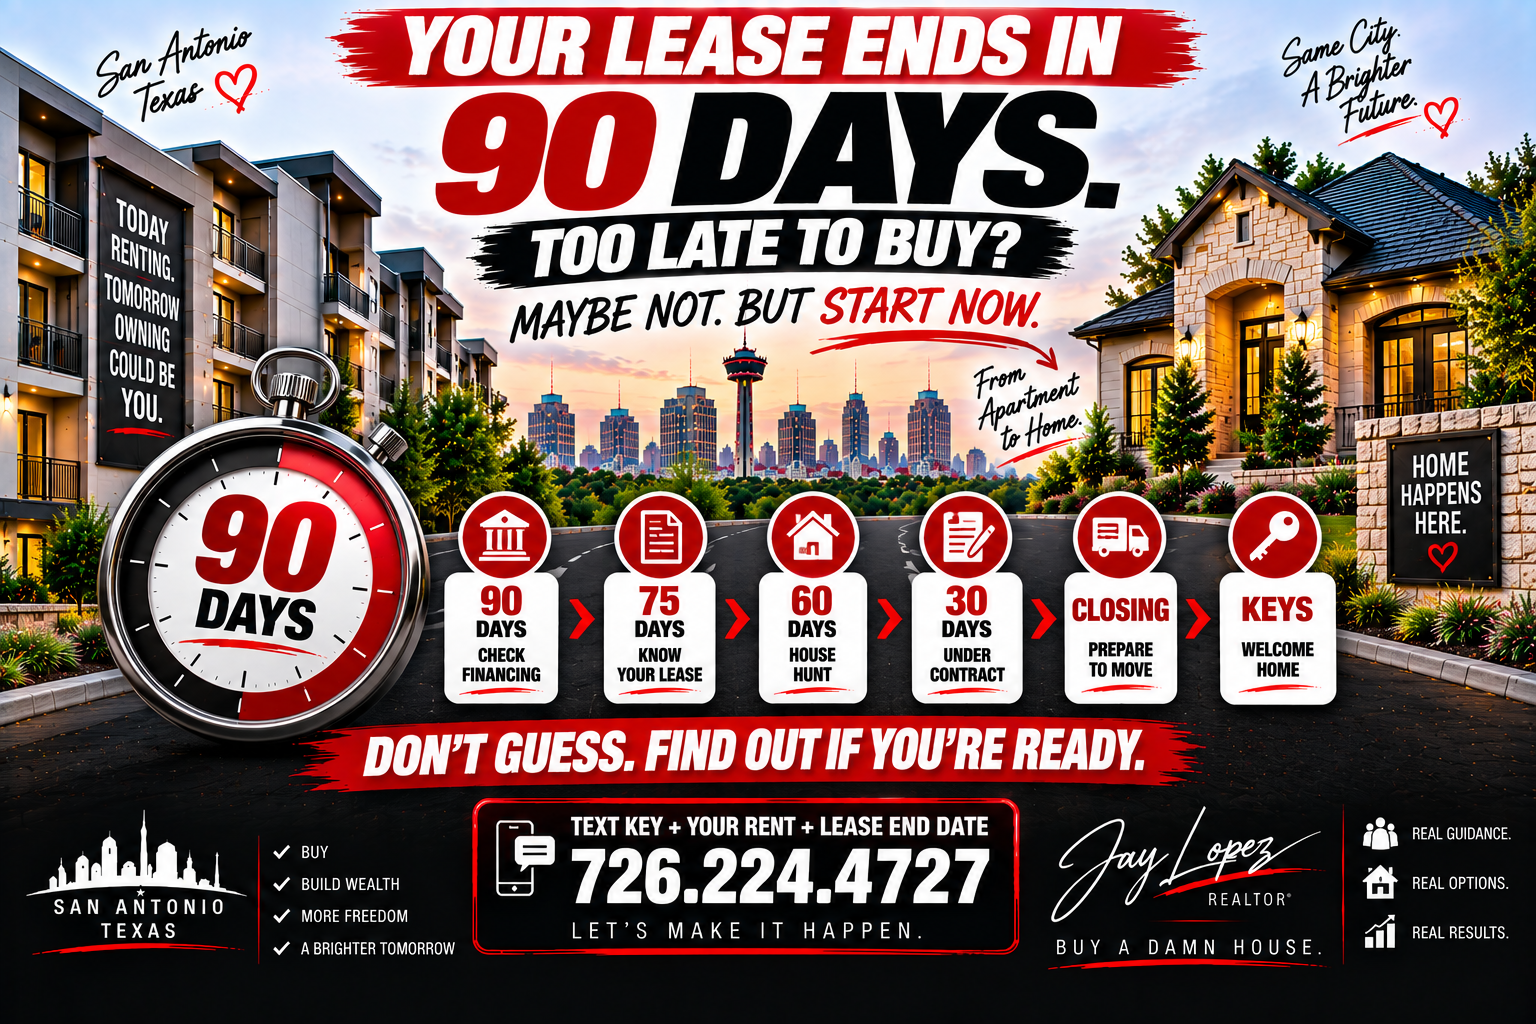
You just looked at your lease.
Then you looked at the calendar.
And realized:
“Oh crap. My lease ends in 90 days.” 😳
You've been thinking about buying a house.
You just haven't actually done anything about it yet.
So now you're wondering:
Did I wait too long?
Not necessarily.
But we're officially out of:
“I'll get around to it.”
And into:
“Let's figure this out NOW.” 🔑
Ninety days can still give some buyers time to purchase a home, depending on their financial readiness, financing, available homes, contract timing and other factors.
But we need answers quickly.
Here's where I would start.
Step 1: Don't Start With Houses
I know.
You have 90 days.
Your instinct is probably:
OPEN ZILLOW IMMEDIATELY.
😂
But finding the house isn't the first problem we need to solve.
We need to determine whether you're financially positioned to buy.
So your first call should be to a qualified mortgage lender.
Tell them:
“My lease expires in 90 days, and I'd like to know if buying a home is realistic for me.”
Now we're working with facts instead of assumptions.
Find Out Where You Stand Financially
A lender can review your situation and help you understand things such as:
Potential financing options
Credit considerations
Debt-to-income
Income documentation
Estimated monthly payment
Potential cash needed
and
Whether you're currently positioned for mortgage approval.
There are basically three possible answers:
1. You're ready.
Great. Let's move.
2. You're close.
Maybe there are specific issues that can reasonably be addressed.
3. You're not ready yet.
That's valuable information too.
Because now we can stop trying to force an unrealistic 90-day timeline and build a better plan.
Don't Assume Your Credit Automatically Disqualifies You
One of the most common things renters tell me is:
“I haven't talked to a lender because my credit isn't good enough.”
Then I'll ask:
“What did the lender say?”
And they respond:
“I haven't talked to one.”
🤦♂️
Don't disqualify yourself.
Different mortgage programs and lenders have different requirements.
For example, the VA itself does not establish one universal minimum credit score for VA-backed purchase loans, although individual lenders can establish their own credit standards.
The same basic principle applies elsewhere:
Your situation needs to be evaluated based on the actual financing you're pursuing.
Step 2: Know Your Comfortable Payment
If the lender says buying could be realistic, don't immediately ask:
“What's the MOST I can buy?”
I care much more about:
“What payment can you comfortably live with?”
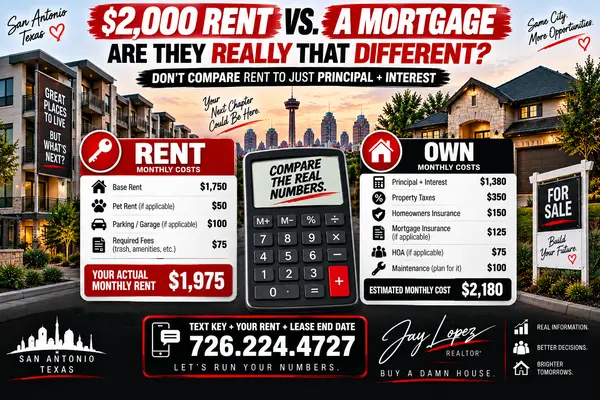
Your housing cost can involve more than principal and interest.
Depending on the property and financing, consider:
Principal
Interest
Property taxes
Homeowners insurance
Mortgage insurance, when applicable
HOA costs, when applicable
plus money for maintenance and repairs.
Your Approval Amount Is Not Your Shopping Target
Let's say you're approved to purchase up to:
$375,000.
That doesn't mean I'm automatically showing you homes from:
$370,000–$375,000.
Maybe your comfortable payment points us toward a $325,000 home.
Then that's where we should be looking.
Buy the payment and house that fit your life—not simply the maximum financing available.
Step 3: Get Pre-Approved
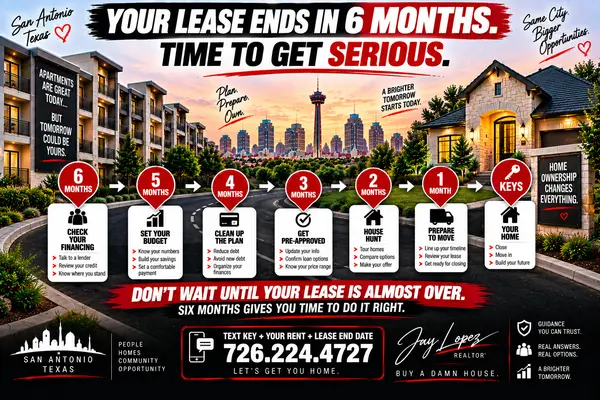
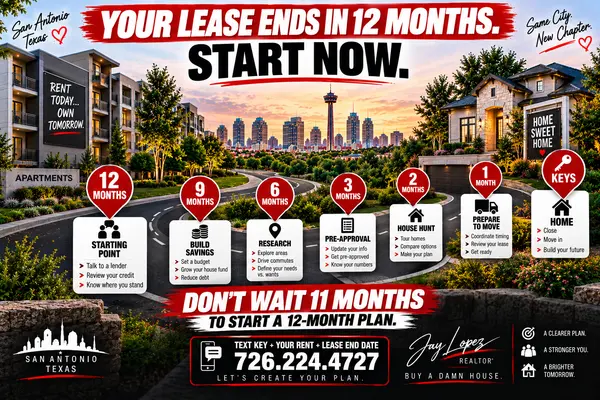
At 12 months out, we have time to casually prepare.
At six months, we're getting serious.
At:
90 DAYS?
If you're financially ready, it's time to discuss pre-approval with your lender.
Because if we're going to start seriously touring homes, I want to understand:
Your financing
Your price range
Estimated payment
Potential cash needed
and
How you're positioned to make an offer.
Step 4: Read Your Lease TODAY
This is one of the most important steps in this entire article.
Find your lease.
Read it.
Specifically look for:
Lease expiration date
Required notice
Renewal provisions
Month-to-month language
Move-out procedures
and any provisions regarding ending the lease early.
Why?
Because:
“My lease expires December 31”
doesn't necessarily tell us everything you need to do before December 31.
Your lease controls your obligations.
You May Have a Notice Deadline Coming Fast
Suppose your lease requires advance notice of your intent to move.
If you're only 90 days away, that deadline may be approaching.
Don't wait until you find a house to investigate your lease.
We need to understand your housing timeline before making decisions.
If you're uncertain about your legal obligations under the lease, get appropriate legal advice.
Step 5: Build a VERY Focused Home Search
We don't have six months to explore every possibility.
So let's narrow this down.
I want to know:
Where do you need to live?
What's your comfortable payment?
How many bedrooms?
What commute works?
New construction or resale?
What are your actual must-haves?
Not your 47-item HGTV wish list.
😂
Your real priorities.
Must Have vs. Nice to Have
At 90 days, this distinction becomes extremely helpful.
MUST HAVE
For example:
Appropriate price/payment
Required bedrooms
Workable commute
Property features you genuinely need
NICE TO HAVE
Maybe:
Kitchen island
Huge backyard
Game room
Oversized shower
Perfect Instagram pantry
Don't lose a house that works because the pantry doesn't make you emotional.
Step 6: Look at Resale AND New Construction
If both fit your goals, don't unnecessarily limit the search.
A resale property and a builder inventory home can present very different opportunities.
And when your lease ends in 90 days, one category of new construction deserves particular attention:
Quick move-in homes.
These are homes builders already have under construction or completed rather than homes you're starting from scratch.
Depending on construction status, financing and other requirements, they may fit a shorter purchase timeline better than a to-be-built home.
Builder Incentives Could Matter
Builders sometimes offer incentives on qualifying inventory.
Depending on current promotions, those could include:
Closing-cost assistance
Financing incentives
Rate buydowns
Price adjustments
or other offers.
But incentives change.
And advertised financing offers normally come with qualifications and conditions.
Verify the current numbers before making your decision.
Don't Walk Into a Builder Alone First
If you want your own Realtor representing you in a new-construction transaction, talk with your Realtor before registering with builders or signing documents.
Builder policies regarding outside-agent representation can vary.
Remember:
The builder's salesperson represents the builder.
You should understand who represents whom before you begin the process.
Step 7: When You Find the House, Be Ready to Act
Focused doesn't mean reckless.
We're not buying:
“Whatever house we can get before the lease ends.”
Absolutely not.
But if we've already established:
Budget
Financing
Location
Needs
and
Timeline
then when the right property appears, we're in a better position to evaluate it.
A Strong Offer Is More Than Price
Don't automatically assume:
“I'll just offer more money.”
An offer contains multiple negotiated terms.
Depending on the transaction, those can involve:
Price
Financing
Earnest money
Option period
Closing timeline
and other contract provisions.
We'll evaluate the situation and build an offer that reflects your goals.
Step 8: You're Under Contract—Now Watch the Clock
Once you're under contract, things start moving quickly.
Depending on your transaction and contract, you'll be dealing with items such as:
Earnest money
Option fee
Inspection
Financing
Appraisal
Insurance
Title
Potential negotiations
and
Closing.
This is not the time to disappear for a week.
😂
Pay attention to emails, phone calls and deadlines.
Schedule the Inspection Quickly
If your Texas contract includes a negotiated termination option, that period matters.
Use the available time wisely.
Get the inspection scheduled promptly.
If something is discovered that needs further evaluation, you'll want time to investigate before applicable contractual deadlines.
VA Buyers: Your Appraisal Is NOT Your Home Inspection
This is especially important in San Antonio.
A VA appraisal evaluates value and certain VA Minimum Property Requirements.
It is not a substitute for a professional home inspection.
They're different things serving different purposes.
Don't skip an inspection simply because the property will receive a VA appraisal.
Step 9: Keep Your Financial Life Boring
You're under contract.
You're excited.
And you know what would look amazing parked in the driveway?
A brand-new truck.
NO. 😂
Not yet.
Your lender may continue verifying financial information before closing.
Don't suddenly:
Finance a vehicle
Open new credit
Buy furniture on credit
Take out a personal loan
or make other significant financial changes without speaking with your lender.
Don't Change Jobs Without Talking to Your Lender Either
Life happens.
Sometimes employment changes are unavoidable.
But if you're considering changing jobs while you're obtaining mortgage financing, talk with your lender first.
Income and employment can be important parts of mortgage qualification.
Don't surprise underwriting three days before closing.
Step 10: Coordinate Closing With Your Lease
Here's where renters sometimes get themselves into trouble.
They try to create the perfect transition:
Lease ends Friday.
Close Friday morning.
Get keys Friday afternoon.
Move Friday night.
Perfect!
Until closing gets delayed.
😬
Give Yourself Some Breathing Room
Real estate transactions involve moving pieces.
Financing.
Appraisal.
Title.
Insurance.
Contract requirements.
Seller logistics.
Funding.
Trying to eliminate every single day of overlap can create unnecessary risk and stress.
When possible, some flexibility between your rental and your home purchase can make moving significantly easier.
What If 90 Days Isn't Enough?
Then don't force it.
Seriously.
Buying a home just because:
“MY LEASE IS ENDING!”
is not a good reason to purchase the wrong property or stretch yourself financially.
If you're not ready, investigate your rental options.
Depending on what your landlord offers and what your lease permits, those might include:
Renewal
A shorter renewal
Month-to-month
or another arrangement.
The options depend on your specific rental situation.
Renting a Little Longer Isn't Failure
This matters.
If the lender says:
“Give me six months.”
Great.
Now you have a target.
Maybe you need to:
Build savings
Address debt
Work on specific credit issues
or improve another aspect of your financial profile.
Then we create:
The next 6-month plan.
The goal isn't to buy a house at any cost.
The goal is to put you in a position to make a smart purchase when you're ready.
What If You're Ready Right Now?
Then things get interesting. 🔥
If:
Financing is lined up
Your budget works
Your lease timeline works
and
We can find the right property
then we move.
Not recklessly.
Efficiently.
There's a difference.
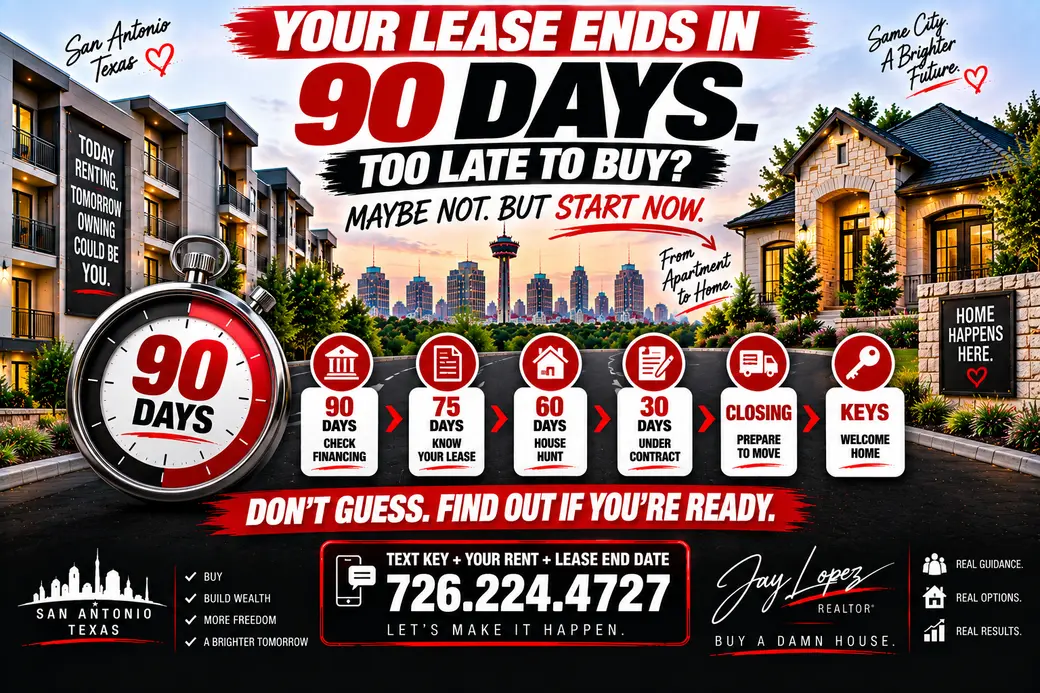
Your 90-Day Home-Buying Game Plan
Here's the simplified version:
DAYS 90–75
🏦 Talk with a lender
📄 Review your lease
💰 Establish your budget
✅ Work toward pre-approval if ready
DAYS 75–60
📍 Narrow locations
🏠 Build your home search
🚗 Test commutes
🏗️ Compare resale and new construction
DAYS 60–30
🔎 Tour homes
📝 Evaluate offers
🤝 Get under contract when the right opportunity appears
DAYS 30–CLOSING
🔍 Inspection
🏦 Financing
📊 Appraisal when required
🛡️ Insurance
📑 Title and closing preparation
📦 Coordinate your move
THEN...
🔑 GET THE KEYS.
Your exact timeline can vary based on your financing, property, contract and circumstances.
But the important thing is:
Start today.
Your Lease Ends in 90 Days?
Don't spend the next 60 days wondering whether you could buy.
Let's find out.
🔑 Text KEY to 726.224.4727
Send:
Your monthly rent
Your exact lease expiration
and
Where you'd like to live around San Antonio.
Example:
“KEY — $2,050 — December 31 — Northeast San Antonio.”
We'll start with the timeline.
Follow @jaylopezrealtor for San Antonio homes, VA information, new construction, first-time buyer education and real estate tips.
Buy a damn house.
Featured Image Concept
This should feel more urgent than Blogs #19 and #20.
Main Headline
YOUR LEASE ENDS IN 90 DAYS. TOO LATE TO BUY?
Large answer underneath:
MAYBE NOT. BUT START NOW. 🔑
Create a bold 90-day countdown graphic moving from an apartment toward a San Antonio home.
90 DAYS
🏦 CHECK FINANCING
75 DAYS
📄 KNOW YOUR LEASE
60 DAYS
🏠 HOUSE HUNT
30 DAYS
📝 UNDER CONTRACT
CLOSING
📦 PREPARE TO MOVE
🔑 KEYS
🏠 WELCOME HOME
Add a large clock/countdown element to make this one visually distinct from the previous roadmaps.
Bottom:
DON'T GUESS. FIND OUT IF YOU'RE READY.
TEXT KEY + RENT + LEASE END DATE
726.224.4727
San Antonio skyline/Tower of the Americas, apartment on one side and attainable modern home on the other.
Jay Lopez | REALTOR®
Buy a damn house.
Categories
Recent Posts