Before You Renew Your Lease in San Antonio, Read This
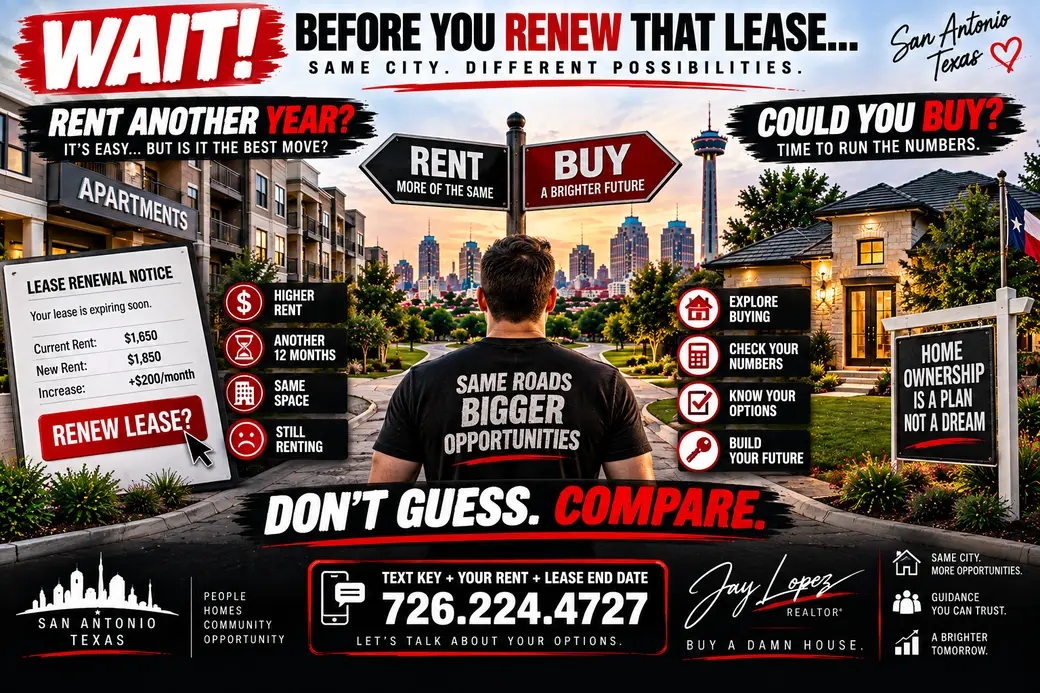
Your apartment sends you the email.
“It's time to renew your lease.”
Maybe the rent is going up.
Maybe it's staying about the same.
Maybe they're offering you some kind of renewal special.
So you do what you've done before:
Open the email.
Look at the new payment.
Complain about it for five minutes. 😂
And then click:
RENEW FOR ANOTHER 12 MONTHS.
Before you do that this time, I want you to ask one question:
Could buying a home actually be an option for me?
I'm not saying everybody should buy a house.
I'm saying you should know your options before committing to another year of renting.
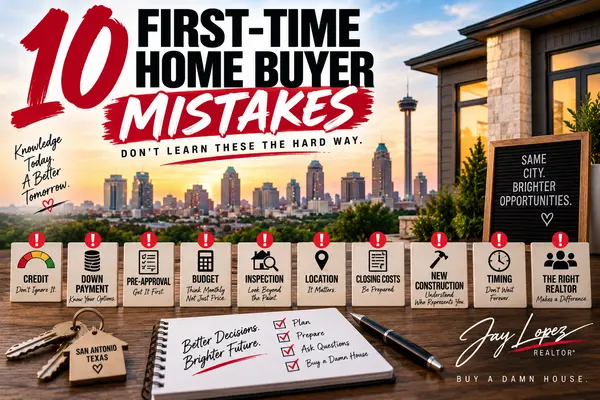
1. Don't Assume You Can't Buy
This is probably the biggest reason renters never investigate homeownership.
They've already decided:
“My credit isn't good enough.”
“I don't have 20% down.”
“Homes are too expensive.”
“My payment would be way higher.”
“I'll look into it next year.”
Maybe buying doesn't make sense for you right now.
That's completely possible.
But shouldn't we figure that out using your actual numbers instead of assumptions?
2. You May Not Need 20% Down
Let's get this one out of the way.
You do not automatically need 20% down to buy a home.
Depending on eligibility and financing, buyers may have access to options such as:
Conventional financing with lower down-payment options
FHA financing
VA financing for eligible military borrowers and Veterans
USDA financing for eligible borrowers and properties
and potentially
Down-payment assistance programs
Each option has its own requirements, costs and tradeoffs.
But if the only reason you haven't investigated buying is:
“I don't have 20% saved.”
Talk to a qualified lender before ruling yourself out.
3. Compare Your Rent to the TOTAL Cost of Owning
Here's where we need to be careful.
If you're paying:
$1,800 per month in rent
that does not automatically mean:
“You can buy a house for an $1,800 mortgage payment.”
Homeownership costs can include:
Principal
Interest
Property taxes
Homeowners insurance
Mortgage insurance, when applicable
HOA costs, when applicable
plus maintenance and repairs.
So we're not comparing:
Rent vs. principal and interest.
We're comparing:
Rent vs. the realistic cost of owning the property.
That's a much better conversation.
4. Find Out What a Real Payment Could Look Like
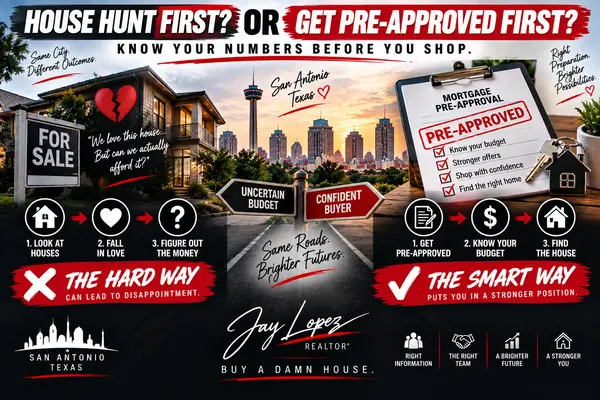
Before renewing your lease, talk with a lender.
Not because you're committing to buy.
Not because you're making an offer tomorrow.
And definitely not because some Realtor is going to chase you around San Antonio with a contract. 😂
You're gathering information.
A lender can help you understand:
What financing you may qualify for
What purchase price range may be possible
How much cash may be needed
and
What estimated monthly payments could look like.
Now you have something useful to compare with your lease renewal.
5. Your Maximum Approval Isn't Your Budget
Let's say a lender tells you that you may qualify up to a certain amount.
Great.
That doesn't mean:
“Go spend every dollar of it.”
Your comfortable housing budget should also account for your life.
Do you:
Travel?
Eat out?
Have car payments?
Help family?
Want to save?
Have hobbies?
Plan to replace your vehicle?
Want an emergency fund?
Your house shouldn't make everything else in your life impossible.
6. Check Your Credit Before the Lease Deadline
Maybe you're ready financially.
Maybe your credit needs some work.
Either way, wouldn't you rather know before you've committed to another 12-month lease?
If there are credit issues, a lender may be able to explain what factors are affecting your mortgage profile and what steps may be worth considering.
Maybe you can buy now.
Maybe you need six months.
Maybe you need a year.
That's still valuable information.
Because now you have a plan.
7. Don't Make Random “Credit Fixes”
This deserves its own section.
Please don't start doing things like:
Closing old credit cards
Opening three new accounts
Paying random collections
or
Financing a new truck
because somebody on Facebook told you it would improve your mortgage approval. 😂
Actions involving your credit can affect your mortgage application in different ways.
If you're preparing to buy, talk with the lender handling your mortgage strategy before making significant credit moves.
8. How Much Cash Would You Actually Need?
This is another reason renters assume they can't buy.
They imagine needing:
$40,000.
Maybe your transaction requires substantial cash.
Maybe it doesn't.
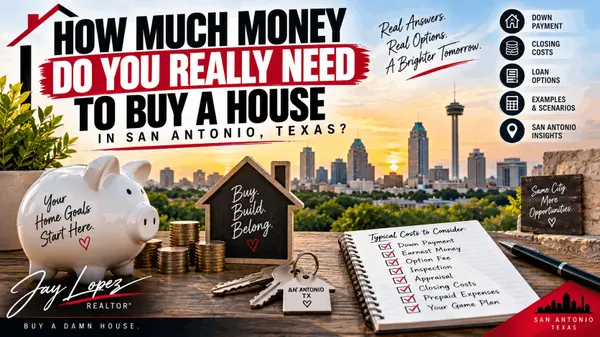
The amount depends on factors such as:
Purchase price
Loan program
Down payment
Closing costs
Prepaid expenses
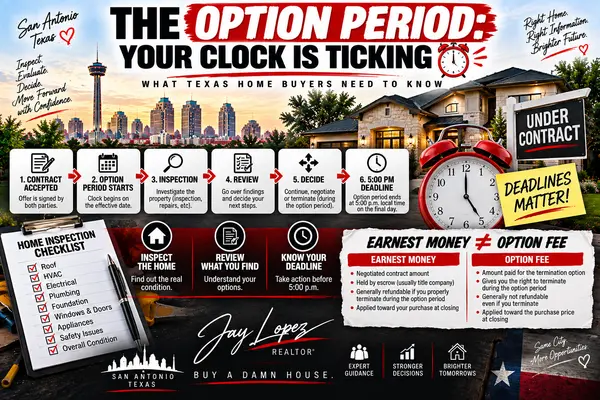
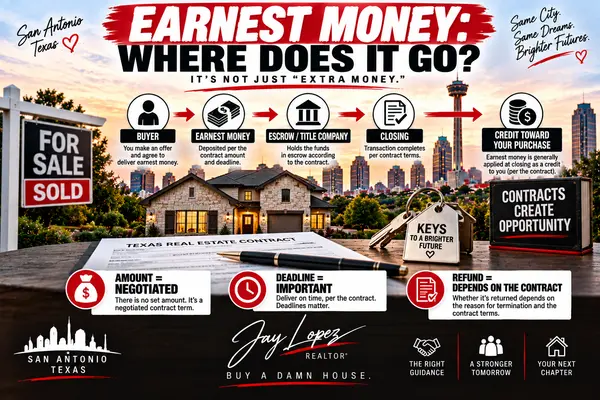
Earnest money
Option fee
and potential negotiated credits or assistance.
The only useful number is the number associated with your situation.
9. Seller Contributions May Be Possible
Depending on the transaction and financing program, a buyer may negotiate for the seller to contribute toward certain allowable costs.
Is the seller required to do that?
No.
Can we guarantee it?
No.
Does it happen in real estate transactions?
Yes.
Whether it makes sense depends on the property, offer strategy, market conditions, financing and seller.
That's why we look at the entire deal rather than one number.
10. New Construction May Be Worth Comparing
If you're renting in San Antonio, don't automatically assume new construction is outside your budget.
Builders sometimes offer incentives on qualifying homes through preferred lenders or other programs.
Depending on the builder and current promotion, incentives might involve things such as:
Closing-cost assistance
Financing incentives
Rate buydowns
or
Price adjustments.
These offers change frequently and come with qualifications.
Always verify the current terms.
But they're worth comparing with resale homes when appropriate.
11. Military Renters: Check Your VA Eligibility 🇺🇸
San Antonio has a huge military community.
If you're an eligible Veteran or service member, your VA home loan benefit may provide significant advantages.
Eligible borrowers with sufficient entitlement may potentially purchase with:
No down payment required by the VA loan program.
VA itself also doesn't establish a universal minimum credit score, although individual lenders may have their own requirements.
And some eligible Veterans may be exempt from the VA funding fee.
If you're stationed around JBSA and renting because you assume buying requires a huge down payment, it may be worth talking with a VA-experienced lender.
12. Your Lease End Date Is Part of the Home-Buying Plan
Timing matters.
If your lease ends next week and you haven't:
Talked with a lender
Started looking
or
Prepared financially
buying immediately may be difficult.
But if your lease expires several months from now?
Perfect.
We have time to plan.
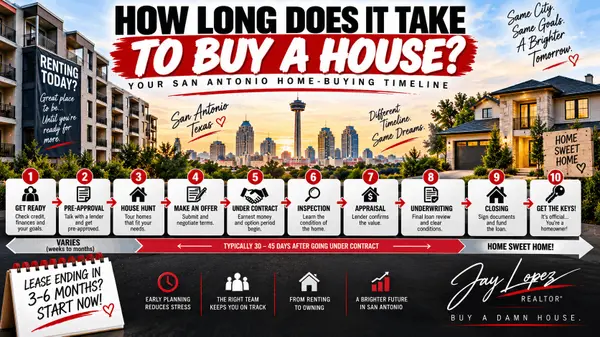
13. Six Months Before Your Lease Ends
This is a great time to start investigating.
You can:
Review your finances
Talk with a lender
Check your credit
Build savings
Learn about financing
Identify target areas
and
Start watching the market.
You don't necessarily need to start touring houses tomorrow.
We're preparing.
14. Three Months Before Your Lease Ends
Now things can become more active.
Depending on your financial readiness and timeline, this may be when you:
Update your pre-approval
Define your budget
Narrow locations
Compare resale and new construction
and potentially
Begin serious house hunting.
The goal is to coordinate the purchase timeline with your lease as reasonably as possible.
15. Don't Time It So Tightly That Everything Has to Be Perfect
I understand the dream:
Apartment lease ends Friday.
Close on house Friday morning.
Move Friday afternoon.
Never pay one overlapping day.
Sounds great.
Real estate transactions, however, have moving pieces.
Financing.
Appraisal.
Title.
Repairs.
Closing.
Funding.
Your move.
Sometimes having a little flexibility is worth far more than trying to engineer the world's most perfect 12-hour transition.
16. Check Your Lease Before Making Plans
Don't assume you know what your lease requires.
Read it.
Important items may include:
Expiration date
Notice requirements
Renewal provisions
Month-to-month terms
Early termination provisions
and other obligations.
If you have questions about your legal rights under the lease, seek appropriate legal guidance.
Your home-buying strategy should work with the lease you're actually under.
17. What If Your Lease Doesn't End for Nine Months?
That's okay.
In fact, that can be a great position.
You have time.
Maybe you spend the next few months:
Improving your mortgage profile
Reducing debt
Building savings
Researching neighborhoods
and learning the buying process.
You don't need to buy tomorrow to start preparing today.
18. What If Buying Doesn't Make Sense Right Now?
Then don't buy.
Seriously.
Maybe:
You expect to move soon.
Your employment situation may change.
You don't have enough emergency savings.
You prefer the flexibility of renting.
The available ownership costs don't work for your budget.
Those are legitimate considerations.
The point of this exercise isn't:
“Everyone needs to buy immediately.”
The point is:
“Make the decision with information.”
19. Renting Can Be the Right Decision
I sell houses.
And I'm still going to tell you this:
Renting can absolutely make sense.
Homeownership comes with responsibilities.
When the air conditioner breaks?
You don't call the apartment office anymore. 😂
You own the problem.
When the roof eventually needs replacement?
That's your roof.
Homeownership can offer benefits, including the potential to build equity over time, but it also comes with costs and risk.
Know both sides.
20. But Don't Renew Just Because It's Easy
This is the part I really want renters to think about.
Renewing a lease is easy.
You already live there.
No moving truck.
No mortgage process.
No inspections.
No house hunting.
Just sign.
And another year passes.
If renting still makes sense after you've evaluated the alternatives?
Renew the lease confidently.
But if buying might work?
You deserve to know that before locking yourself into another year.
The Lease-Renewal Test
Before signing another lease, answer these five questions:
1. What will my new monthly rent be?
2. How long do I expect to stay in San Antonio?
3. Have I actually talked with a mortgage lender?
4. Do I know what buying could realistically cost me?
5. If I rent another year, what am I trying to accomplish financially during that year?
That last one is important.
If the answer is:
“I need another year to prepare.”
Great.
Then let's create a 12-month preparation plan.
Don't simply wait 12 months and find yourself asking the same questions again.
Your Lease Is Up. Let's Run the Numbers.
You don't have to decide today whether you're buying a house.
Let's simply find out whether it's possible.
🔑 Text KEY to 726.224.4727
Send me:
Your current monthly rent
and
When your lease expires.
Example:
“KEY — $1,750 rent — lease ends in February.”
That's enough to start the conversation.
We'll figure out what your next step should be.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts