How to Prepare to Buy a Home 12 Months Before Your Lease Ends
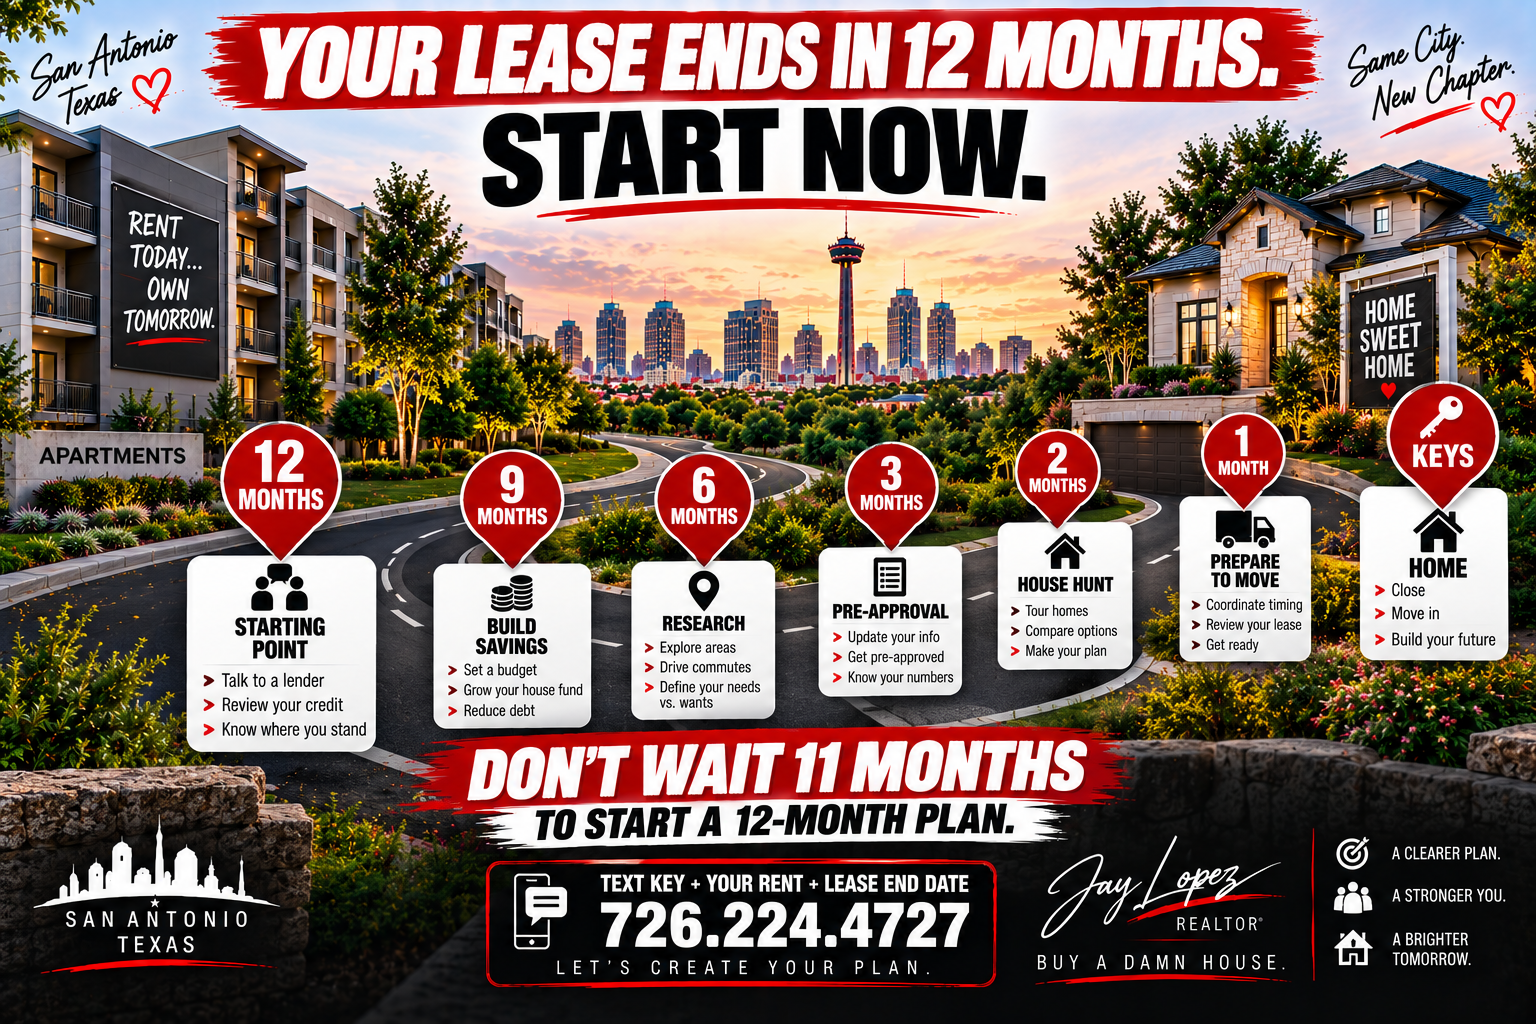
Your lease doesn't expire for another year.
So buying a house is something you'll worry about later.
Right?
Wrong. 😂
Actually, having 12 months before your lease expires can put you in a great position.
You don't need to rush.
You don't need to start touring houses this weekend.
And you definitely don't need to spend the next 11 months scrolling through homes online that will probably be sold before you're ready.
Instead, use the next year to get yourself prepared.
12 months isn't “too early.” It's preparation time.
Here's the game plan.
Month 12: Find Out Where You Actually Stand
The first thing I want you to do is surprisingly simple:
Gather information.
Before deciding you need to:
Improve your credit
Save $30,000
Pay off your car
or
Wait another three years
find out what your actual situation looks like.
Talk with a qualified mortgage lender.
Tell them:
“My lease expires in about 12 months and I'd like to prepare to buy.”
You're not asking them to magically get you into a house tomorrow.
You're building a plan.
What Should You Learn From That First Conversation?
You want a better understanding of:
Your current mortgage profile
Potential financing options
Credit factors that may affect you
Your debt-to-income picture
Potential down-payment requirements
Possible closing costs
and
What areas need attention before you're ready.
Maybe you're closer than you thought.
Maybe you have work to do.
Either answer is useful.
Month 11: Review Your Credit Strategy
Notice I said:
Review your credit strategy.
Not:
Go randomly “fix” your credit.
Please don't start closing accounts, opening new cards or paying things without understanding how those actions may affect a future mortgage application.
Mortgage lending can evaluate credit differently than a consumer credit app.
If your lender identifies areas that deserve attention, build a plan around those specific items.
Your Credit Doesn't Need to Be Perfect
One of the biggest misconceptions among renters is:
“I need an 800 credit score to buy a house.”
No.
Different loan programs and lenders have different requirements.
VA itself, for example, doesn't establish one universal minimum credit score, although individual lenders may impose their own standards.
Conventional, FHA, USDA and other financing options also have their own requirements.
Your job isn't to achieve some random internet score.
Your job is to become financially prepared for your financing strategy.
Month 10: Get Serious About Your Budget
Now let's look at your money.
Not just:
“How much house can I qualify for?”
Instead ask:
“How much housing payment would I actually be comfortable with?”
Look at your current spending.
Housing.
Cars.
Insurance.
Food.
Subscriptions.
Travel.
Entertainment.
Debt.
Savings.
Everything.
Your lender may eventually tell you the maximum financing available.
That doesn't mean you have to spend the maximum.
Create a “Future Home Payment” Test
Here's a useful exercise.
Suppose you're currently spending:
$1,700 per month on rent
and after preliminary planning you think a comfortable future housing budget might be around:
$2,000 per month.
Consider practicing the difference.
Keep paying your $1,700 rent.
Then move:
$300
into savings each month.
You're accomplishing two things:
Building savings
and
Testing whether that future budget actually feels comfortable.
If $300 completely wrecks your finances?
That's useful information too.
Month 9: Start Building Your House Fund
Create a separate savings bucket.
Call it:
HOUSE MONEY. 🏠
This isn't:
Vacation money
New television money
Emergency margarita money. 😂
It's for the future purchase.
Depending on your transaction, you may eventually need funds for things such as:
Down payment
Closing costs
Prepaid expenses
Earnest money
Option fee
Inspections
Moving expenses
and reserves after closing.
Don't Empty Your Bank Account to Buy a House
I don't want your financial plan to look like:
Closing Day:
$23 left in checking.
Day After Closing:
Air conditioner makes weird noise.
😐
Owning a house means unexpected expenses can happen.
Keeping emergency savings after the purchase should be part of the conversation.
Month 8: Look at Your Debt
Now review your monthly obligations.
That might include:
Car payments
Credit cards
Student loans
Personal loans
and other debt.
Debt can affect mortgage qualification because lenders evaluate your monthly obligations relative to qualifying income.
But don't automatically assume:
“Pay everything off immediately.”
Sometimes preserving cash may be important too.
Talk with your lender before making major financial moves specifically for mortgage qualification.
Month 7: Stop Adding Unnecessary Debt
We're getting closer.
This probably isn't the ideal time to finance:
A new truck
A boat
$12,000 worth of furniture
or
An entire living room because the store offered zero payments until 2031. 😂
New debt can affect your financial picture.
If you're planning to apply for a mortgage soon, talk with your lender before taking on significant new obligations.
The furniture will still exist after you buy the house.
I promise.
Month 6: Start Learning San Antonio
Now we can begin shifting from:
FINANCIAL PREPARATION
to
HOME-BUYING PREPARATION.
Start identifying areas that may fit your needs.
Think about:
Work commute
Access to major roads
Home style
New construction vs. resale
Lot size
HOA preferences
Budget
and other priorities.
Don't ask:
“What's the best neighborhood?”
Ask:
“Which areas fit what I need?”
That's a much better question.
Military Buyers: Think About Your JBSA Commute 🇺🇸
If you're stationed at:
Lackland
Randolph
Fort Sam Houston
or elsewhere around JBSA, commute can become a major factor.
San Antonio is spread out.
A house that looks close on a map may feel very different during the times you actually travel.
Research routes that match your schedule.
Month 5: Learn the Difference Between Wants and Needs
Create three categories.
MUST HAVE
Examples:
3 bedrooms
Specific commute range
Certain monthly budget
Garage
WOULD LIKE
Examples:
Kitchen island
Large backyard
Game room
Office
BONUS
Examples:
Pool
Outdoor kitchen
Media room
That giant shower you saw on Instagram. 😂
This prevents you from rejecting good homes because they don't have every feature on your dream list.
Month 4: Learn Your Financing Options
Now is a good time to get more specific.
Depending on your eligibility, your lender may discuss options such as:
Conventional
FHA
VA
USDA
or other available programs.
Each has different requirements, costs and advantages.
Don't choose financing based solely on:
“Which one requires the least down?”
Consider the whole financial picture.
VA Buyers: Learn Your Benefit Early
If you're an eligible Veteran or service member, learn how your VA benefit applies to your situation.
Eligible borrowers with sufficient entitlement may potentially purchase with no down payment required by the VA loan program.
VA doesn't itself establish a universal minimum credit score, though lenders can have their own requirements.
Some eligible Veterans may also be exempt from the VA funding fee.
But VA financing still has qualification and property requirements.
Learn the benefit before you're trying to write an offer.
Month 3: Time to Get Serious
Now your lease expiration is approaching.
This is where I want the lender conversation updated.
Your finances may have changed during the previous nine months.
Maybe you've:
Reduced debt
Built savings
Improved your mortgage profile
Received a raise
or
Changed jobs.
Your lender needs current information to determine where you stand now.
Get Pre-Approved Before Serious House Hunting
If you're financially ready, this may be the time to move toward mortgage pre-approval.
That helps us understand:
Potential price range
Estimated payment
Financing structure
and
How much money you may need for the transaction.
Now we're getting close.
Month 2: Start Seriously Shopping
This is where the fun begins. 🔥
Now we can start looking at actual homes that fit:
Your budget
Your financing
Your location
Your timeline
and
Your priorities.
We'll compare:
Resale homes
and, when appropriate,
New construction.
The goal isn't to tour 73 houses.
The goal is to identify homes that actually fit the plan we've spent months creating.
Don't Forget New Construction
San Antonio has substantial new-home development.
Depending on inventory and current promotions, builders may offer incentives on qualifying properties.
These can potentially include:
Closing-cost assistance
Financing incentives
Rate buydowns
Price adjustments
or other promotions.
Builder incentives change and have qualification requirements.
Always verify current terms.
And remember:
The builder's salesperson represents the builder.
Consider having your own representation involved before registering or signing documents.
Month 1: Prepare for the Transition
If you're under contract, now we're coordinating two timelines:
Your home purchase
and
Your lease.
Review your lease carefully.
Know:
Your expiration date
Required notice
Move-out procedures
and any other relevant obligations.
Don't simply assume:
“My lease ends on the 30th, so I'm good.”
Read what you signed.
Don't Try to Make the Timing Too Perfect
Everybody wants this:
9:00 a.m. — Close on house
10:00 a.m. — Get keys
Noon — Lease ends
12:01 p.m. — Move everything
$0 overlap
😂
Real estate doesn't always cooperate that perfectly.
Financing, title, appraisal, repairs and closing logistics can affect timing.
A little overlap between your rental and your new home can sometimes reduce stress considerably.
Build flexibility when possible.
What If You're NOT Ready at Month 3?
This is important.
Suppose we started 12 months out.
You did everything.
But when we reach Month 3, you're not financially ready.
That's okay.
Don't force the purchase.
Maybe you:
Renew for six months
Go month-to-month if available and appropriate
Renew another year
or choose another option permitted by your lease.
The difference?
You're not guessing anymore.
You know exactly what needs to happen next.
What If You're Ready EARLY?
That can happen too.
Maybe we talk with the lender at Month 12 and discover:
“Wait...I could actually buy now?”
Interesting.
Now we evaluate the lease.
Maybe buying early still doesn't make sense.
Maybe there are contractual costs associated with ending the lease.
Maybe you simply wait.
Or maybe another solution exists under your lease.
Don't break a lease based on assumptions.
Understand your obligations first.
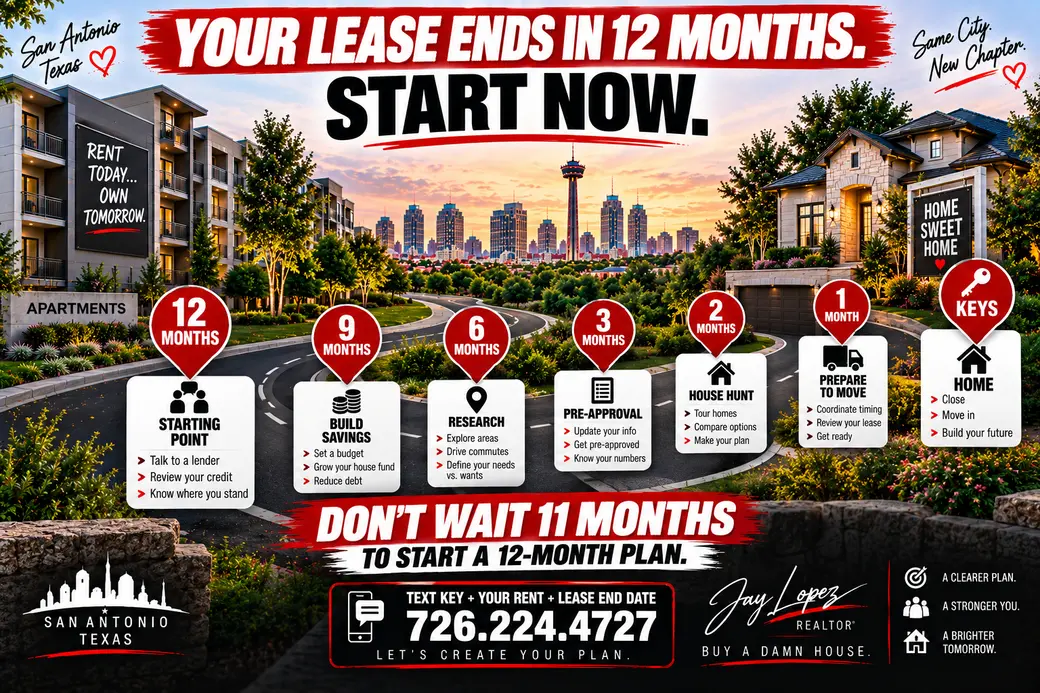
Your 12-Month Home-Buying Calendar
Here's the whole plan:
12 Months Out
Talk with a lender and establish your starting point.
11 Months
Review your credit strategy.
10 Months
Set your comfortable monthly housing budget.
9 Months
Build your house fund.
8 Months
Review debt and monthly obligations.
7 Months
Avoid unnecessary new debt.
6 Months
Research San Antonio areas and commute.
5 Months
Build your must-have / would-like / bonus list.
4 Months
Learn your financing options.
3 Months
Update lender information and prepare for pre-approval.
2 Months
Begin serious house hunting if ready.
1 Month
Coordinate your purchase, closing and lease transition.
And then...
🔑 KEYS.
One Year From Now Is Coming Either Way
Here's what I want you to remember.
Twelve months from today, you'll be twelve months older.
Your lease may be ending again.
The question is:
Will you still be saying:
“Maybe I'll buy someday.”
Or will you have spent the year figuring out exactly what it takes?
Even if you decide renting is still the right choice, you've made that decision with better information.
That's progress.
Want a 12-Month Home-Buying Plan?
Let's build one around your lease, not some generic timeline.
🔑 Text KEY to 726.224.4727
Send me:
Your monthly rent
Your lease expiration month
and
Where you'd like to live around San Antonio.
Example:
“KEY — $1,800 — September 2027 — Northwest San Antonio.”
We'll start from there.
Follow @jaylopezrealtor for San Antonio homes, new construction, VA information, first-time buyer education and real estate tips.
Buy a damn house.
Categories
Recent Posts